
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is IDC WAAP Leader Status Altering The Investment Case For F5 (FFIV)?
- F5 was recently named a Leader in the IDC MarketScape Worldwide WAAP Platforms 2026 Vendor Assessment, with IDC highlighting its AI powered WAF, broad AI security options, and converged protection across web apps, APIs, bots, and DDoS.
- The IDC recognition underscores how F5’s unified WAAP offering targets customer pain points around multicloud complexity and security gaps across hybrid environments, directly linked to its core mission of securing distributed applications.
- We will look at how F5's investment narrative is influenced by IDC's WAAP leadership callout around AI powered application security.
Scan beyond F5 and see how other security and AI focused application providers line up in our hand picked list of 90 AI infrastructure stocks.
F5 Investment Narrative Recap
For an investor in F5, the core belief is that multicloud complexity and heavier AI workloads keep pushing enterprises toward a unified platform for application delivery and security. The IDC MarketScape leadership callout supports that story but does not fundamentally change it. In the near term, the key factor still appears to be converting that interest into broader Distributed Cloud and multimodal adoption.
The most immediate risk remains execution on the software and recurring side, while annual recurring revenue has recently grown modestly and hardware still carries weight. Ongoing guidance for lower non GAAP gross margin in FY27 adds another watchpoint, since higher component costs could limit earnings support if pricing or product mix do not shift.
The IDC recognition connects most directly to F5 being early with AI powered application security, including its Distributed Cloud WAF and newer AI Security Platform. Those offerings sit squarely in the web app and API protection category highlighted in the assessment, which is notable as application layer attacks have risen sharply over the past three years.
Regarding potential catalysts, that AI security push aligns with management’s focus on hybrid multicloud and more complex API and AI workloads, along with roughly US$50 million of direct AI bookings in the first half of FY26. Execution risk lies in demonstrating that these WAAP and AI features drive higher security spend per customer without eroding the targeted margin framework.
F5's current analyst setup ties to a projection for about US$4.2b in revenue and US$1.0b in earnings by 2029, based on an assumed 8.1% yearly top line expansion and an earnings increase of roughly US$273.5m from US$726.5m today.
Uncover why F5's fair value indicates a 4% potential downside to its current price, leaving little room for error.
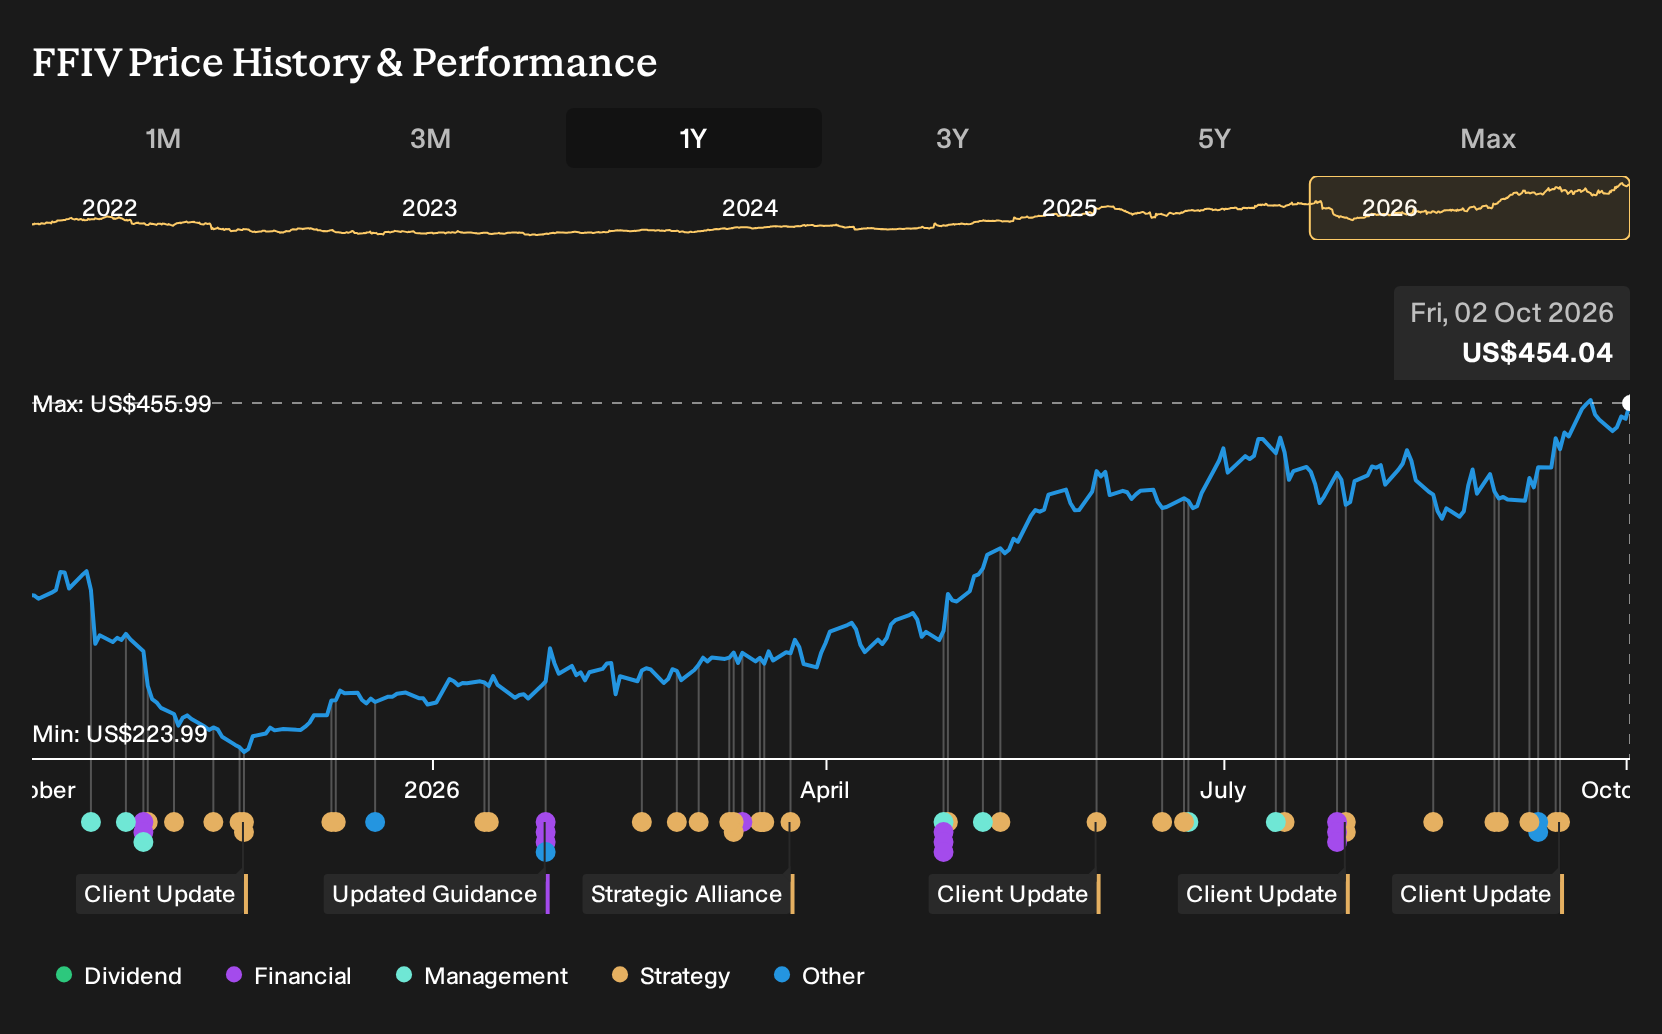
Exploring Other Perspectives
Some of the most optimistic analysts were already leaning on a catalyst that goes beyond IDC’s WAAP callout for F5. They were modeling revenue of about US$4.3b and earnings near US$1.2b by 2029, compared with US$4.2b and US$1.0b in the base case. That shows how far opinions can stretch. The WAAP leadership news may eventually push those narratives closer together or pull them further apart. Treat it as a cue to compare several viewpoints before deciding what this means for you.
Explore 2 other F5 fair value estimates, including one that suggests it could be worth as much as $436.10.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your F5 research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for F5. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate F5's overall financial health at a glance.
Looking For More Ideas Beyond F5?
If this F5 story has sharpened your thinking, broaden your watchlist by scanning for other stocks that fit the type of profile you want to research next.
- For investors hunting for potential mispricing, review a 31 high quality undervalued stocks that currently combine stronger fundamentals with lower implied expectations.
- If capital preservation sits higher on your priority list, filter for 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- When you want early stage opportunities with room for the thesis to develop, check a curated set of 19 high quality undiscovered gems that pair quality metrics with lighter coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com