
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Semtech (SMTC) Justify Its Valuation As It Expands In AI Networks And Security?
Semtech (SMTC) has been busy on three fronts. The group moved its 50G mobile transport portfolio into full production, joined the eXtra-dense Pluggable Optics MSA, and completed an edge security integration with Palo Alto Networks.
Investors have reacted strongly to this run of Semtech announcements, with a 1-month share price return of 45.6% and a year-to-date share price gain of 158.9%. The 3-year total shareholder return of around 7x indicates that long-term momentum has been very strong, and recent moves reflect a sharp pickup in optimism about its role in next generation connectivity and security.
Scan the Semtech story against a wider field and size up other wired into AI infrastructure using our hand-picked 90 AI infrastructure stocks as potential comparables.
After a 7x three year return and a surge that put Semtech within reach of published analyst targets, the question now is simple: Does the current price still compensate buyers for the risks they are taking?
Most Popular Narrative: 7% Undervalued
Semtech last closed at $194.88, while the most widely followed narrative pegs fair value at $210.33. The story now hangs on whether investors agree with some very bullish assumptions on data center and IoT growth.
Accelerating demand from hyperscale data centers and AI infrastructure is described as driving robust, multi-year growth across Semtech's high-margin data center business, supported by design wins in advanced optical (FiberEdge), low-power (LPO), and active copper interconnects (CopperEdge/ACC). As data rates move from 400G to 800G and 1.6T, this narrative suggests that Semtech could capture significant revenue and margin expansion from new content per deployment.
See why 38 investors see Semtech as 7% undervalued.
Result: Fair Value of $210.33 (UNDERVALUED)
Still, Semtech’s story can break if integration issues, such as the recent US$41.9 million goodwill impairment, linger or if the mix shifts toward lower margin IoT continue.
Find out about the key risks to this Semtech narrative.
Another View: What Semtech’s P/E Is Telling You
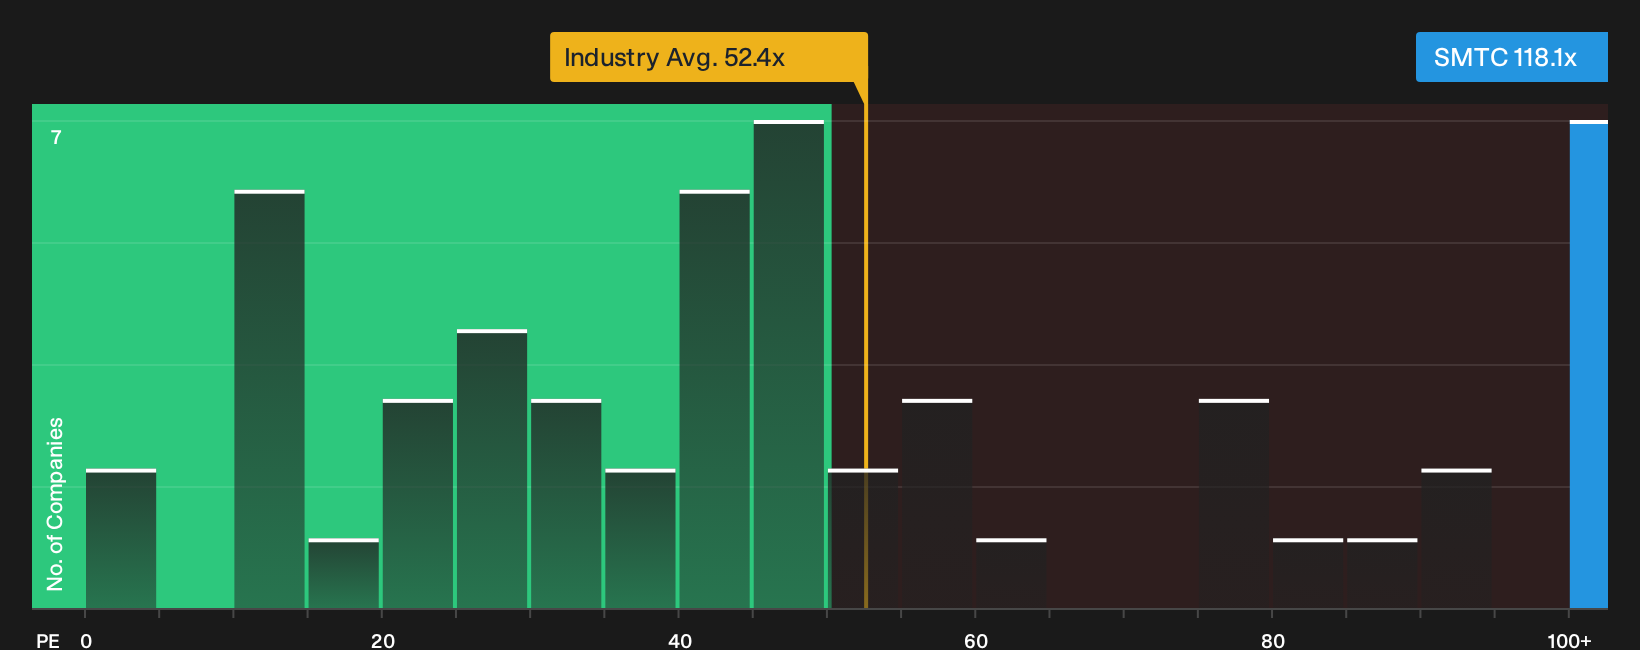
There is a very different message in the simple valuation ratios. Semtech trades on a P/E of 118.1x, while the fair ratio is 47.9x and the US Semiconductor peer average is 52.4x. That gap points to potential valuation risk if sentiment cools or growth stumbles. Where do you think the multiple drifts toward next?
For a closer look at how the current price compares with these ratios and peers, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Semtech is split between excitement and caution, so consider reviewing the numbers yourself, evaluating the situation carefully, and deciding where you stand on its mix of risks and upsides by weighing the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Semtech?
Do not stop your research with Semtech. A wider watchlist can help you spot opportunities earlier and avoid concentrating too much risk in a single story.
- Target rapid growth potential by scanning 9 elite penny stocks with strong financials that pair smaller size with stronger balance sheets and cleaner financial histories.
- Hunt for mispriced quality using the 31 high quality undervalued stocks to surface businesses with solid fundamentals trading at what may be discounted levels.
- Prioritize resilience by reviewing the 31 resilient stocks with low risk scores to see companies screened for lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com