
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Marketing AI Transformation Change The Case For Extreme Networks Stock (EXTR)
- Extreme Networks recently appointed Chloe Tambe as Director, Marketing AI Transformation, tasking her with scaling AI adoption and practical use across the marketing organisation.
- Tambe’s nearly two decades of experience using technology to close efficiency gaps positions Extreme Networks to refine how it applies AI inside its own commercial engine.
- This section examines how Extreme Networks' investment narrative could be influenced by Chloe Tambe's focus on marketing AI transformation.
Extreme Networks Investment Narrative Recap
To own Extreme Networks, you need to believe the business can keep building on its AI powered networking platform while managing heavy exposure to government and public sector budgets. The key near term swing factor is how consistently Extreme converts its pipeline in APAC and EMEA without relying on one off government projects that introduce revenue lumpiness.
Chloe Tambe’s arrival looks important for execution, not for changing the immediate risk profile. Her remit in marketing AI transformation may help Extreme communicate its cloud and subscription offerings more efficiently over time. However, the core challenges around competition, pricing pressure, and tariff or supply chain shifts remain the main operational watchpoints.
There are no other fresh company announcements around this appointment. The clearest link is to Extreme Networks’ existing push on ExtremeCloud IQ and AI driven network management. The new marketing AI role lines up with that focus, aiming to make the commercial side match the technical story.
For you as a shareholder, the operational question is simple: Can Extreme turn product strength in Wi Fi 7, cloud subscriptions, and MSP models into steadier recurring revenue while facing larger rivals? Effective AI enabled marketing execution under Tambe could support that effort over time, but investors still need to track contract concentration and competitive intensity closely.
Extreme Networks' analyst narrative points to US$1.7b in revenue and US$60.2m in earnings by 2029, built on 9.8% yearly top line growth and an earnings increase of about US$18.1m from US$42.1m today.
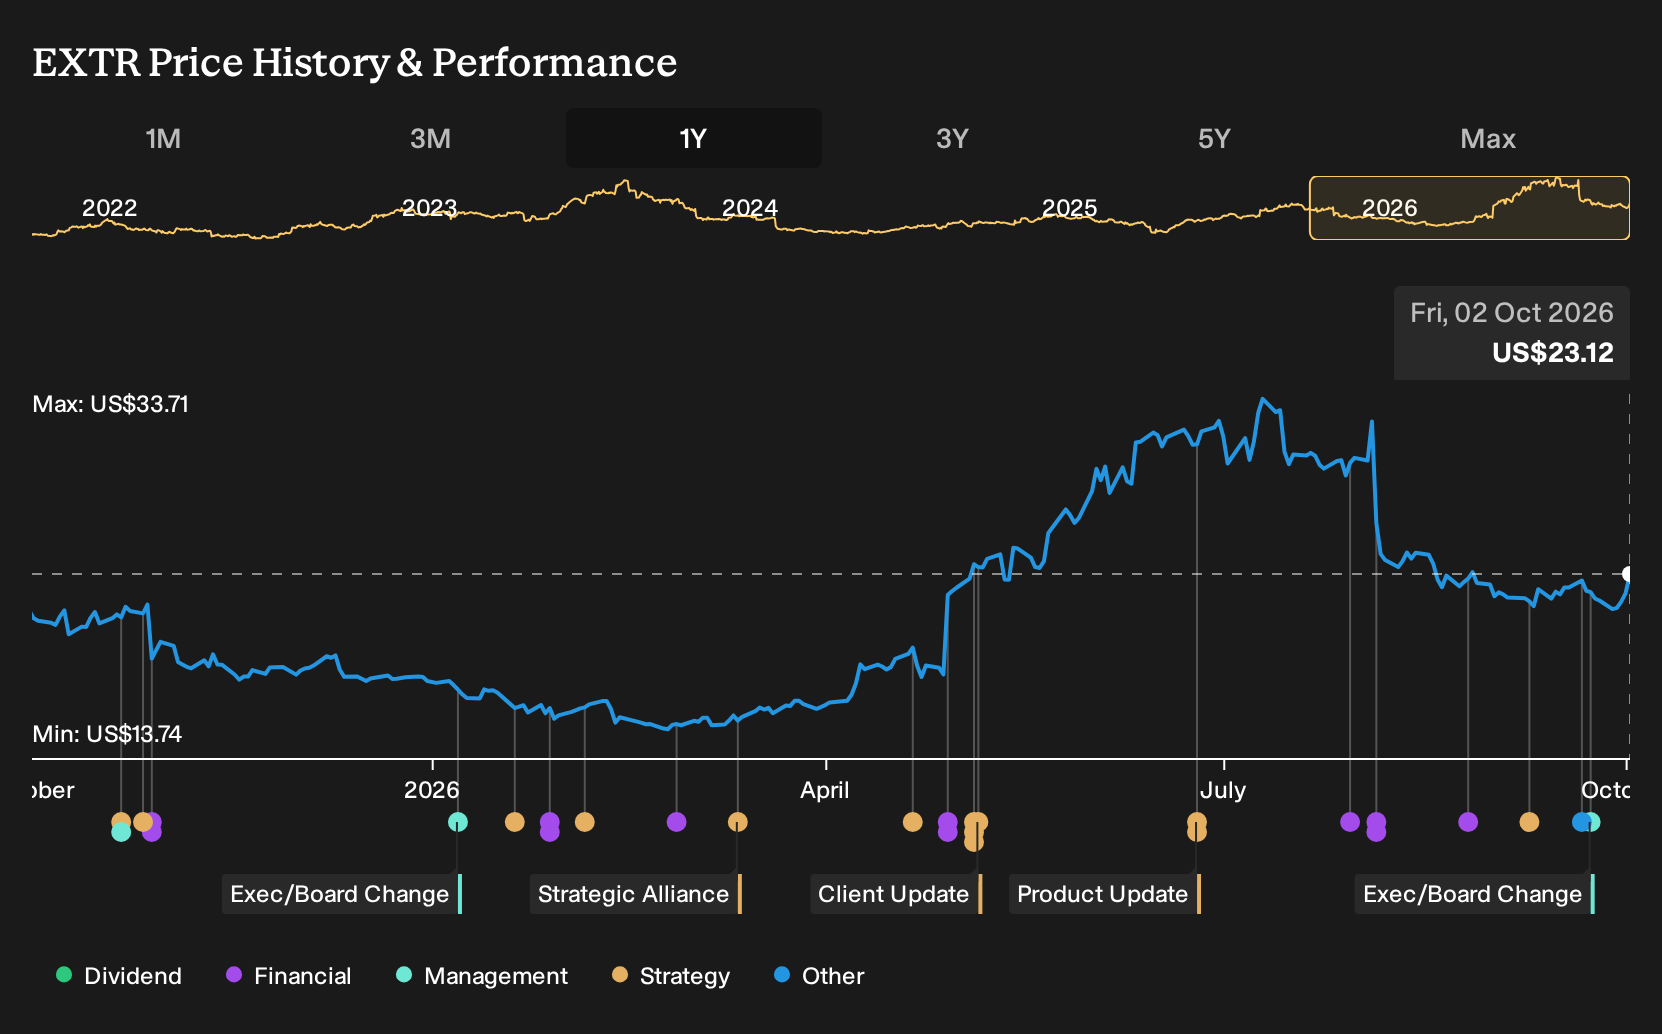
Uncover why Extreme Networks' fair value points to a 45% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view puts more weight on a potential slowdown in Wi Fi 7 refresh projects at Extreme Networks. The most cautious analysts were already baking in 8.8% annual revenue growth and about US$61.2 million of earnings by 2029 before this appointment. You can treat Tambe’s AI focused role as a possible wildcard that may shift those expectations.
Explore 4 other Extreme Networks fair value estimates, including one that suggests as much as 23% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Extreme Networks research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Extreme Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extreme Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Extreme Networks?
Once you have a view on Extreme Networks, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener offers a range of starting points built around quality, balance sheet strength, and income potential.
- For investors who want potential upside without ignoring financial resilience, consider a curated 19 high quality undiscovered gems that combine strong fundamentals with under the radar profiles.
- If capital preservation sits higher on your priority list, focus on a 31 resilient stocks with low risk scores that filters for companies with more resilient financial and risk scores.
- Income oriented readers who prefer to be paid while they wait might screen through a set of 7 dividend fortresses designed to highlight higher yielding payout opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com