
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Stocks Trading At Least 24% Below Fair Value
Bond yields in the US recently hit their highest levels since 2002, which puts pressure on richly priced assets and shifts attention to cash generation and valuation discipline. When borrowing costs bite, investors often look harder at businesses that throw off solid cash and yet trade at a discount to their estimated worth. This article highlights three such stocks from our cash flow value screen that could merit a closer look.
The stocks covered below are just a sample. The full screen surfaces 445 more businesses where current prices sit below their estimated cash flow value and the underlying stories are not captured in this short list. To identify and analyze those additional opportunities directly, head into the Undervalued Stocks Based On Cash Flows screener
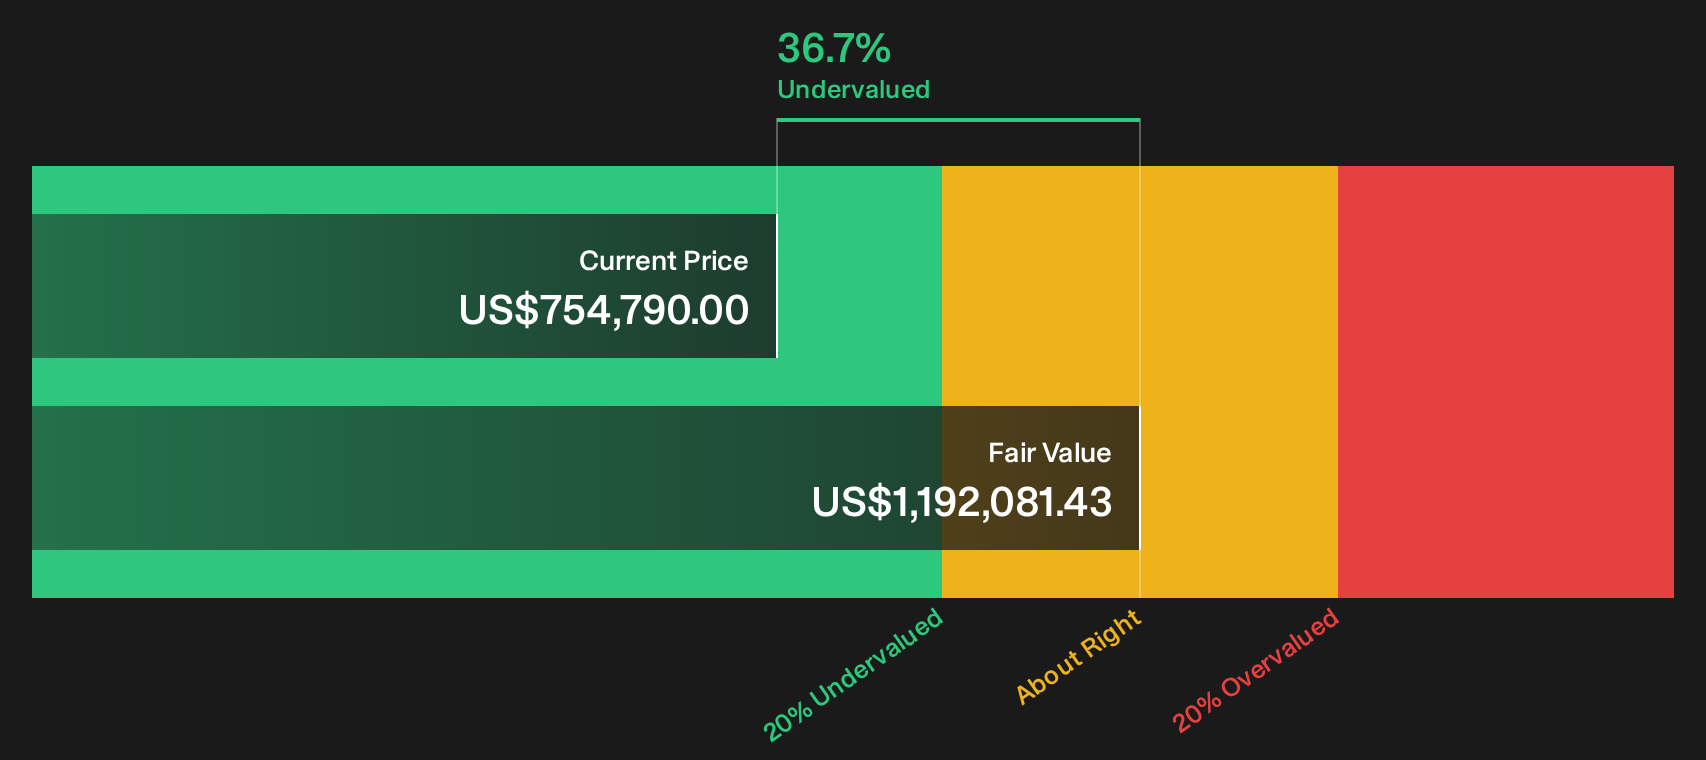
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified holding company that owns insurance, rail, energy, manufacturing, retail, and utility businesses generating substantial cash flows.
Operations: Berkshire Hathaway earns most of its revenue from Manufacturing at US$82.99b, BNSF rail at US$24.64b, and Berkshire Hathaway Energy at US$26.92b.
Market Cap: US$1.07t
Berkshire Hathaway fits this cash flow focused screen through its regulated utility arm Berkshire Hathaway Energy. This segment feeds a long-lived stream of predictable cash into an already cash rich conglomerate.
"The Cash Fortress: Berkshire's cash and short-term Treasuries hit a staggering, record-breaking $397.4 billion."
What happens to Berkshire Hathaway’s valuation as one key pressure on those operating margins and capital deployment choices finally reveals itself?
As that pressure point comes into focus, read the full narrative for Berkshire Hathaway to see how Berkshire Hathaway’s cash pile, optionality and risks could be decoupling from headline valuations.
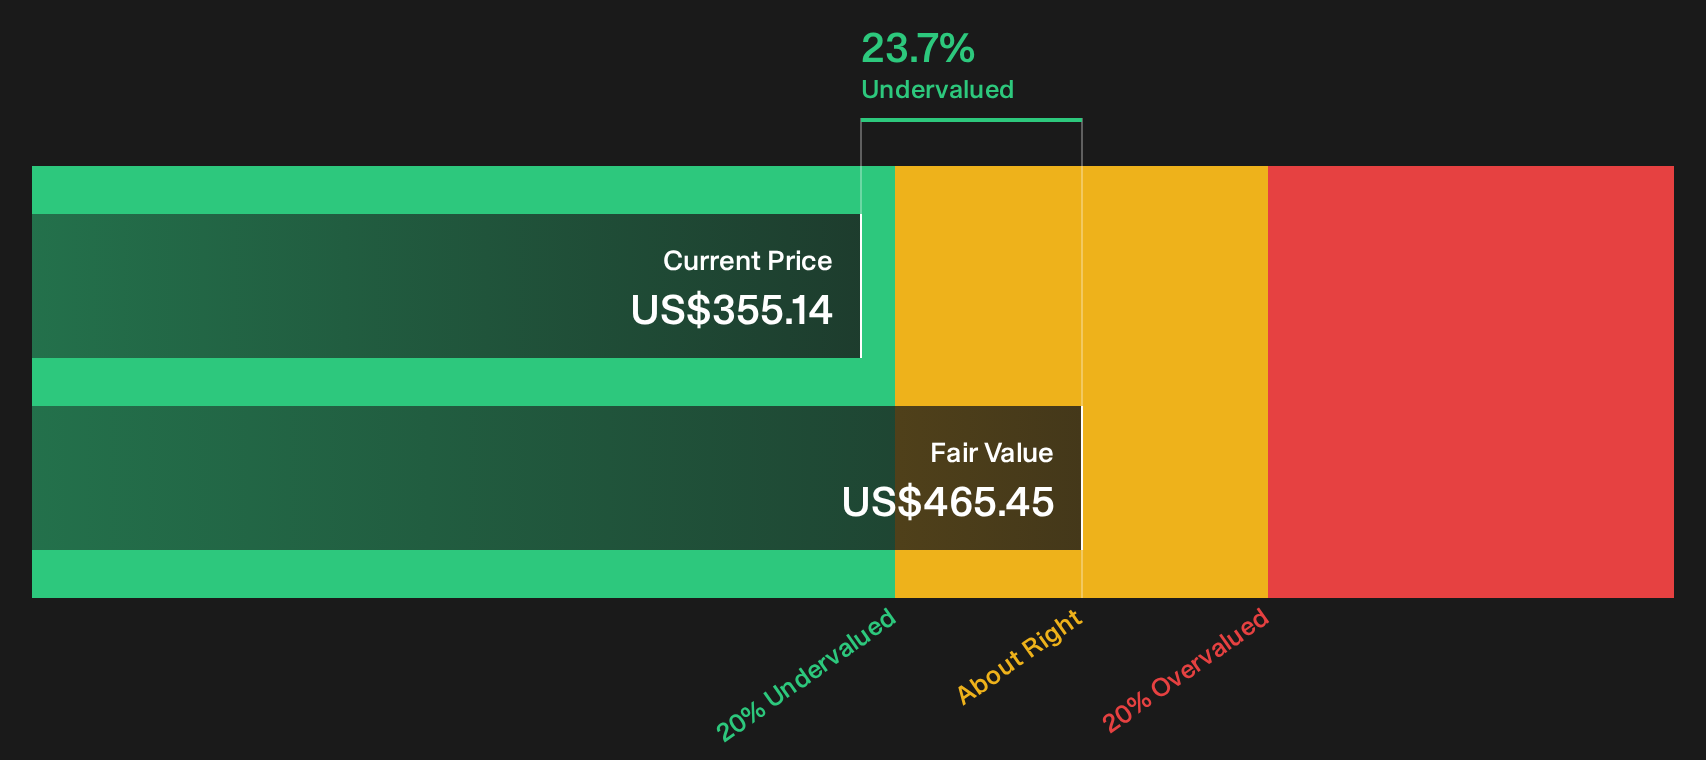
Broadcom (AVGO)
Overview: Broadcom designs semiconductor and infrastructure software products that power data center networking, storage, wireless connectivity, and enterprise computing worldwide.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, giving it two sizeable cash engines.
Market Cap: US$1.64t
Broadcom matters for this cash flow focused screen because its data center networking and storage chips generate substantial recurring cash. In addition, the infrastructure software arm adds another durable source of earnings that supports the valuation signal.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens to Broadcom’s cash rich profile if one fast growing part of that data center demand curve bends in an unexpected direction?
If that demand curve does bend, read the full narrative for Broadcom to see how Broadcom’s cash engines, valuation signal, and risk skew could really line up.
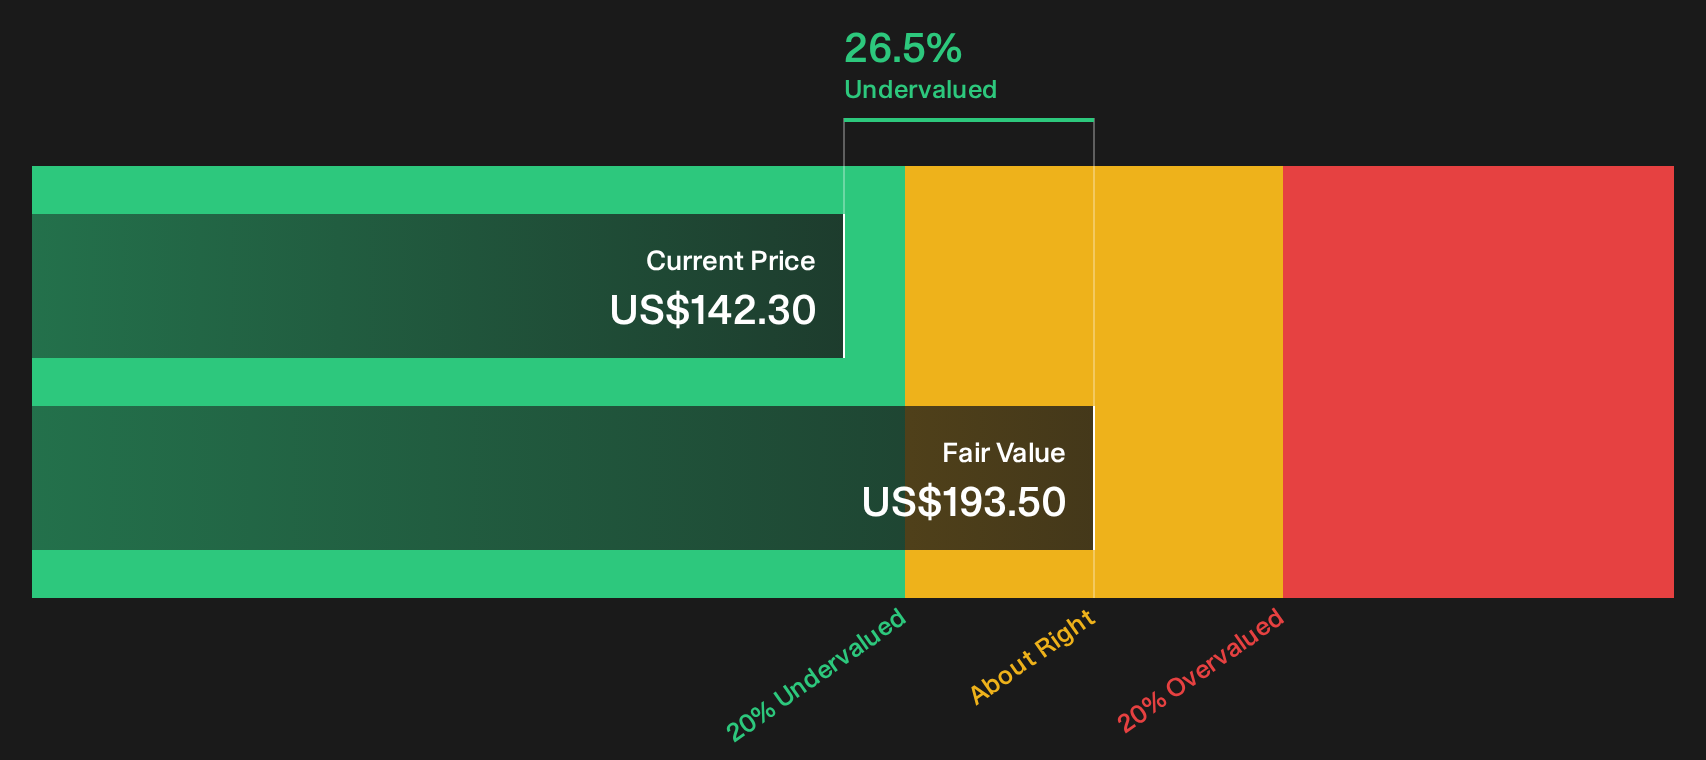
Oracle (ORCL)
Overview: Oracle develops cloud software, databases, and infrastructure that help large organisations run finance, HR, supply chain, and data workloads globally.
Operations: Oracle generates about US$62.8b from cloud and software, US$5.8b from services, and US$3.2b from hardware each year.
Market Cap: US$418.6b
Oracle matters for this undervalued cash flow screen because its cloud and subscription platforms convert recurring customer contracts into substantial free cash generation that is explicitly captured in the DCF work behind the valuation signal.
"The foundation of Oracle’s AI narrative rests on its Gen2 AI infrastructure and the validation it received from the premier generative AI powerhouse, OpenAI."
What happens to that cash flow story if a single unseen pressure on funding those huge AI buildouts starts to bite harder?
If that funding strain is the real swing factor, read the full narrative for Oracle to see how Oracle’s AI push and cash engine could still accelerate.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, early entry points can be gone or dropping fast. Scan these under the radar lists now and look for opportunities to enter earlier in the cycle.
- Focus on resilient payers generating cash and use the 7 dividend fortresses to spot income ideas before yields and prices start moving in opposite directions.
- Look for real AI momentum without funding deep losses by filtering for cash-generating contenders through the 37 profitable AI stocks that aren't just burning cash while they are still attracting limited attention.
- Consider positioning for potential infrastructure demand and let the 40 power grid technology and infrastructure stocks surface possible beneficiaries ahead of any broader focus on power upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com