
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
New ETF Launch Might Change The Case For Investing In IGM Financial Stock (TSX:IGM)
- IGM Financial, through Mackenzie Investments, recently introduced four ETFs managed by its Multi-Asset Strategies Team, blending systematic factor approaches with global exposure and a gold futures overlay on one global equity product.
- The combination of new Modus-branded ETFs and a corporate transformation program that channels savings into AI capabilities signals a push to reshape IGM Financial's product mix and operating model at the same time.
- We will now look at how IGM Financial's investment narrative could be influenced by its AI focused transformation and new ETF range.
IGM Financial Investment Narrative Recap
To own IGM Financial, you need to be comfortable with a wealth manager that still leans heavily on traditional advice channels while trying to rewire its operations with AI and rules based products. The near term story hinges on whether that transformation lifts productivity and supports earnings without relying on aggressive revenue growth assumptions.
The biggest swing factor remains execution. The firm is pushing new Modus ETFs and AI tools into a market that is moving toward low cost passive options and digital platforms. Fee pressure, slower forecast revenue growth and significant recent insider selling all keep the execution risk very real for you as a shareholder.
The launch of four Mackenzie ETFs, including the Global Equity & Gold Overlay ETF, is the clearest operational step that lines up with this catalyst. You are seeing IGM Financial try to broaden its toolkit beyond traditional Canadian mutual funds, use factor rules, and add a gold futures overlay to speak to diversification focused clients.
For investors watching catalysts, these ETFs sit alongside the AI investment program as proof points. Fund uptake, AUM traction and fee levels across this Modus range could either offset fee compression and slower expected revenue growth or leave the group even more exposed if adoption lags and competition in global ETF markets keeps intensifying.
IGM Financial's analyst narrative points to revenue of CA$4.5b and earnings of CA$1.4b by 2029, with revenue described as remaining fairly flat over the next 3 years and earnings rising from CA$1.2b today, which is an increase of about CA$200m from current earnings.
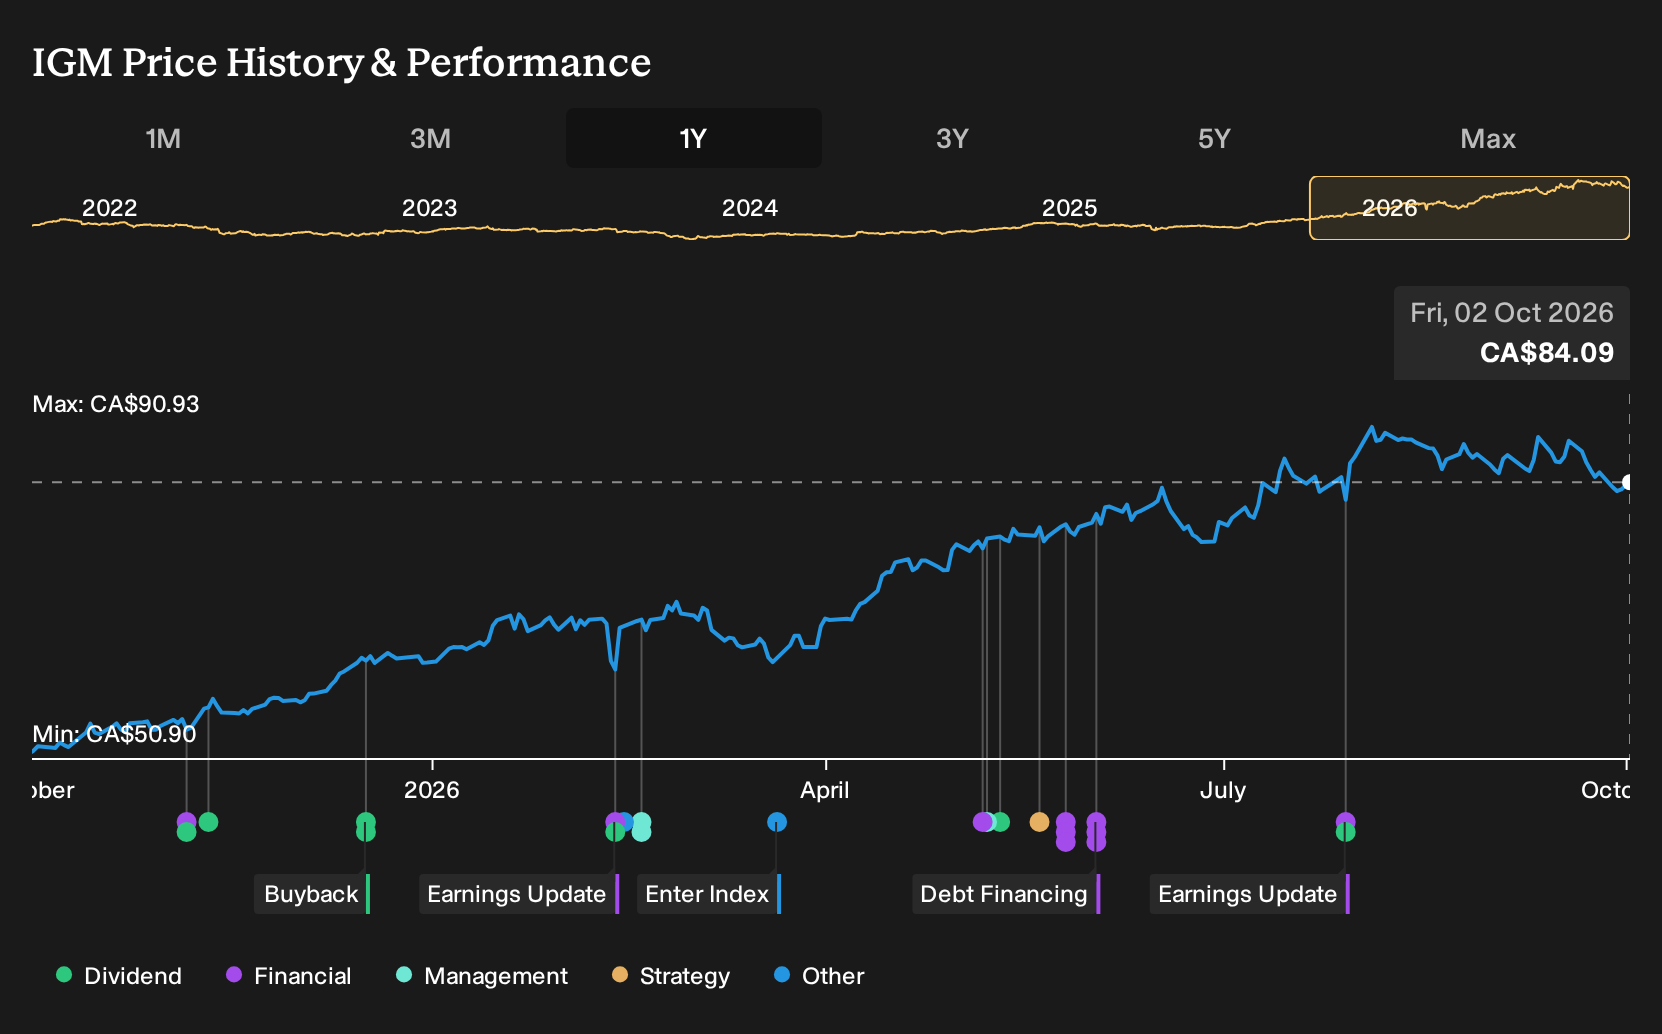
Uncover why IGM Financial's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between about CA$87 and CA$92, so you are not seeing extreme under or overvaluation flags yet. Those pre news estimates also do not factor in IGM Financial's ETF rollout and AI reinvestment, which could influence long term profitability expectations. Consider this a prompt to compare several contrasting Community viewpoints before forming your own stance.
Explore another IGM Financial fair value estimate, including one that suggests up to 10% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your IGM Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IGM Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IGM Financial's overall financial health at a glance.
Looking for more investment ideas beyond IGM Financial?
Once you have formed a view on IGM Financial, it can be useful to compare it with a broader watchlist of potential opportunities that share similar traits or offer a different risk and income profile.
- If you want potential value combined with quality fundamentals, scan through our 6 high quality undervalued stocks that might merit a closer look beside IGM Financial.
- For investors who care most about balance sheet strength and resilience, filter for companies using our list of solid balance sheet and fundamentals (7 results) to see which ones match your risk tolerance.
- If capital preservation comes first for you, start with our 8 resilient stocks with low risk scores and build a shortlist that lines up with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com