
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Bank of New York Mellon Corporation's Payward Talks Mean For Shareholders
- BNY is reported to be in ongoing talks with Kraken parent Payward about a broad digital asset partnership spanning custody, trading, payments, wealth products and market infrastructure through Payward Services.
- The potential tie up would plug a large crypto exchange into Bank of New York Mellon Corporation's institutional plumbing. This could test how well BNY's platform model handles new asset types and more complex client demands.
- We will now see how Bank of New York Mellon Corporation's investment narrative could be influenced by its talks on a Payward crypto partnership.
Scan how this potential Bank of New York Mellon Corporation and Payward link-up compares with other listed plays plugged into digital assets through our hand picked 18 cryptocurrency and blockchain stocks.
Bank of New York Mellon Investment Narrative Recap
To own Bank of New York Mellon Corporation, you need to be comfortable with a fee heavy model tied to custody, asset servicing and related activities, and with earnings that rely on cost discipline and operating leverage as much as on top line growth. The talks with Payward sit on top of this story rather than redefine it, unless they eventually lead to materially different client behavior or product mix.
In the near term, the key swing factor remains whether BNY can keep expense growth below revenue so that operating leverage and current pretax margins hold up. The main risk is renewed pricing or flow pressure in Investment Management that softens fee income while costs tied to digital platforms, including any future crypto build out, keep running.
The most relevant reference point for the Payward discussions is BNY's existing digital asset work with Circle, where USDC sits on the Digital Asset Custody platform and the group participates in the Open USD initiative with shared reserve yield economics. That project shows BNY is already wiring digital assets into its core infrastructure rather than treating them as a side bet.
If a Payward arrangement goes ahead, investors can weigh it against this Circle experience when thinking about execution risk, operational complexity and potential fee channels. The thread that links them is simple: Bank of New York Mellon Corporation keeps testing whether its AI backed, platform style model can support new asset types while still delivering operating leverage, stable margins and high quality earnings.
Bank of New York Mellon's narrative projects US$24.4b revenue and US$7.3b earnings by 2029. This is based on analysts assuming 4.5% yearly revenue growth and an earnings increase of about US$1.3b from US$6.0b today.
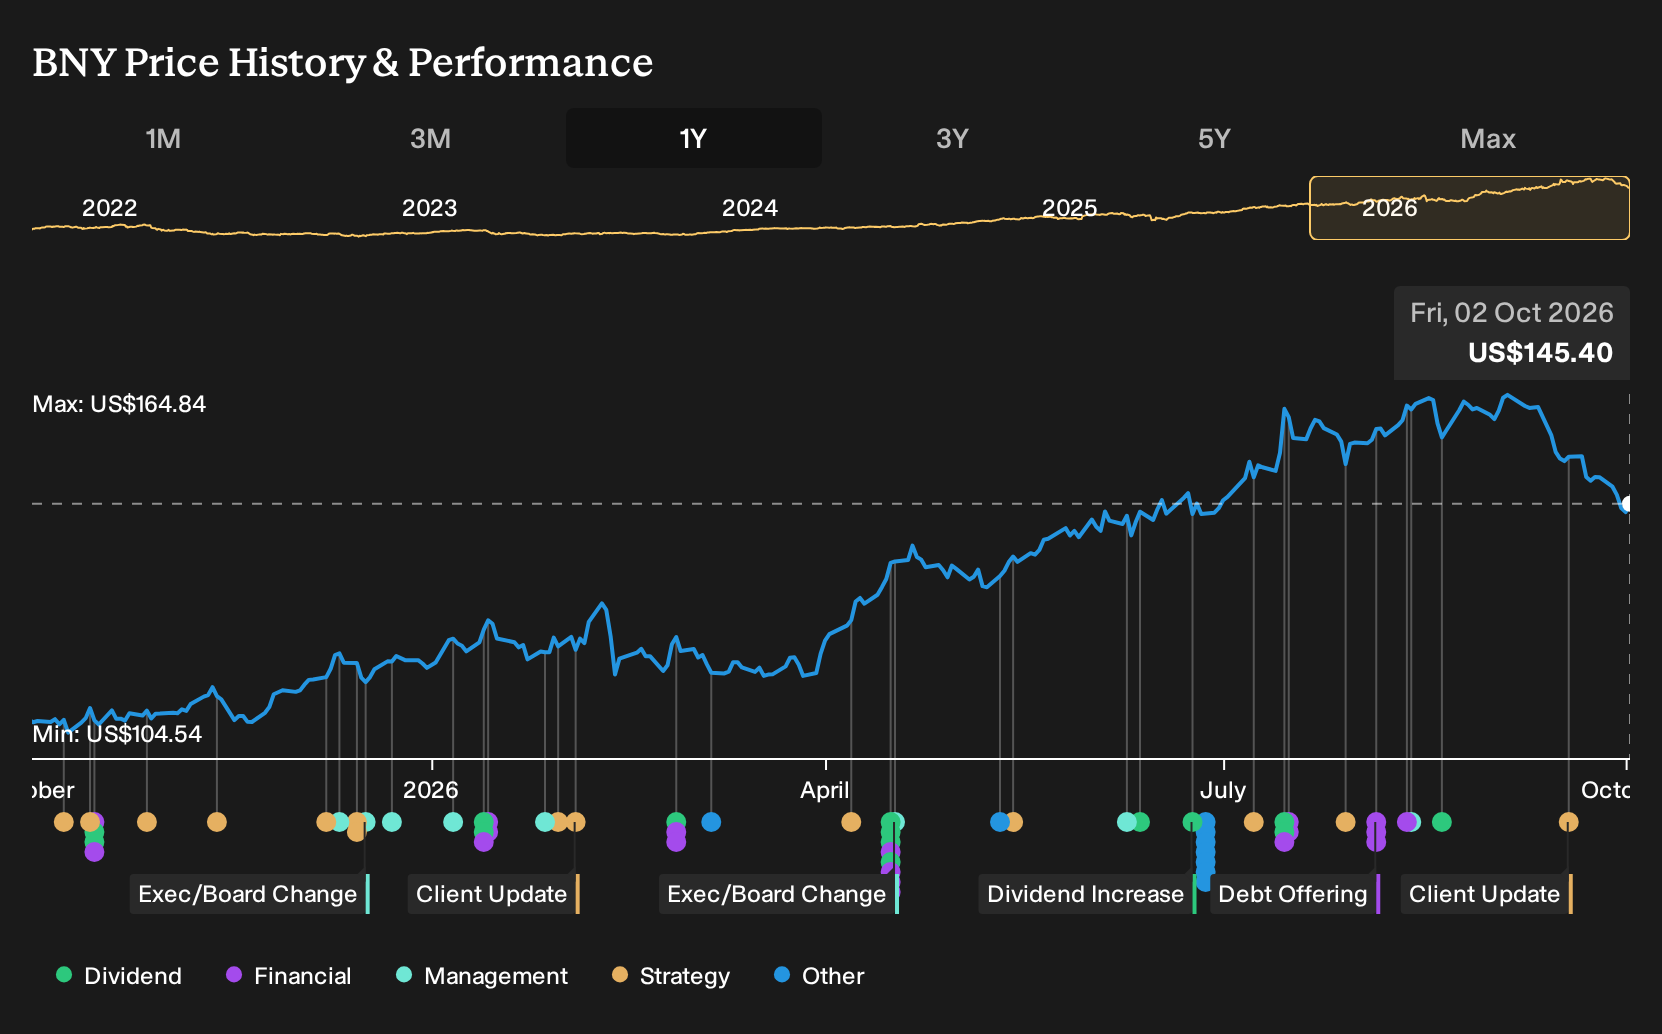
Uncover how Bank of New York Mellon's fair value indicates a 15% potential upside to its current price, which could narrow quickly as sentiment around BNY shifts.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between about US$146 and US$168, so even this small sample shows private investors can land in very different places on Bank of New York Mellon Corporation. When you add in the crypto partnership talks and shifting fee expectations, you have plenty of reasons to compare multiple views.
Explore another Bank of New York Mellon fair value estimate, including one that suggests it could be worth just $146.41.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of New York Mellon research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of New York Mellon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of New York Mellon Corporation's overall financial health at a glance.
Looking for more investment ideas beyond Bank of New York Mellon Corporation?
Once you have a view on Bank of New York Mellon Corporation, it can help to widen the lens and compare it with other listed opportunities that fit different risk and income profiles.
- If you want potential mispricings with solid fundamentals, scan our curated set of 31 high quality undervalued stocks that may be trading below what their cash flows and balance sheets suggest.
- For investors who care most about resilience, check out a 31 resilient stocks with low risk scores that screens for businesses with steadier risk scores and fewer financial red flags.
- Those hunting for income ideas can review a collection of 7 dividend fortresses that pair 5%+ yields with a focus on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com