
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Protagonist Therapeutics (PTGX) Could Be 25% Undervalued On Its Royalty Backed Story
Protagonist Therapeutics (PTGX) moved slightly higher at the latest close, with the share price at US$140.06. This has drawn attention to how investors are weighing its clinical pipeline, recent returns, and current valuation profile.
Recent trading tells a mixed story for Protagonist Therapeutics. In the short term, the shares have eased, with a 7 day share price return of 1.27% lower and a 30 day share price return of 4.12% lower. However, the year to date share price return of 60.66% and a 1 year total shareholder return of 116.04% show momentum that has already been very strong.
Scan Protagonist Therapeutics alongside other fast moving biotech opportunities by reviewing the hand picked 19 high quality undiscovered gems that share strong fundamentals and significant recent share price momentum.
After such a steep 1 year run for Protagonist Therapeutics, the key tension is clear. Are investors already pricing in most of the good news, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 20% Undervalued
Against the last close of $140.06, the most followed narrative anchors Protagonist Therapeutics to a fair value of $174.69. This frames the recent share price surge against a longer term royalty and pipeline story that is still being priced in.
The transition to a royalty and milestone funded model, with around US$850 million in cash and no anticipated equity based financings in the foreseeable future, gives Protagonist Therapeutics room to advance its pipeline and run a US$300 million share repurchase program, which can influence per share earnings metrics even if total profit is unchanged.
See why 2 investors see Protagonist Therapeutics as 20% undervalued.
Result: Fair Value of $174.69 (UNDERVALUED)
Still, the Protagonist Therapeutics story can unravel quickly if ICOTYDE or MIMRYLO royalties miss analyst assumptions or if the rich P/E multiple compresses sharply.
Find out about the key risks to this Protagonist Therapeutics narrative.
Another View On Protagonist Therapeutics Valuation
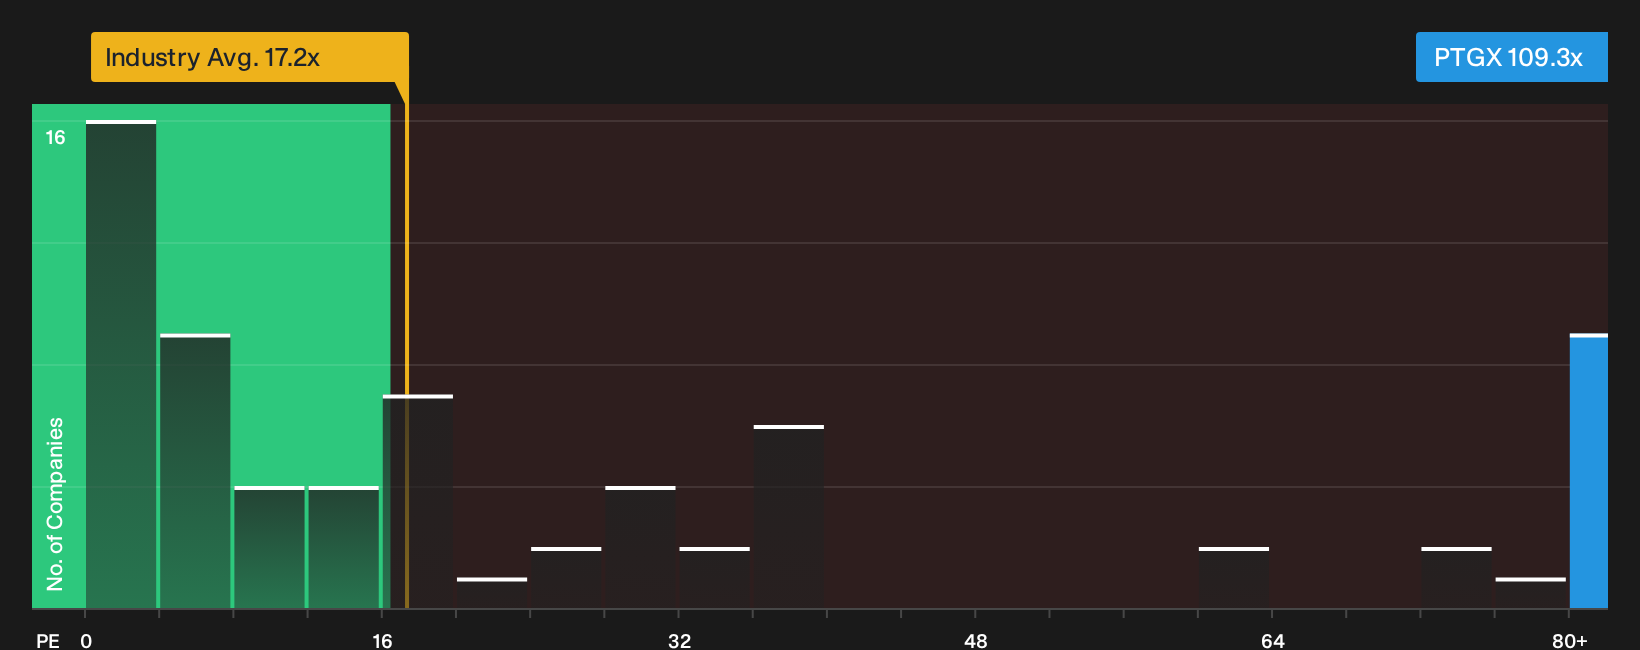
The first story around Protagonist Therapeutics leans on future royalties and analyst targets pointing to a fair value of $174.69. A simple P/E lens tells a very different story, with the stock at 109.3x earnings versus a fair ratio of 28.9x.
That multiple also sits well above the US Biotechs industry on 17.1x and a peer group on 66.3x. If sentiment cools and the ratio drifts closer to the fair ratio over time, how comfortable are you holding a stock where valuation compression alone could dominate the return profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Protagonist Therapeutics is split, which is exactly why checking the underlying rewards and risks yourself can be so helpful. If you want to see what is driving the optimism in detail, start with the 4 key rewards.
Looking for more investment ideas beyond Protagonist Therapeutics?
If Protagonist Therapeutics has sharpened your thinking, use that momentum to scan other opportunities before they move out of reach and leave you playing catch up.
- Target potential mispricings by checking companies on the 31 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying strength.
- Prioritize income and stability by reviewing the 7 dividend fortresses that focus on higher yield payouts supported by dependable financial profiles.
- Cut down portfolio stress by filtering for the 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com