
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pipeline Expansion Go Ahead Might Change The Case For Investing In TC Energy (TSX:TRP)
- TC Energy has confirmed that Coastal GasLink Phase 2 will proceed after LNG Canada’s expansion FID, with upgrades planned to nearly double the pipeline’s approximately 2.1 Bcf/d capacity using new compressor stations and facility improvements along the existing 670 kilometre route.
- The decision links TC Energy’s long haul gas network more tightly to LNG Canada’s export build out, concentrating future returns on efficient brownfield capacity increases rather than new greenfield pipe and highlighting execution, capital allocation, and long duration demand risk as key issues for investors.
- We will now assess how TC Energy's investment narrative could shift as Coastal GasLink Phase 2 advances without adding new pipeline mileage.
Scan how TC Energy’s pipeline expansion story compares with other gas and infrastructure plays by reviewing our hand picked 40 power grid technology and infrastructure stocks across the energy transport value chain.
TC Energy Investment Narrative Recap
To own TC Energy, you need to be comfortable with a business that leans on long lived gas pipes, regulated returns and steady, contracted cash flows, while carrying meaningful debt and a dividend that is not fully covered by earnings or free cash flow. The Coastal GasLink Phase 2 go ahead tightens the link to LNG Canada but does not change those fundamentals overnight.
The key near term swing factor is still execution and cost control on major projects, alongside progress on deleveraging, given interest costs are not well covered. Coastal GasLink Phase 2 adds another large build where delays or overruns could pressure margins further, so project delivery and balance sheet repair remain the main risk pair to watch.
The sale of the Guadalajara Manzanillo pipeline in Mexico for about US$560 million is the announcement that fits this moment best. It speaks directly to TC Energy’s portfolio reshaping as the group commits fresh capital into Coastal GasLink Phase 2 and other North American gas projects tied to LNG and power demand.
For you as a shareholder, that pipeline divestment feeds into the same catalyst that now matters more after the Coastal GasLink decision. Execution on asset sales and recycling proceeds into brownfield style expansions gives management more room to address leverage and interest coverage, while concentrating operational focus on systems where utilization and contracts are most central to the story.
TC Energy's current analyst narrative points to CA$18.2b in revenue and CA$5.3b in earnings by 2029, anchored to an assumed 5.2% yearly revenue growth rate and an earnings increase of about CA$1.6b from CA$3.7b today.
Discover why TC Energy's fair value indicates a 17% potential upside to its current price that may not last much longer.
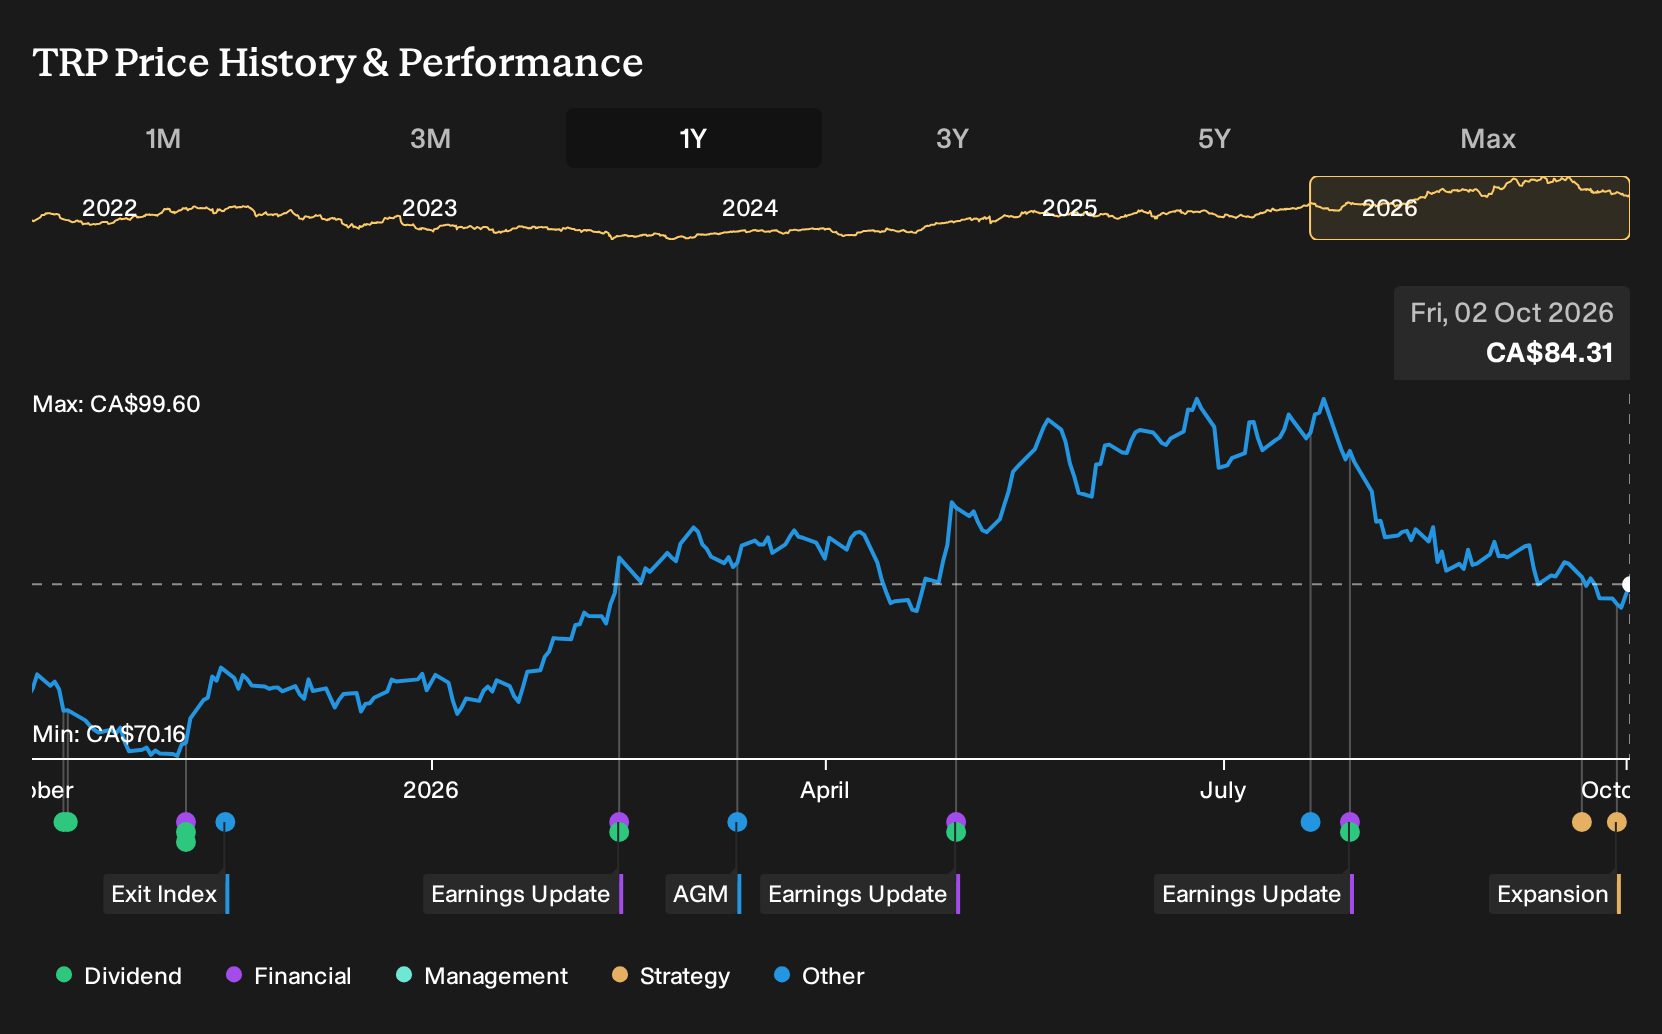
Exploring Other Perspectives
The Simply Wall St Community only has two fair value models for TC Energy, yet they stretch from about 33.86 to 98.78. That spread shows how far private investors can diverge. If you then consider the Coastal GasLink Phase 2 build and ongoing asset sales, you can see real execution risk. You should test several views, not just one.
Explore another TC Energy fair value estimate, including one that suggests as much as 60% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TC Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TC Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TC Energy's overall financial health at a glance.
Looking for more investment ideas beyond TC Energy?
Once you have a view on TC Energy, it can help to cross check that thesis against other listed businesses with different balance sheets, payout profiles and risk levels. The Simply Wall St Screener gives you a quick way to spot companies that match the kind of financial traits you care about most.
- If capital preservation is your first filter, start by reviewing a group of companies that score well on resilience and financial risk through the 8 resilient stocks with low risk scores.
- If reliable income streams matter more to you, scan for payout heavy stocks that aim for robust distributions with the 1 dividend fortresses.
- If you prefer to hunt for under followed opportunities, widen your watchlist with a 9 high quality undiscovered gems that pair solid fundamentals with lower investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com