
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Western Digital (WDC) Below Fair Value Following Its AI Storage Push?
Western Digital (WDC) just put its WD Red Pro hard drives in the spotlight during a special call on how these HDDs support AI powered NAS systems facing heavier data loads and tougher reliability demands.
Western Digital has seen sharp swings recently, with the share price falling 10.22% in the last session and declining 22.95% over 90 days, yet still posting a 121.25% year to date share price return and a very large 3 year total shareholder return of 10.9x. This suggests that long term momentum remains strong even as shorter term sentiment cools around AI infrastructure demand and storage hardware risk.
Look beyond Western Digital and consider other potential AI infrastructure beneficiaries using the hand picked 90 AI infrastructure stocks in the same data hungry theme.
Western Digital has swung hard in both directions, yet sits far below many valuation models and analyst targets. Is the recent pullback enough to bring the share price back toward a fair value range, or is it still not close?
Most Popular Western Digital Narrative: 26% Overvalued
According to the most widely followed narrative on Western Digital, the fair value sits at $329.76 compared with the last close at $415.29, which puts current pricing above that reference point while still leaning heavily on the AI storage story.
Here is the tension. That golden hour is priced as if it lasts. And the single most repeated line in technology investing is Jeff Bezos's warning, "your margin is my opportunity." Record margins are not just the reward in this business, they are the invitation. Every point of margin above the long-run average is a signal to someone, somewhere, to add supply, requalify a competitor, or accelerate a substitute.
See why 37 investors see Western Digital as 26% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital's story can break if AI capex cools faster than expected, or if new HDD capacity and cheaper flash squeeze those rich margins.
Find out about the key risks to this Western Digital narrative.
Another Take On Western Digital’s Value
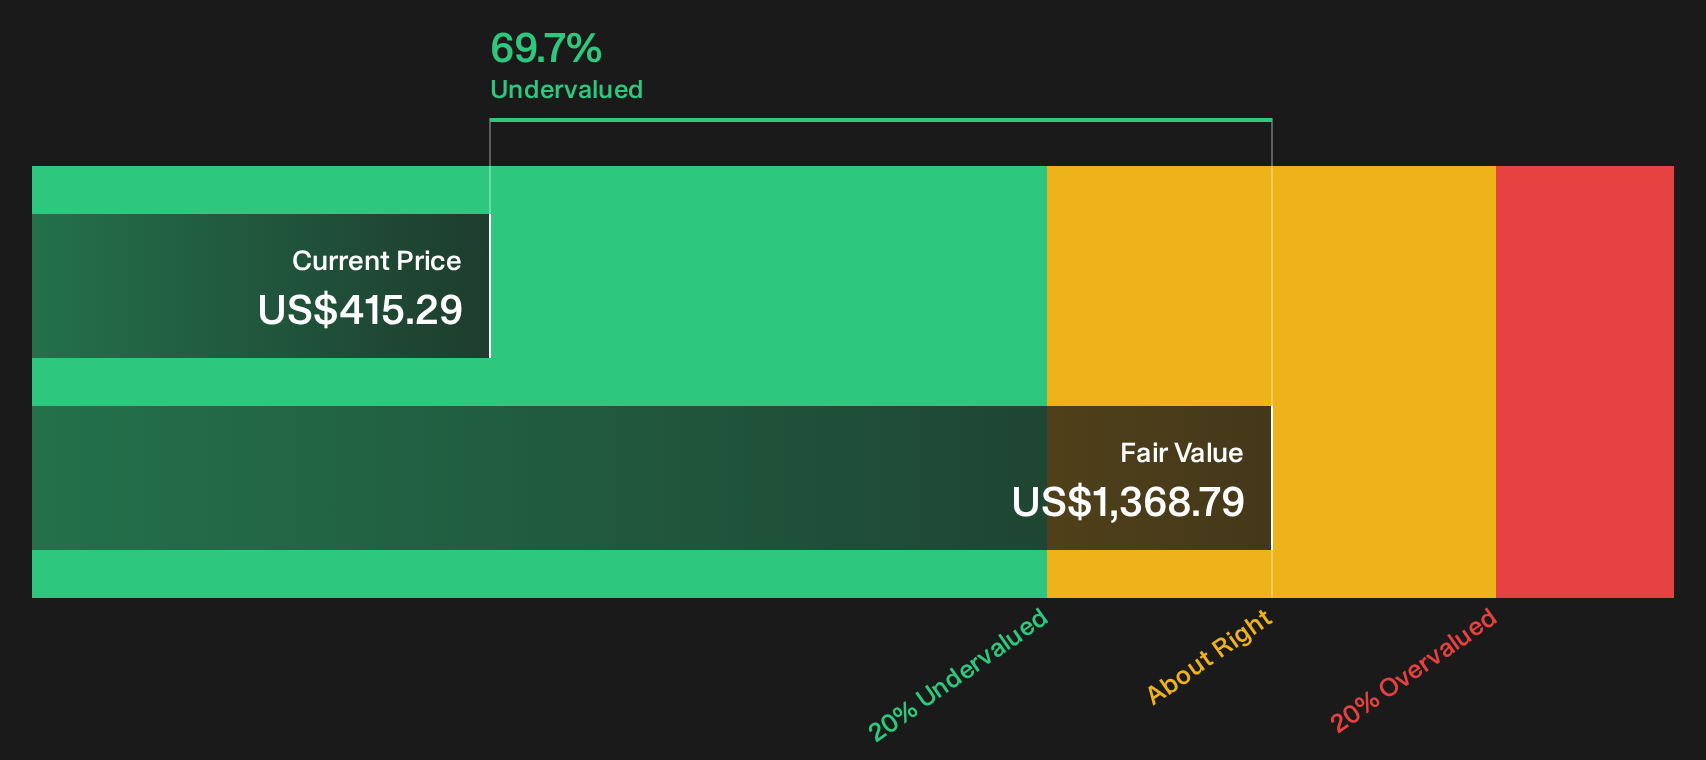
The popular Western Digital narrative pins fair value at $329.76 and calls the stock overvalued, yet our DCF model suggests a different view. On that basis, WDC at $415.29 trades well below an estimated future cash flow value of $1,368.79, which frames the current price as heavily discounted. Which story do you lean toward when the cash flow math disagrees with the crowd?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Western Digital's value and AI upside can feel confusing. Move quickly, review the full data set, and weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Western Digital?
You have seen how conflicting narratives around Western Digital can shape decisions. Do not stop here. Broaden your watchlist using focused idea lists built from the Simply Wall Street Screener.
- Target steady compounding by reviewing resilient companies on the 31 resilient stocks with low risk scores that score well on risk metrics and may cushion sharper drawdowns.
- Hunt for quality at a discount through the 19 high quality undiscovered gems and spot strong fundamentals that the broader market might still be ignoring.
- Prioritize strength in downturns by scanning the list of solid balance sheet and fundamentals (26 results) where healthier finances can support dividends, reinvestment, and flexibility when conditions tighten.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com