
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Valle Ancho Spin Out Will Impact NGEx Minerals Stock Investors
- NGEx Minerals has already filed materials for a special shareholder meeting to approve spinning out its Valle Ancho Project into a separate company, Valiente Resources Inc., with Valiente expected to hold that asset and seek a TSX Venture Exchange listing subject to regulatory approval.
- This carve out of Valle Ancho could reshape how investors assess NGEx Minerals' core exploration focus in comparison with the prospective value of a standalone Valiente equity exposure.
- We will look at how NGEx Minerals' investment narrative is affected by the proposed Valle Ancho spin out into Valiente Resources.
Compare NGEx Minerals' spin out story with other specialist miners by scanning a hand picked group of 16 top copper producer stocks that are shaping the next phase of resource development.
NGEx Minerals Investment Narrative Recap
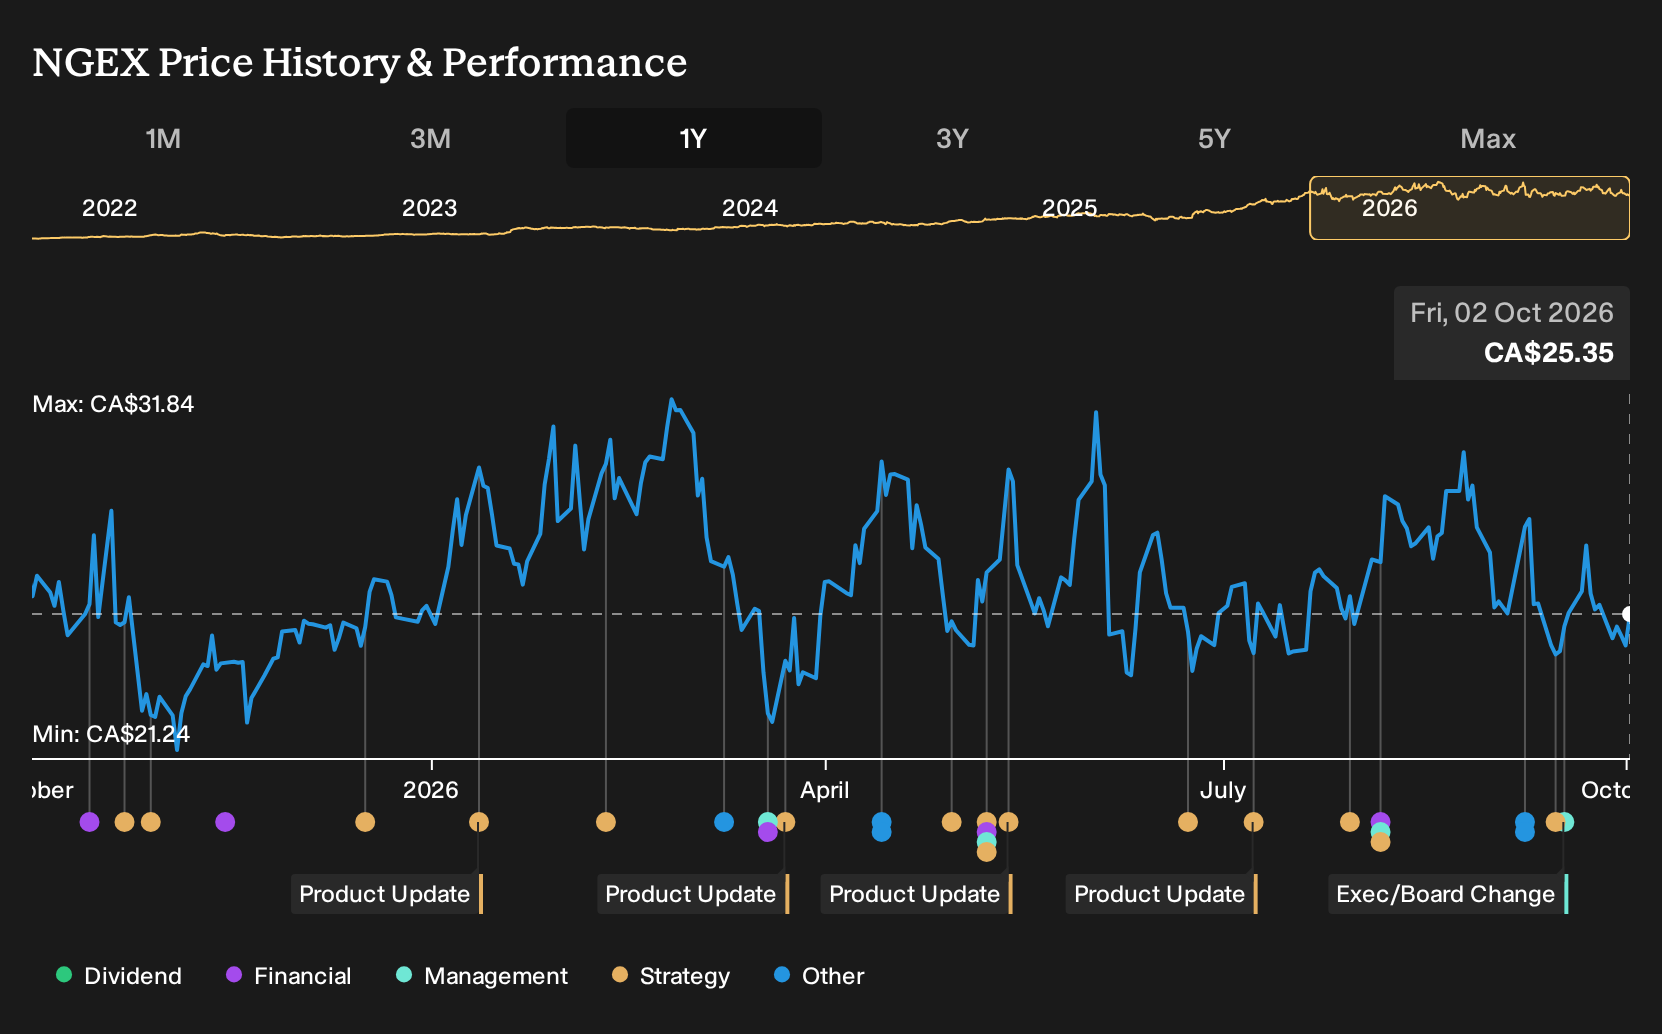
To own NGEx Minerals, you need to believe its South American copper and gold assets can ultimately move from exploration into viable long life operations, despite the current lack of revenue and ongoing losses. The Valle Ancho spin out does not change that core belief. The key near term swing factor still sits with how efficiently Lunahuasi and Los Helados programs convert drilling, testwork and early development into clearer project definition.
On the risk side, the widened losses, heavy exploration spend and rich P/B multiple leave little room for setbacks in timing or project quality without a sharp sentiment reset. The Valle Ancho transaction may simplify the story, but it does not reduce exposure to exploration, permitting and geopolitical uncertainty in Argentina and Chile, or the possibility of future funding needs that dilute existing holders.
The spin out filing for Valiente Resources is the most relevant recent step. It formalises the plan to put Valle Ancho into a separate vehicle and give existing NGEx Minerals shareholders direct exposure to that asset through Valiente shares, subject to approvals and listing. For catalysts, focus stays on how cleanly this separation is executed and whether it clarifies capital allocation toward Lunahuasi and Los Helados.
That corporate move sits alongside earlier catalysts such as the funded drill programs, the underground adit plan and metallurgical work at Lunahuasi. Together, these pieces shape how quickly NGEx Minerals can tighten its technical story while managing cash burn and construction risk. If execution on drilling, testwork and project access falls behind expectations, the benefits of the Valle Ancho spin out could be overshadowed by concern about schedule slippage and extended losses.
NGEx Minerals' narrative projects forecast revenue of CA$510.5 million and forecast earnings of CA$160.4 million by 2029. This implies a move from no sales today to CA$510.5 million in forecast revenue, and an earnings increase of about CA$291.3 million from a current loss of CA$130.9 million to expected earnings of CA$160.4 million.
Uncover why NGEx Minerals' fair value indicates a 41% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster between CA$35.78 and CA$62.22 per share, showing a wide band of opinion on NGEx Minerals. Those figures were all set before the Valle Ancho spin out plan and recent funding progress, so reassess them in light of fresh drilling, project risks, and new capital structure paths.
Explore 3 other NGEx Minerals fair value estimates, including one that suggests the potential for as much as 145% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NGEx Minerals research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NGEx Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NGEx Minerals' overall financial health at a glance.
Looking for more NGEx Minerals style investment ideas?
If the NGEx Minerals story has you thinking about where else the numbers and narrative might line up in your favour, put that curiosity to work with a few focused screens on Simply Wall St.
- For investors who want strong fundamentals and meaningful upside potential, scan a curated group of 6 high quality undervalued stocks that pair quality with appealing valuations.
- If capital preservation and a smoother ride matter to you, filter for 8 resilient stocks with low risk scores that score well on resilience and risk controls.
- When you want to widen your opportunity set beyond widely followed stocks, hunt through 9 high quality undiscovered gems that combine solid business profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com