
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pebblebrook Hotel Trust (PEB) Dividend And Board Move Put Valuation Back In Focus
Pebblebrook Hotel Trust (PEB) has drawn fresh attention after announcing a cash dividend of $0.398 per share and appointing veteran real estate executive Bill Bayless to its Board of Trustees.
Recent trading suggests the latest dividend declaration and Bill Bayless joining the board are feeding into a sense of renewed momentum around Pebblebrook Hotel Trust. The shares have delivered a 7 day share price return of 3.53% and a year to date share price return of 65.11% at a recent price of $19.07. The 1 year total shareholder return of 72.89% and 3 year total shareholder return of 45.56% point to meaningful gains for investors who stayed invested over the longer stretch, despite a 5 year total shareholder return that declined 15.17%.
Scan other hotel and real estate focused REITs showing similar momentum and income appeal by reviewing our curated list of 31 high quality undervalued stocks.
Bulls see Pebblebrook Hotel Trust’s sharp share price run, fresh dividend and new board appointment as validation. Bears focus on the recent net loss and mixed multi year returns. Which side does the current valuation support next?
Most Popular Narrative: 4% Overvalued
The most followed narrative pegs Pebblebrook Hotel Trust’s fair value at about $18.42, which sits a little below the recent $19.07 share price and frames today's jumpy trading against longer term expectations built on urban hotel demand, margin work and upcoming city events.
The portfolio is set to benefit from a loaded pipeline of major citywide events, convention calendars, and sports/entertainment spectacles (World Cup, Super Bowl, Olympics) in 2026 to 2028, which are expected to significantly boost occupancy, push ADR higher, and drive revenue growth in core urban markets.
See why 1 investors see Pebblebrook Hotel Trust as 4% overvalued.
Result: Fair Value of $18.42 (OVERVALUED)
Still, Pebblebrook Hotel Trust’s focus on high cost urban markets and recent net loss of US$78.6 million leave the bullish fair value story exposed.
Find out about the key risks to this Pebblebrook Hotel Trust narrative.
Another View on Pebblebrook Hotel Trust’s Value
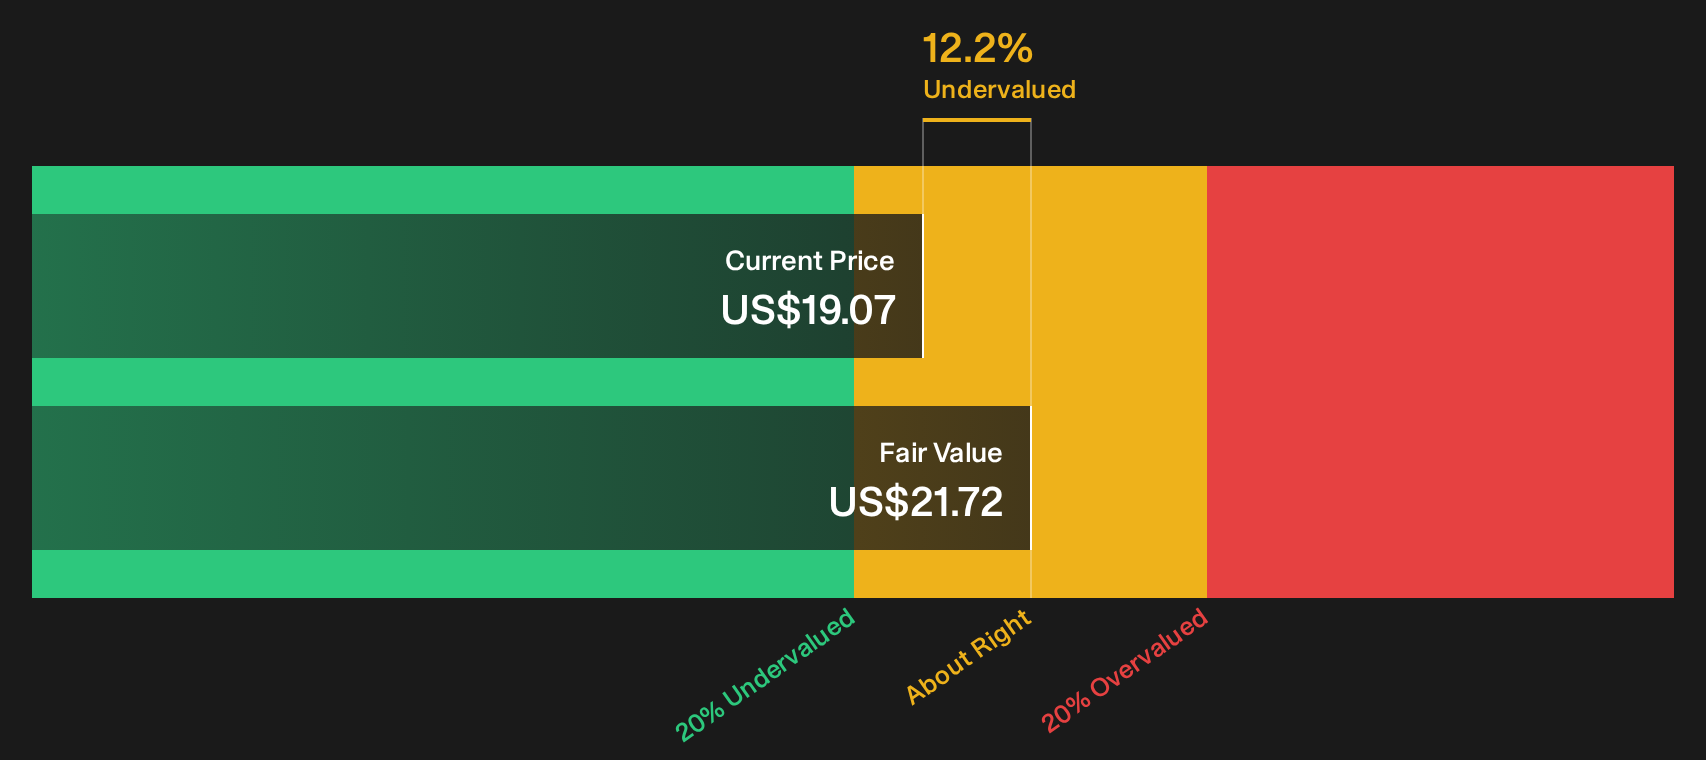
The first narrative tagged Pebblebrook Hotel Trust as about 4% overvalued around $19.07, based on analyst fair value of $18.42. A different lens tells a very different story. Our DCF model points to a future cash flow value of $21.72, which places the current quote roughly 12.2% below that estimate.
That split between analyst targets and the SWS DCF model leaves investors with a simple puzzle. Which set of assumptions feels closer to how Pebblebrook Hotel Trust will actually perform over time, and which one would you lean on when the price starts to move?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Pebblebrook Hotel Trust’s value narrative can create pressure, so move quickly and review the data directly to shape your own stance with 3 key rewards and 1 important warning sign.
Looking for more Pebblebrook Hotel Trust sized ideas?
If Pebblebrook Hotel Trust has you reassessing your watchlist, do not stop here. Cast the net wider so you are not the investor who looks back wishing you had checked the rest of the field when the next winners were already lining up.
- Target higher income potential by scanning companies that feature 7 dividend fortresses and see which payouts align with your return goals.
- Prioritize resilience and sleep easier at night by reviewing a 31 resilient stocks with low risk scores that screens for businesses with steadier risk profiles.
- Hunt for future leaders before they are crowded trades by checking a 19 high quality undiscovered gems that highlights quality stories still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com