
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Great Canadian Dividend Stocks To Own In October 2026
Global bond markets have just steadied after a sharp sell off that pushed borrowing costs to levels not seen since the early 2000s. Higher yields make reliable income harder to find and more valuable when you get it. That is where a group of Canadian companies with dividend yields above 3% and records of well covered payouts comes in. This article highlights three of the strongest options from that list.
The three stocks in this article are just a first pass, and the full screen surfaced 17 more dividend payers with similarly compelling stories that are not covered below. To see the broader field, head straight into the Dividend Powerhouses (3%+ Yield) screener to identify, analyze, and focus on the dividend ideas that fit your income goals.
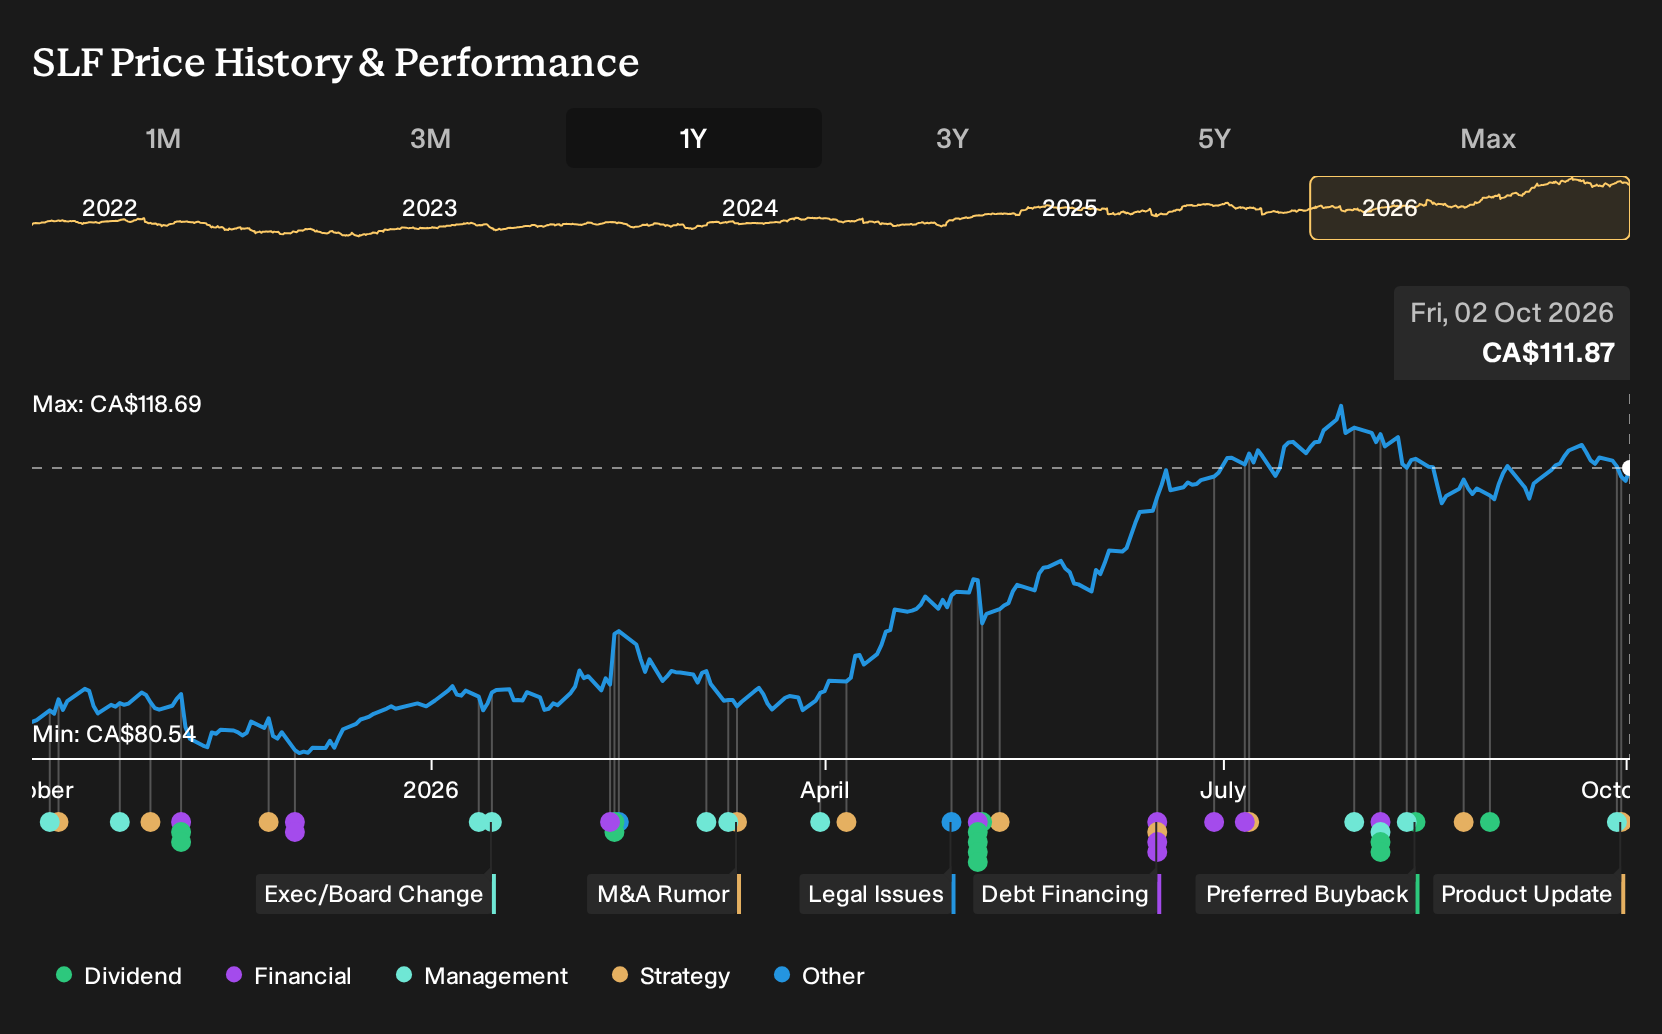
Sun Life Financial (TSX:SLF)
Sun Life Financial is a long running insurer and asset manager that ties into the Dividend Powerhouses theme through dividend paying common shares backed by recurring cash flows across Canadian and international insurance, wealth, and asset management operations.
Sun Life Financial generates about C$15.7b of revenue from Canada, C$12.9b from the U.S., C$7.7b from Sun Life Asset Management and C$2.6b from Asia, with corporate and consolidation effects bringing group totals together. The company’s market cap is roughly C$61.5b.
For dividend investors, Sun Life Financial matters because this mix of insurance premiums and fee income can support a well covered, growing payout when those cash flows stay consistent.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources; this is reinforced by double-digit sales and CSM growth in the region year-over-year."
What could really move the dial from here is how one emerging pressure on profitability shapes the next leg of that income story.
As that profitability pressure builds, read the full narrative for Sun Life Financial to see how Sun Life Financial’s cash engines, capital levers and dividend ambitions really fit together.
Magna International (TSX:MG)
Magna International gives this dividend screen exposure to a large auto supplier whose steady contracts and high-volume programs help support a 3%+ yield backed by recurring cash flows rather than one-off wins.
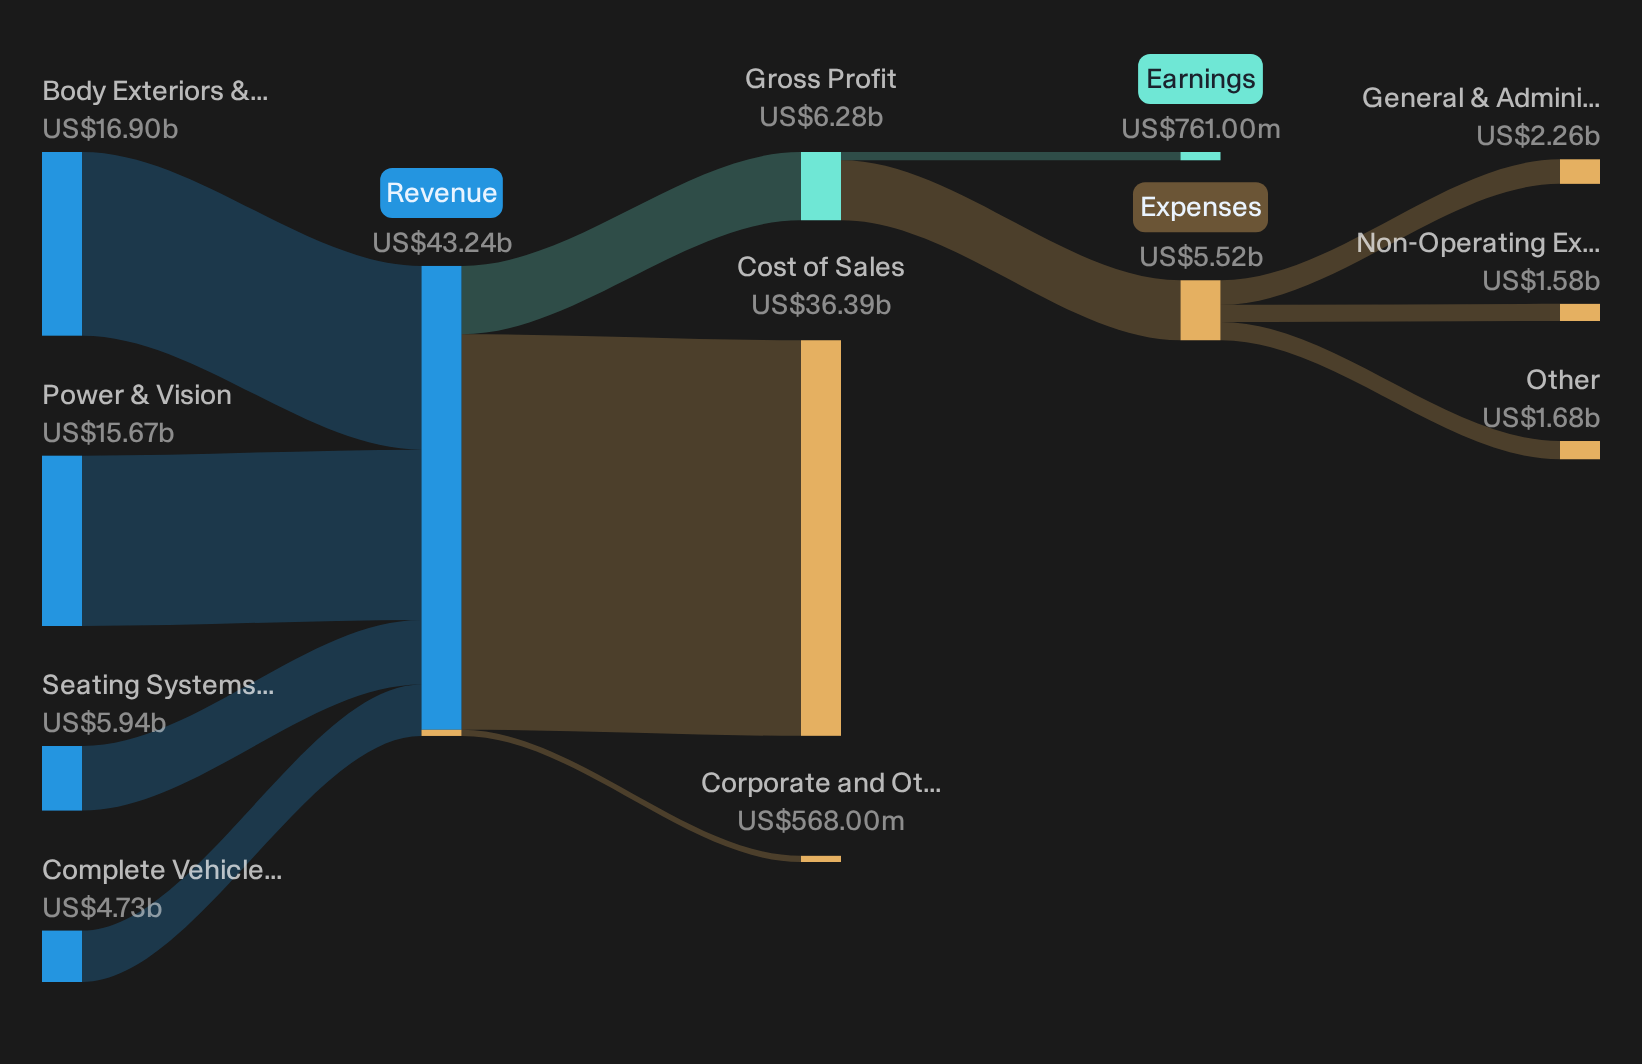
Magna International is a global auto supplier that designs and builds components, seating, powertrain systems and complete vehicles, with Body Exteriors & Structures generating about US$16.9b of revenue, Power & Vision US$15.7b, Seating Systems US$5.9b and Complete Vehicles US$4.7b, and the business carries a market cap near CA$24.3b.
"Magna International is focusing on operational excellence and restructuring actions, which are expected to result in meaningful margin expansion over the next two years. The company anticipates significant improvements in free cash flow due to the normalization of capital spending, particularly now that investments in battery enclosure assembly are behind them."
What really matters from here is how one less visible cost pressure shapes that margin story and ultimately cushions the dividend through the cycle.
That quiet cost squeeze is exactly why the full narrative for Magna International matters for seeing how Magna International’s cash generation, capital spend and dividend ambitions could ultimately decouple.
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources is a heavyweight in the Dividend Powerhouses screen because its large upstream oil and gas production throws off the cash that supports a sizable, well covered payout. Recent corporate moves are shaping how durable that income profile looks from here.
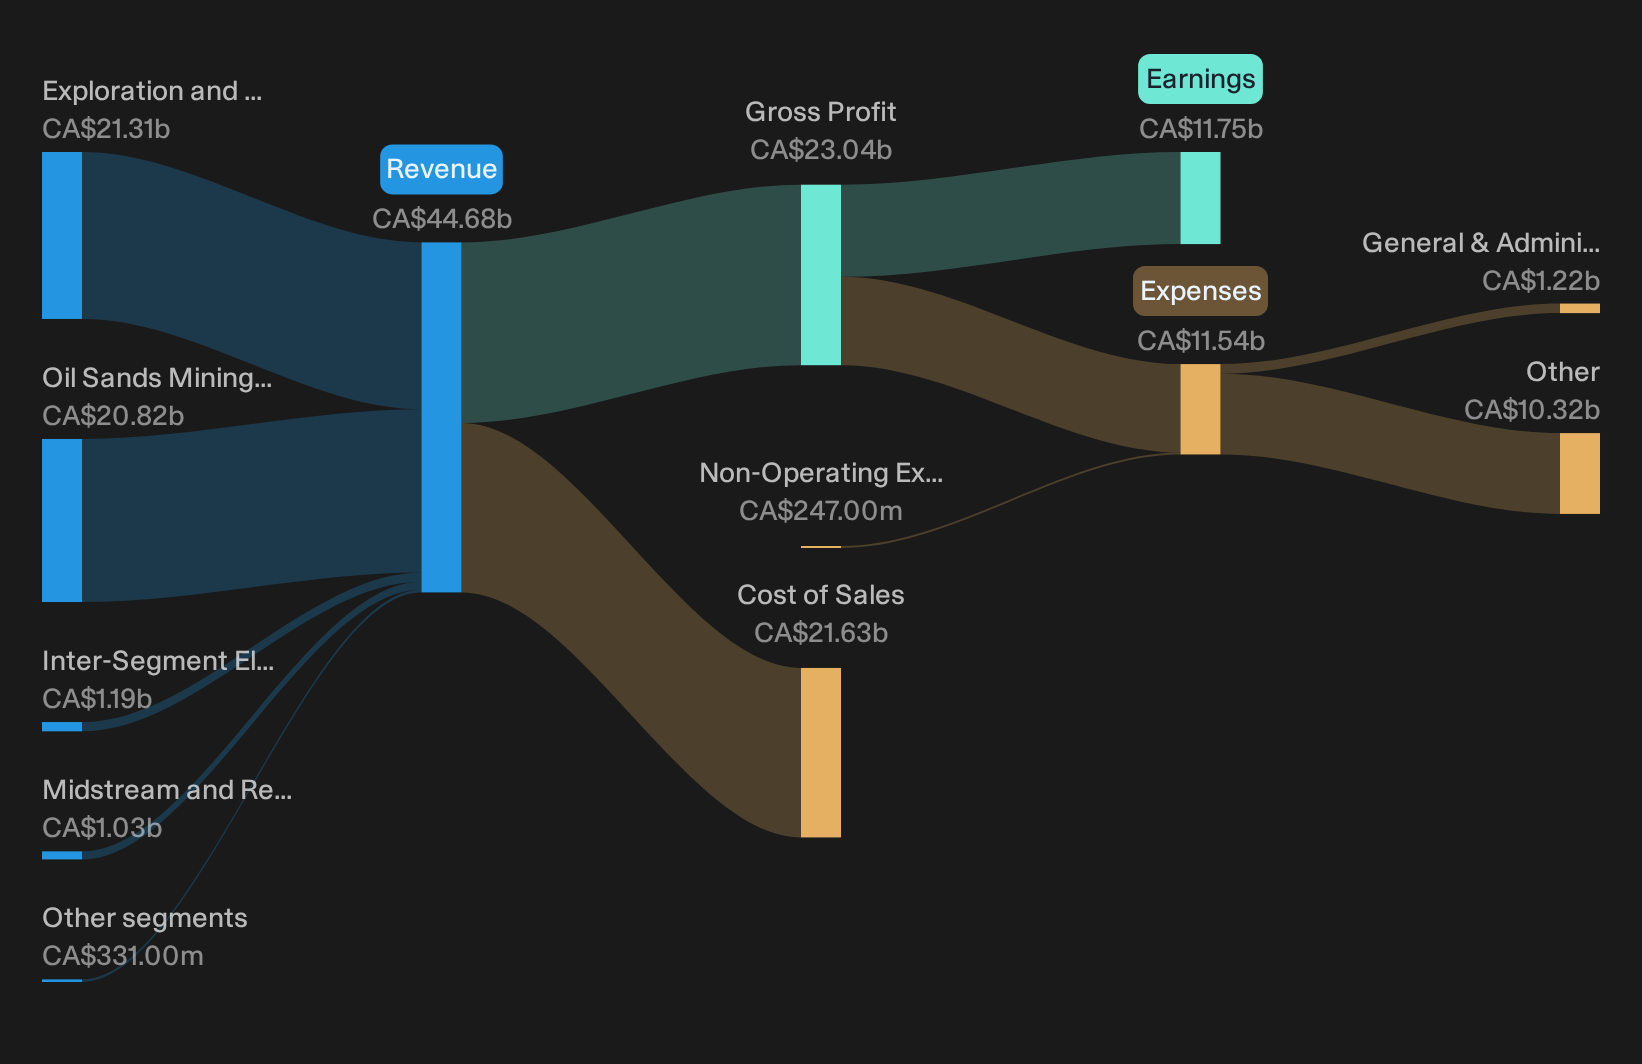
Canadian Natural Resources generates most of its income from exploration and production in North America at about C$21.3b and oil sands mining and upgrading at roughly C$20.8b, with smaller contributions from midstream and refining and the North Sea and Offshore Africa. The group carries a market value near C$140.3b.
"Recent accretive acquisitions have expanded production and reserves with minimal increase to the 2025 capital budget, positioning Canadian Natural for immediate cash flow growth and increased future revenues as these assets are developed."
The strength of that dividend story could look very different depending on how one brewing pressure on future earnings and cash flows plays out.
That brewing pressure is exactly why reading the full narrative for Canadian Natural Resources can help you see whether Canadian Natural Resources’ dividend story is quietly strengthening or at risk of stalling.
Seeking Fresh Alternatives For Your Watchlist
Fresh dividend and sector stories can move from quiet accumulation to full breakout before most investors react. Consider ideas while they are still under the radar for now and decide whether they fit your approach.
- Look for the next potential momentum shift by scanning curated quality picks in the 6 high quality undervalued stocks before crowded trades push valuations away from your preferred entry zone.
- Identify resilient operators with balance sheet strength using the curated list of solid balance sheet and fundamentals (7 results) list while financing conditions may still reward prudence rather than excess leverage.
- Track where long term capital may be building by reviewing the focused 8 resilient stocks with low risk scores before lower volatility profiles are repriced by yield-focused investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com