
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Smucker (SJM) Falling Unit Sales
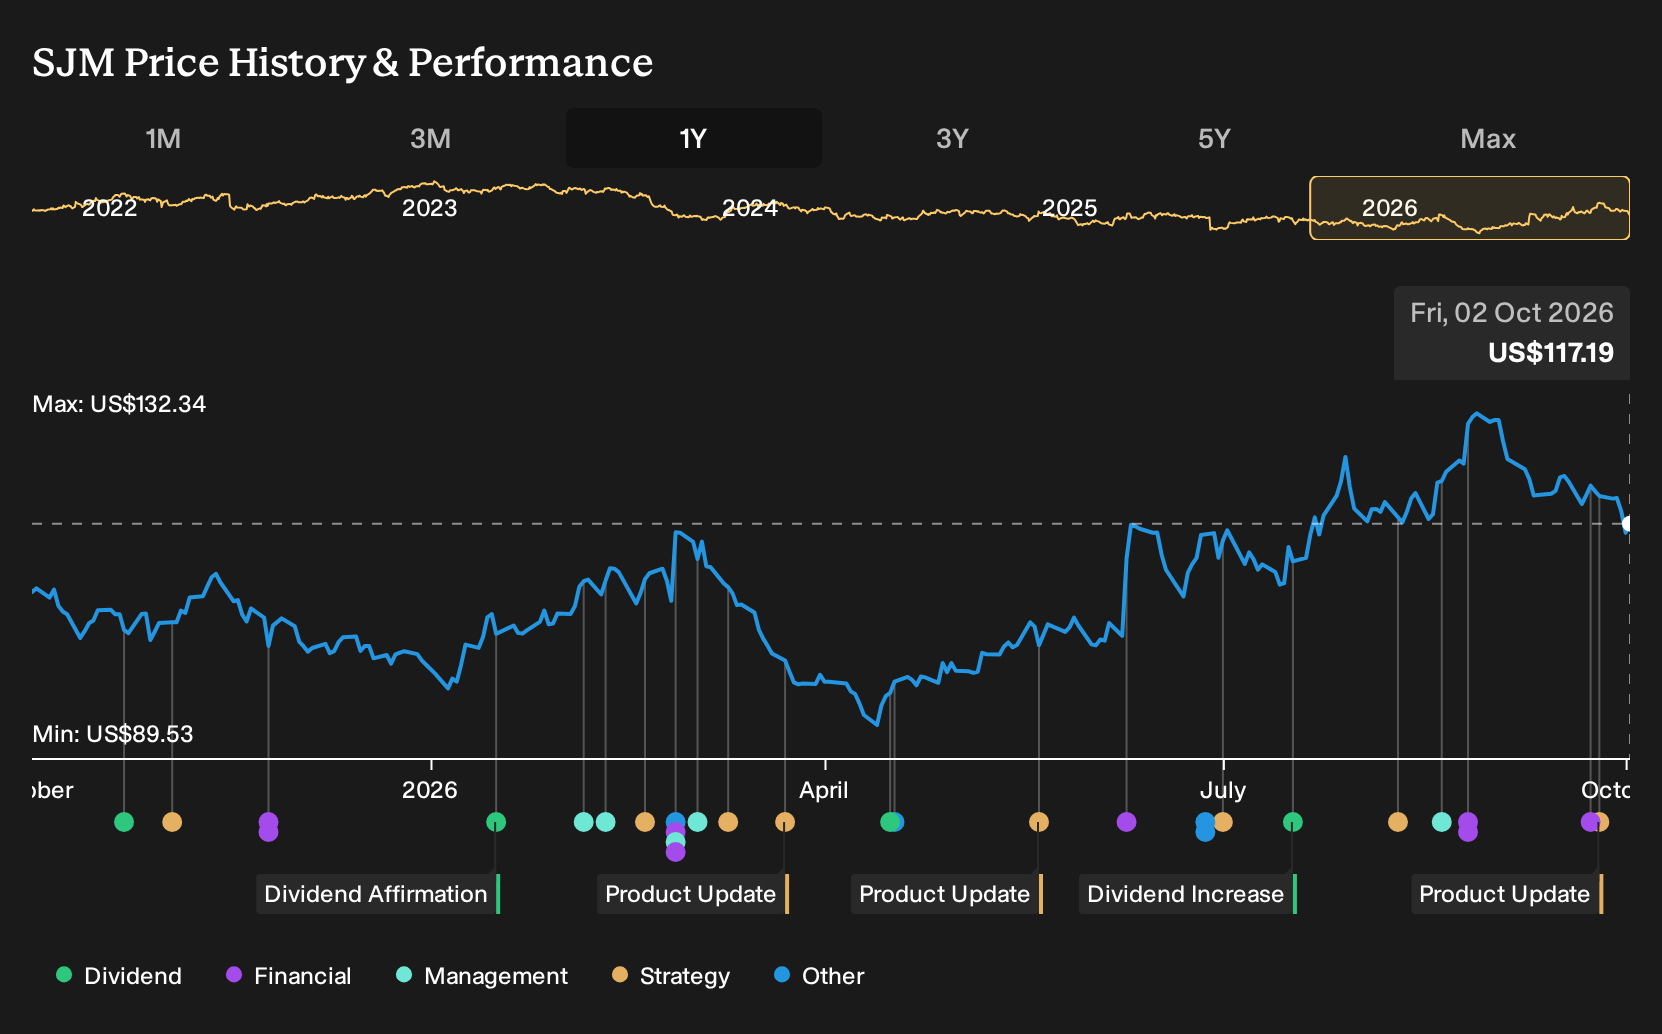
- J. M. Smucker recently leaned into seasonal demand with a broad fall lineup across Hostess, Milk-Bone and Uncrustables. The company also filed an omnibus shelf registration for potential future issuance of debt, common and preferred shares, warrants and units.
- The combination of declining unit sales, a tougher demand backdrop and shrinking return on invested capital puts renewed pressure on how effectively J. M. Smucker can deploy any capital it raises from this expanded financing flexibility.
- We will now see how J. M. Smucker's investment narrative is affected by weaker unit demand and a tougher backdrop for profitable reinvestment.
J. M. Smucker Investment Narrative Recap
To stay on board with J. M. Smucker, an investor needs to believe this portfolio of mature brands can turn projected earnings growth into stronger returns on capital despite flat revenue expectations. The key near term swing factor is still execution on pricing, cost cuts and mix, especially in coffee and sweet baked snacks where elasticity and SKU clean up matter most.
The biggest risk remains volume pressure as past pricing actions and changing consumer preferences intersect with heavier competition and private label. The recent fall product push across Hostess, Milk-Bone and Uncrustables feels more incremental than game changing, so it does not materially alter that core risk reward trade off.
The shelf registration looks most relevant right now because it directly affects how J. M. Smucker funds the next phase of its plan. With high debt, a 3.82% dividend that is not well covered by earnings and recent one off items in the P&L, extra flexibility to issue debt or equity could shape how quickly management can pursue automation, marketing and M&A priorities.
For catalysts, any eventual use of this shelf to refinance borrowings or support restructuring and SKU rationalization would tie into the margin story analysts are watching through fiscal 2027. Execution risk cuts both ways. Fresh capital, if deployed carefully into core brands such as coffee, pet snacks and sweet baked snacks, could support the forecast 21.1% annual earnings growth. Poor allocation would amplify concerns about a low 4% return on equity and already rich P/E multiples.
J. M. Smucker's current narrative centers on analysts expecting revenue to stay fairly flat, with projections for about US$9.1b in sales and US$1.0b in earnings by 2029. That path assumes earnings rise by roughly US$770.5m from about US$229.5m today, which is more than a fourfold increase in profit even if top line growth is limited.
Uncover why J. M. Smucker's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle around J. M. Smucker focuses on execution risk in Sweet Baked Snacks. The most bearish analysts already assumed revenue would drift to about US$8.7b by 2029 with margins at 11.6%, compared with flat revenue at US$9.1b in consensus. Seasonal launches and the fresh shelf registration could push both narratives to evolve from here.
Explore 2 other J. M. Smucker fair value estimates, including one that suggests it could be worth just $141.44!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your J. M. Smucker research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for J. M. Smucker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. M. Smucker's overall financial health at a glance.
Looking for more J. M. Smucker sized investment ideas?
If J. M. Smucker has you thinking harder about capital allocation, return profiles and balance sheet strength, it can help to line it up against a wider watchlist of potential opportunities.
- For investors hunting for underappreciated quality, scan a curated set of potential mispriced opportunities through the 31 high quality undervalued stocks.
- If dependable income is your focus, size up businesses that combine higher yields with staying power using the 7 dividend fortresses.
- When capital preservation comes first, narrow your attention to companies with steadier risk profiles through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com