
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
It Might Not Be A Great Idea To Buy TMK Chemical Bhd (KLSE:TMK) For Its Next Dividend
TMK Chemical Bhd (KLSE:TMK) stock is about to trade ex-dividend in 3 days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. Meaning, you will need to purchase TMK Chemical Bhd's shares before the 7th of October to receive the dividend, which will be paid on the 4th of November.
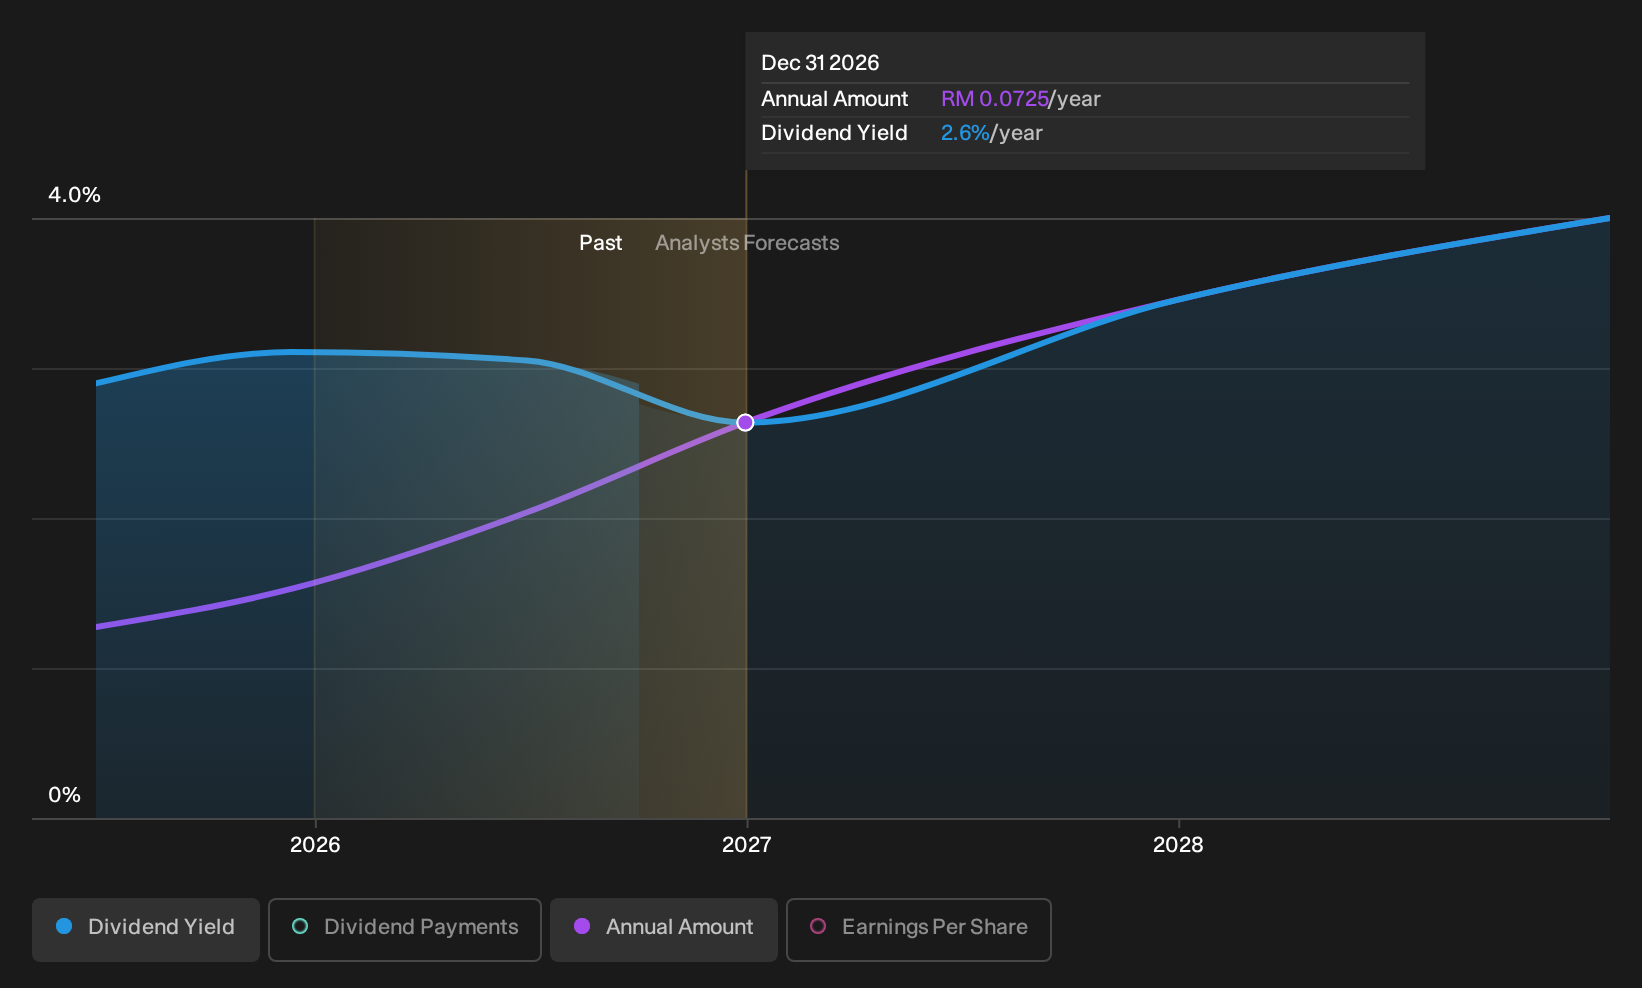
The company's upcoming dividend is RM00.036 a share, following on from the last 12 months, when the company distributed a total of RM0.072 per share to shareholders. Based on the last year's worth of payments, TMK Chemical Bhd has a trailing yield of 2.6% on the current stock price of RM02.75. If you buy this business for its dividend, you should have an idea of whether TMK Chemical Bhd's dividend is reliable and sustainable. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. TMK Chemical Bhd paid out more than half (51%) of its earnings last year, which is a regular payout ratio for most companies. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. Over the past year it paid out 164% of its free cash flow as dividends, which is uncomfortably high. It's hard to consistently pay out more cash than you generate without either borrowing or using company cash, so we'd wonder how the company justifies this payout level.
TMK Chemical Bhd paid out less in dividends than it reported in profits, but unfortunately it didn't generate enough cash to cover the dividend. Were this to happen repeatedly, this would be a risk to TMK Chemical Bhd's ability to maintain its dividend.
Check out our latest analysis for TMK Chemical Bhd
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
When earnings decline, dividend companies become much harder to analyse and own safely. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. From this viewpoint, it's unfortunate that earnings per share have declined 8.3% over the last year.
We'd also point out that TMK Chemical Bhd issued a meaningful number of new shares in the past year. It's hard to grow dividends per share when a company keeps creating new shares.
Another key way to measure a company's dividend prospects is by measuring its historical rate of dividend growth. TMK Chemical Bhd has delivered an average of 43% per year annual increase in its dividend, based on the past two years of dividend payments. That's interesting, but the combination of a growing dividend despite declining earnings can typically only be achieved by paying out more of the company's profits. This can be valuable for shareholders, but it can't go on forever.
To Sum It Up
From a dividend perspective, should investors buy or avoid TMK Chemical Bhd? TMK Chemical Bhd had an average payout ratio, but its free cash flow was lower and earnings per share have been declining. It's not an attractive combination from a dividend perspective, and we're inclined to pass on this one for the time being.
So if you're still interested in TMK Chemical Bhd despite it's poor dividend qualities, you should be well informed on some of the risks facing this stock. Case in point: We've spotted 1 warning sign for TMK Chemical Bhd you should be aware of.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.