
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Amphenol (APH) Earnings Beat Puts Valuation Back In Focus
Amphenol (APH) is back in focus after a recent earnings release that reported strong year over year revenue growth, record adjusted EPS, and guidance above expectations, driven largely by AI data center demand.
The recent AI driven earnings beat has been met with strong buying interest, with Amphenol’s share price returning 8.65% over the past month and 24.49% year to date, while total shareholder return over the past year has reached 43.29% as momentum builds off a very large three-year gain.
Look beyond Amphenol’s AI-driven surge and explore other infrastructure opportunities benefiting from similar data center demand with a curated list of 90 AI infrastructure stocks
After a surge built on AI fueled earnings and a three year total return that is already very large, the real tension now is simple. Is Amphenol’s recent jump the opening act, or has most of the upside already been priced in as investors reassess valuation next?
Most Popular Narrative: 16% Undervalued
Amphenol's most followed narrative pegs fair value at $103.67, comfortably above the recent $86.96 close, which puts current enthusiasm in a different light.
The CommScope transaction is the strategic piece. Amphenol closed the $10.5b acquisition of CommScope's Connectivity and Cable Solutions business in January 2026, adding roughly 20,000 employees and, critically, significant fiber optic interconnect capability. Management guided CCS to approximately $4.1b in 2026 sales, and some analysts believe that target is conservative. Before this deal Amphenol was a copper and connector company with optical aspirations. After it, the architecture neutrality argument above is actually true rather than aspirational.
See why 7 investors see Amphenol as 16% undervalued.
According to isidrohg, the narrative values Amphenol on strong revenue growth of 15.7% a year, a profit margin near 17.7%, and a discount rate of 9.1%, which together support that $103.67 fair value estimate versus the current market capitalization of about $211.3b.
The same storyline leans heavily on earnings power, with annual profit growth of 20.1% forecast, a return on equity above 30%, and a view that the business can justify a future P/E of 38.5 given its scale in connectors, fiber and sensors across data centers, industrials and other end markets.
On this framework the gap between the $86.96 share price and the $103.67 narrative fair value implies roughly a 16% discount, even after a very large three year total return, which is why valuation debates are now centering less on whether Amphenol benefits from AI demand and more on how long the current growth and order momentum can support these assumptions.
Result: Fair Value of $103.67 (UNDERVALUED)
Still, two pressure points could quickly undermine that story if hyperscaler capex eases or the CommScope integration starts to drag on margins.
Find out about the key risks to this Amphenol narrative.
Another View: What Amphenol’s P/E Is Telling You
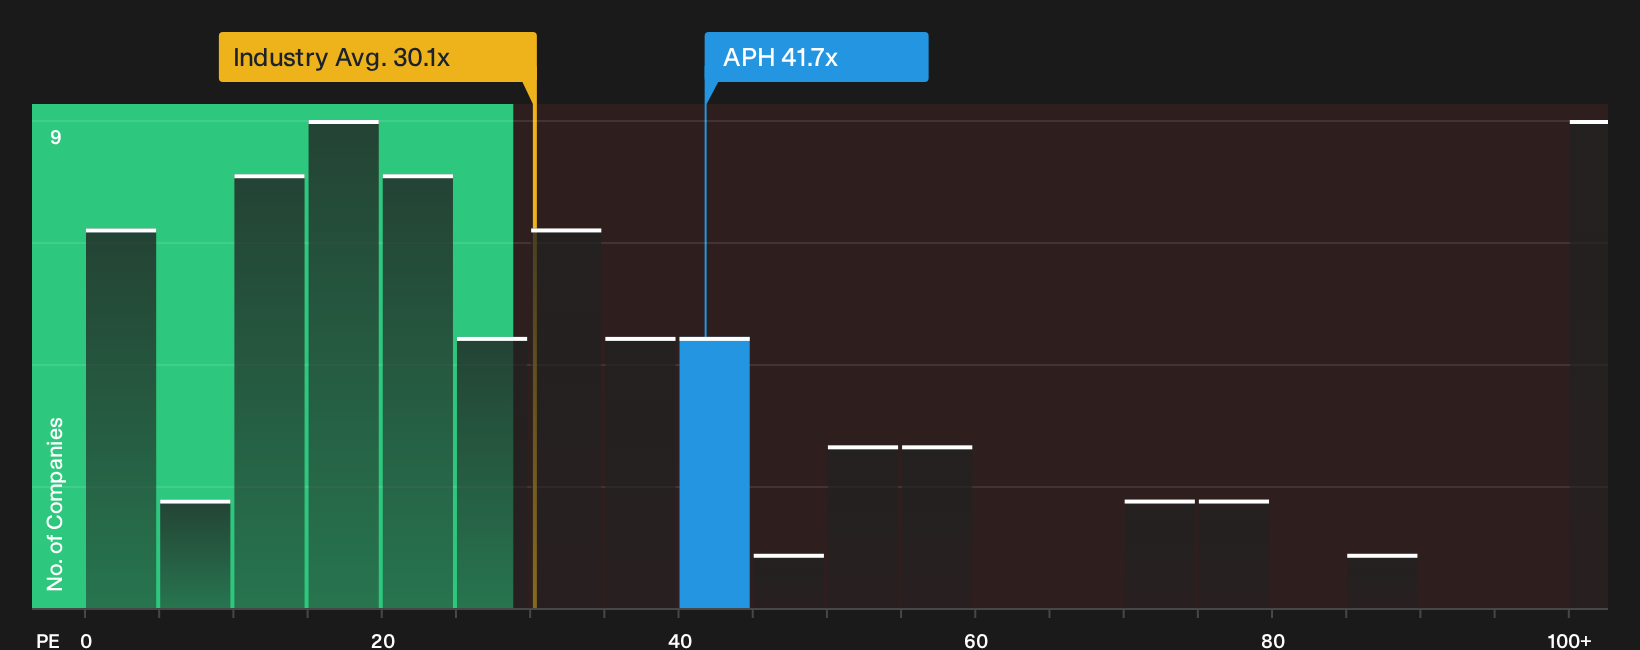
There is a different read on Amphenol once the focus shifts from that $103.67 narrative fair value to the plain P/E math. At about 41.7x earnings, the stock trades above the US Electronic industry on 30.1x and also above a fair ratio of 38.8x. That premium narrows against peers on 96.1x, yet it still leaves you asking whether most of the good news is already baked into the price.
For anyone weighing that gap between rich earnings multiples and growth expectations, it can help to see how the numbers line up across sectors before making a move. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and growth expectations create plenty to debate. Move quickly, review the numbers yourself, and weigh both sides of the story through 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Amphenol?
If Amphenol has sharpened your focus on quality, you can use that momentum. Filter clear opportunities, compare fundamentals, and keep your watchlist stocked with fresh candidates.
- Target value potential early and sort through a curated set of 19 high quality undiscovered gems before the crowd pays attention.
- Strengthen your core holdings by scanning a list of solid balance sheet and fundamentals (25 results) that emphasizes financial resilience and durable fundamentals.
- Cut down portfolio stress by focusing on stability and consistency through a 31 resilient stocks with low risk scores that screens for resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com