
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pony AI (PONY) Stock May Still Look Overvalued Despite Driverless Trial News
Pony AI has been under heavy pressure, and the stock’s slide now puts a sharp spotlight on a simple question for investors: Is the current share price still aligned with what the business is actually generating in sales?
- The share price has fallen 74.4% over the past year, which puts recent trading levels in direct question against the revenue Pony AI is producing.
- Pony AI and Verne have started fully driverless robotaxi passenger trials in Zagreb, which can shape how investors think about future sales potential and the timing of any revenue ramp from its autonomous driving platform.
- Your read on Pony AI is one view; the desks covering it have another. See what analysts think Pony AI's shares could be worth.
The issue now is whether the current Pony AI valuation is adequately supported by its sales profile.
If you are weighing whether Pony AI’s sales can justify today’s share price, it can help to compare it with other AI-focused businesses by starting with 38 AI small caps.
Has Pony AI Run Too Far on Sales?
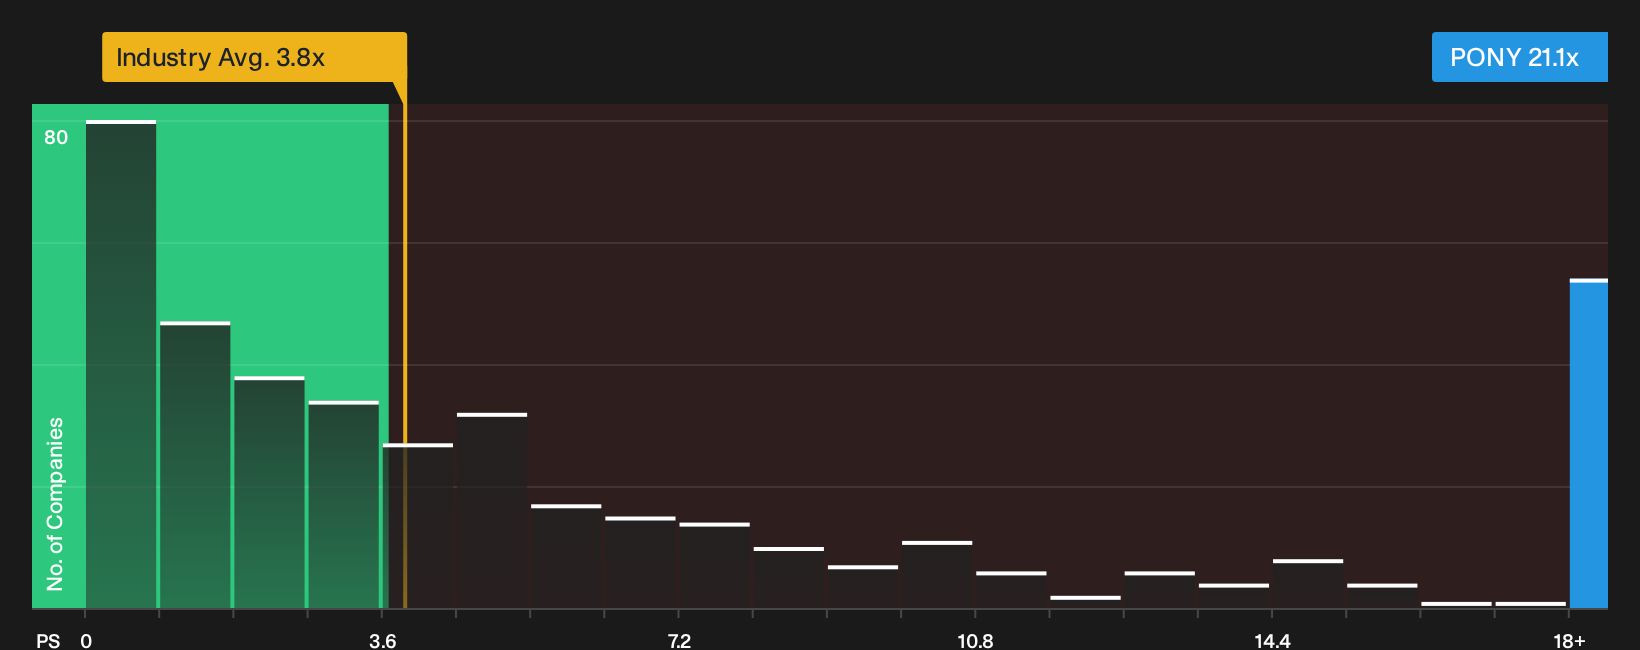
P/S suits Pony AI because revenue is still the cleanest anchor for a business that is not yet generating positive free cash flow. The stock currently trades on a P/S of 21.1x, compared with a Software industry average of 3.8x and a peer group around 5.2x. That is a steep gap for a company where losses are still material, even as investors look to the autonomous driving platform as the eventual driver of the top line.
The model based fair multiple, which adjusts for Pony AI’s growth profile, margins, size and risk, sits well below the current 21.1x P/S. That gap signals the shares screen overvalued on this metric and that the framework is heavily penalising the ongoing cash burn and execution risk. Because the Zagreb robotaxi trials with Verne and Uber spotlight the commercial story, the current P/S implies that a lot of future sales from such deployments are already reflected in the valuation. Explore the numbers behind Pony AI's P/S valuation.
The Pony AI Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Pony AI valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today’s price. Rather than leaning on a single multiple or model point estimate, each narrative lays out the key assumptions behind its view so you can track those against Pony AI’s reported numbers on the Community page over time.
One of the top community narratives on Pony AI: 70% undervalued
"Global ride hailing and urban transport platforms are increasingly adopting autonomous vehicles, and Pony AI’s joint deployment model with partners like Uber, Bolt, Verne and ComfortDelGro creates an asset light path…"
Discover why this Narrative puts Pony AI at 70% undervalued.
The Pony AI price is only one piece of the investment puzzle
For Pony AI, the people setting priorities and how they are rewarded can matter as much as any multiple, and that leadership picture has not been unpacked here. See who runs Pony AI and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com