
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GFL Environmental (TSX:GFL) Names A New COO, Is The Stock Still Below Fair Value?
GFL Environmental (TSX:GFL) just reshaped its leadership bench. The company elevated Allen Gransch to Chief Operating Officer, bringing SECURE Waste Infrastructure experience directly into day to day operations.
Recent trading suggests momentum around GFL Environmental is picking up, with a 1-day share price return of 3.98% helping lift its CA$59.83 share price and contributing to a 90-day gain of 4.62%. This comes even though the 1-year total shareholder return is down 7.87% and the 3-year figure sits at 35.01%.
Scan how GFL Environmental compares with other operators reshaping their operations by running the hand picked list of solid balance sheet and fundamentals (7 results) alongside this leadership change story.
Bulls see GFL Environmental pairing fresh operating leadership with a discounted share price. Bears point to the current loss and mixed recent returns. Which story looks closer to fair value once you run the numbers?
Most Popular Narrative: 17% Undervalued
GFL Environmental’s most followed valuation storyline pegs fair value at about CA$72.50, well above the last close at CA$59.83. This places the new operating leadership moves in the middle of a much bigger re-rating debate.
The company is investing significantly in sustainability-related projects like EPR and RNG, which are anticipated to boost future revenue and earnings through increased efficiency and new revenue streams.
The planned sale of the ES business will improve the balance sheet, enabling share buybacks and increased dividends, which could enhance earnings per share (EPS) and overall shareholder value.
See why 21 investors see GFL Environmental as 17% undervalued.
Result: Fair Value of CA$72.50 (UNDERVALUED)
Still, that 2029 earnings story leans heavily on higher profit margins and a rich 54.6x future P/E, while divesting the ES business could drag on reported revenue.
Find out about the key risks to this GFL Environmental narrative.
Another View: What Multiples Say About GFL Environmental
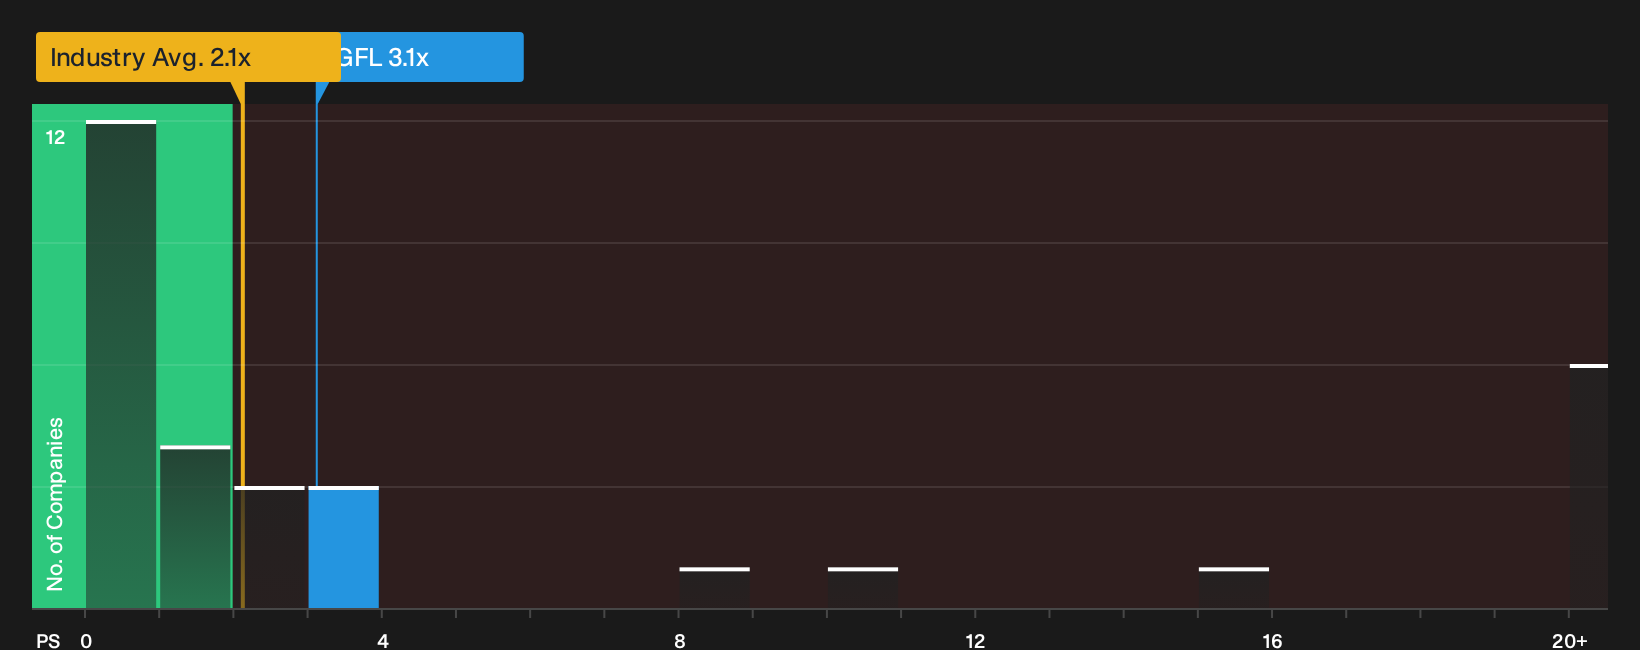
That CA$72.50 fair value rests on a rich 54.6x future P/E story. On today’s numbers, GFL Environmental trades on a P/S of 3.1x, which is higher than both its peer group at 2.5x and the Canadian Commercial Services sector at 2.1x.
The fair ratio for GFL Environmental is also 3.1x, so the current P/S lines up closely with where the market could gravitate over time. If the stock is already priced in line with that fair ratio while still being labelled undervalued on earnings forecasts, how much margin for error do you think is really there?
For a closer read on how this sales multiple stacks up against peers and that fair ratio in detail, take a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the optimism around GFL Environmental really stacks up against the risks and current pricing? Act while the data is fresh and weigh the upside using 2 key rewards
Looking for more GFL Environmental sized ideas?
If momentum around GFL Environmental has your attention, do not stop here. Broaden your watchlist now with fresh ideas filtered by clear, data driven criteria.
- Target potential bargains by zeroing in on high quality businesses that still trade on muted expectations through the 5 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with generous yields and resilient payouts using the 1 dividend fortresses.
- Prioritise capital preservation by filtering for resilient businesses with lower risk profiles via the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com