
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Beam Therapeutics (BEAM) Could Be 52% Undervalued Following Its Lawsuit Over Research Misuse
Beam Therapeutics (BEAM) is in the spotlight after filing a lawsuit that accuses former scientist Zi Jun Wang of misusing confidential research to help launch Chinese gene editing startup YolTech Therapeutics.
For investors watching Beam Therapeutics, the lawsuit lands after a stretch of weak momentum, with the share price down about 16% over 30 days and roughly 30% over 90 days. The 3 year total shareholder return is positive, while the 5 year total shareholder return remains deeply negative.
Scan beyond Beam Therapeutics and see how other genetic medicine players with stronger momentum or balance sheets line up in our curated list of 19 high quality undiscovered gems.
Beam Therapeutics now trades well below its recent levels after that slide, which raises a simple fork-in-the-road question. Is the bulk of the rerating already in the rear-view mirror, or is meaningful upside still on the table once you compare the current price with fundamentals?
Most Popular Narrative: 52% Undervalued
Against a last close of $24.39, the most followed narrative pegs Beam Therapeutics at a fair value of $51.07, so the gap to that estimate is wide and places significant emphasis on how its lead programs progress from here.
Beam Therapeutics is focusing on advancing their two core franchises in hematology and liver genetic diseases, with lead programs BEAM-101 for sickle cell disease and BEAM-302 for alpha-1 antitrypsin deficiency, both showing preclinical validation that could support the development of new treatments. The BEACON trial for BEAM-101 reported rapid neutrophil engraftment and high HbF induction, which the narrative suggests could indicate potential clinical differentiation and result in a larger addressable patient base and commercial opportunity.
See why 60 investors see Beam Therapeutics as 52% undervalued.
Result: Fair Value of $51.07 (UNDERVALUED)
Still, the narrative around Beam Therapeutics can be knocked off course if safety concerns around busulfan conditioning persist, or if funding needs force heavier dilution.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: Beam Therapeutics Looks Expensive On Sales
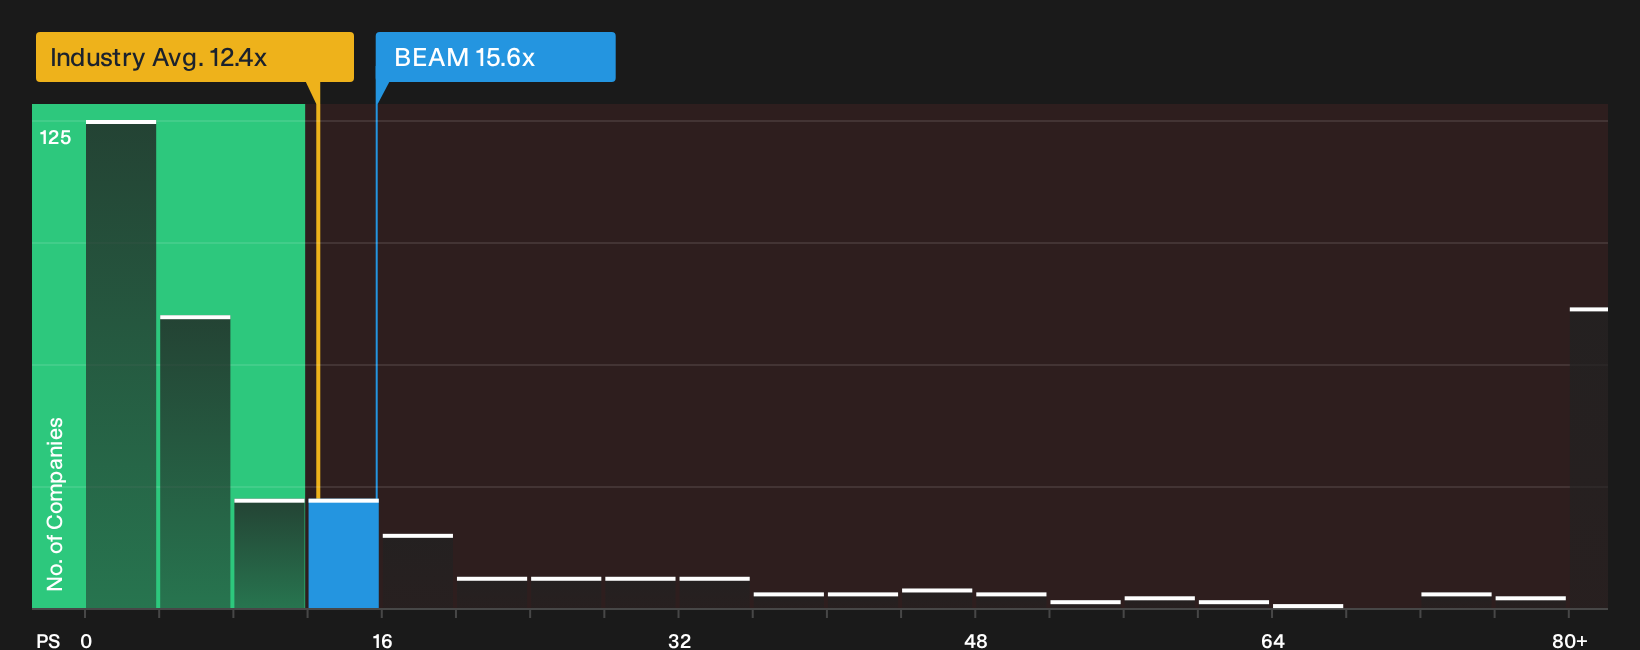
The fair value of $51.07 from the consensus narrative points to upside, but the simple sales multiple tells a tougher story. Beam Therapeutics trades on a P/S of 15.6x, compared with 12.4x for the US biotech sector and a fair ratio of just 0.8x, which implies meaningful valuation risk if sentiment cools.
For investors weighing these conflicting signals, it helps to see how the current price compares with what the numbers suggest in a clearer way. The starting point is our valuation breakdown built around that sales metric, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Beam Therapeutics valuation and risk profile are clear, so move quickly, review the underlying data yourself, then weigh the 2 key rewards and 2 important warning signs.
Ready to find your next idea beyond Beam Therapeutics?
If you stop with Beam Therapeutics, you miss a wider field of opportunities that might suit your risk limits, income goals, or preference for sturdier balance sheets.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations using our focused list of 28 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a curated list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching their finances.
- Hunt for earlier stage opportunities by checking a filtered group of 8 elite penny stocks with strong financials that already show stronger financial traits than most peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com