
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Allied Defense Demand At Moog (MOG.A) Has Changed Its Investment Story
- Recent commentary has highlighted Moog as a key supplier of advanced aerospace, defense, and motion control technologies to allied militaries, with investors focusing on its exposure to elevated global defense spending and modernization programs.
- The renewed focus on Moog's role in supporting long-term defense procurement underscores how its order visibility, program breadth, and mission-critical systems are closely linked to the durability of its defense and aerospace revenue base.
- We will now look at how Moog's reinforced role in allied defense modernization could influence the broader investment narrative around the business.
Scan beyond Moog's defense exposure and compare other contractors tied into rising allied procurement with our curated list of 39 power grid technology and infrastructure stocks.
Moog Investment Narrative Recap
To own Moog, you need to be comfortable with a defense centered motion control specialist whose fortunes are closely tied to long running programs with U.S., NATO and Indo Pacific allies, and to industrial and medical automation. The near term story still hinges on converting a strong order book into cash without letting tariffs and higher inventory needs eat into margins.
The Five Eyes defense momentum story does not materially change that near term setup. The biggest swing factor remains free cash flow execution as Moog supports growth with higher working capital. The key risk is any reset in allied defense budgets or major aerospace platform delays that slow orders or pressure pricing.
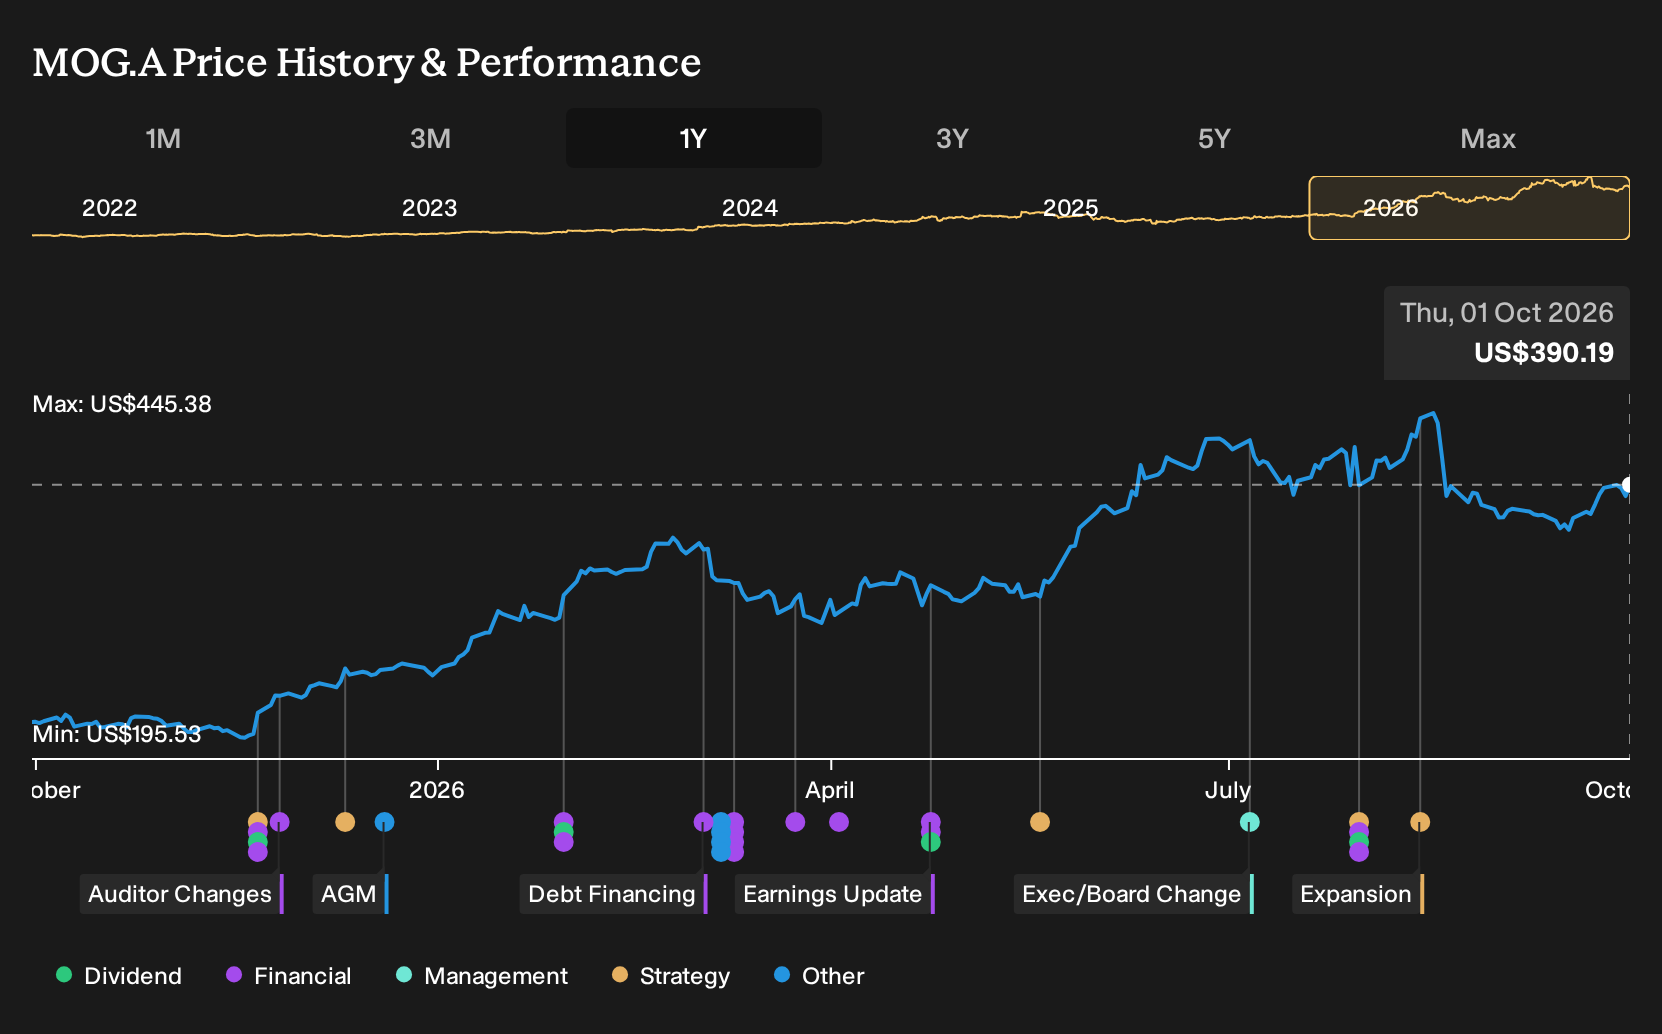
Recent coverage grouped Moog with other Five Eyes exposed contractors that have shown strong share price momentum. That spotlight matters because it ties directly to Moog’s long discussed catalyst: the depth of allied modernization programs that support its Space and Defense and Military Aircraft work and help underpin multi year program visibility.
For you as an investor, that linkage cuts both ways. Stronger attention to Moog’s role in advanced aerospace and defense can support confidence in its backlog, aftermarket service potential and ongoing R&D spend in areas like actuators and optoelectronics. It also sharpens focus on the risk that any change in procurement tempo or tariffs could filter quickly into margins and cash generation.
Moog's current analyst narrative points to revenues of $5.3b and earnings of $389.4m by 2029, off a base of $377.1m in earnings today. That profile implies 7.1% yearly revenue growth and an earnings increase of about $12.3m from current levels.
Uncover why Moog's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard on Moog’s record backlog as the real story. Those bullish analysts were modeling about $5.4b of revenue and $397.4m of earnings by 2029, with a $520.0 price target. That is far more optimistic than consensus and could shift again as the Five Eyes defense momentum evolves.
Explore 3 other Moog fair value estimates, including one that suggests as much as 33% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Moog research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Moog. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Moog's overall financial health at a glance.
Looking for More Ideas Beyond Moog?
If the Moog story has sharpened your thinking about defense, automation and cash generation, it can be useful to compare it with other companies that fit different risk and return profiles. The Simply Wall St Screener gives you a structured way to widen your watchlist without losing sight of balance sheets, income quality and longer term resilience.
- For investors who want potential upside but still care about business quality, check out a curated set of 19 high quality undiscovered gems that combine solid fundamentals with lower market attention.
- If capital preservation is front of mind and you prefer steadier profiles, focus on a 31 resilient stocks with low risk scores that filters for resilient financials and lower risk characteristics.
- When you care most about financial strength and durability through cycles, start with a list of solid balance sheet and fundamentals (25 results) to find companies with robust balance sheets and consistent fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com