
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coinbase Global (COIN) Stock Trades At A Premium To Its Sales Base
Coinbase Global has seen its stock swing sharply in recent years, and at a last close of US$189.29 the question for investors is how well that price lines up with the sales the business is generating. With such a volatile share history and a crypto focused model, the key issue is whether the current market value can be grounded in the revenue base.
- Over the past 3 years the stock is up about 153.7%, which puts the spotlight on whether that climb is supported by the underlying sales power of Coinbase.
- Fresh approvals such as CFTC registration for Coinbase Clearing LLC and moves into areas like tokenized equities and on chain lending can influence how quickly trading and related services might translate into higher revenue and potentially different P/S expectations.
- There is a second opinion on Coinbase Global worth weighing. See what analysts think Coinbase Global's shares could be worth.
For investors, the debate is whether Coinbase Global's current share price can be justified by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales based valuation question beyond Coinbase Global, you can compare this stock with the companies in the 18 cryptocurrency and blockchain stocks.
Does Coinbase Global Look Pricey on Sales?
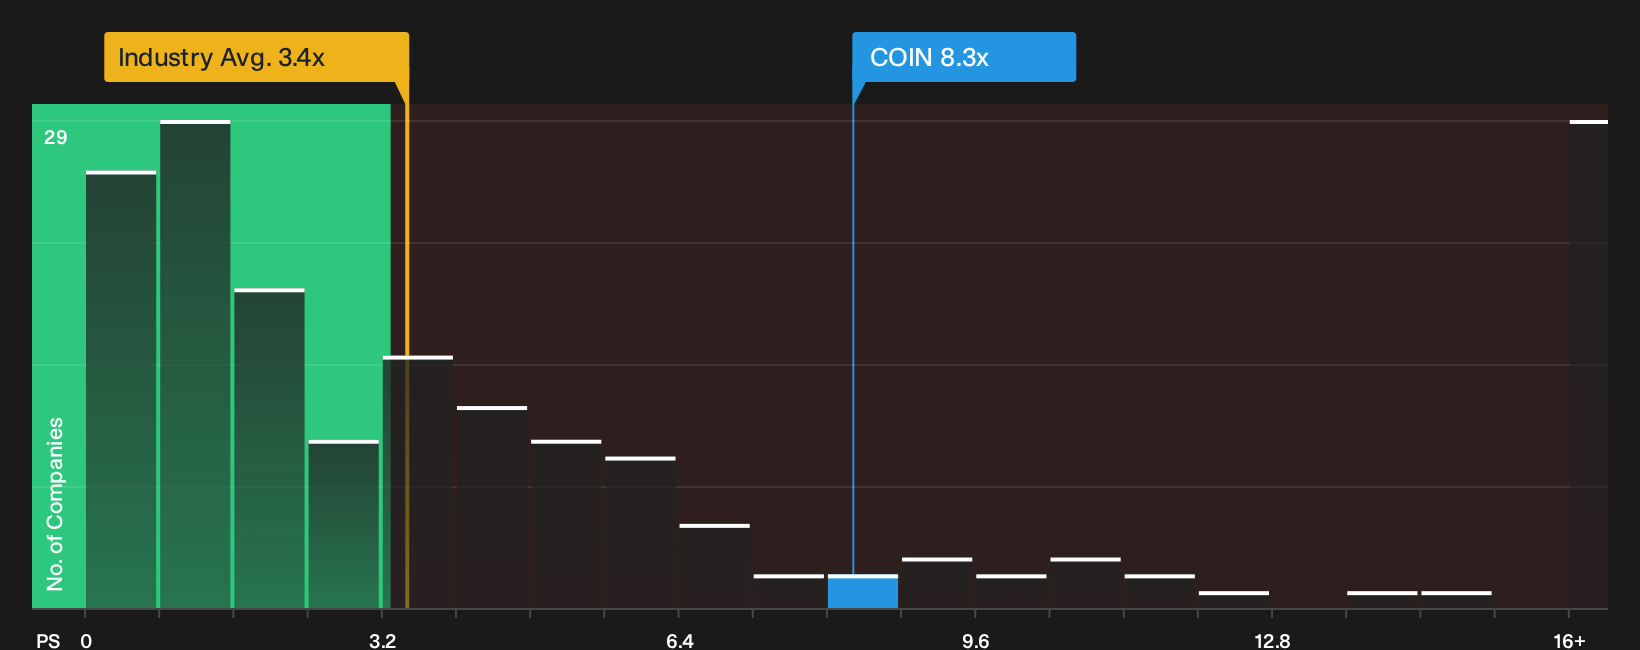
P/S is a cleaner way to look at Coinbase Global because revenue from trading, custody and other services tends to move faster than reported earnings. On this lens the stock trades on a P/S of 8.3x, which is above both the Capital Markets industry average of 3.4x and the peer group on about 9.6x.
The Fair Ratio model, which adjusts the P/S benchmark for Coinbase Global's size, margins, risk profile and sector, suggests a lower multiple than where the shares change hands today, so the stock screens as overvalued on this metric. Because the CFTC clearing approval and push into tokenization have raised expectations around future activity, investors are effectively paying a premium P/S now for the possibility that these initiatives support stronger sales later. That gap between current pricing and the Fair Ratio sits at the heart of the valuation debate for this stock. Explore the numbers behind Coinbase Global's P/S valuation.
The Coinbase Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coinbase Global valuation puzzle leaves off by spelling out which expectations for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each Narrative presents Coinbase Global's implied fair value as a thesis about the business that you can track over time rather than a single static estimate, and they sit on the platform’s Community page.
Community views on Coinbase Global split along how durable its newer revenue streams really are compared with old style trading activity.
Bull case: 51% undervalued
"Launch and adoption of proprietary blockchain platforms such as Base and the Base super app could drive user growth via novel on-chain utilities…"
Discover why this Narrative puts Coinbase Global at 51% undervalued.
Bear case: 84% overvalued
"The current numbers and business mix imply the share price already reflects a rich outcome for Coinbase Global, with limited room for disappointment…"
Explore why this Narrative puts Coinbase Global at 84% overvalued.
Before acting on Coinbase Global's valuation, there is one more piece to check
Market pricing tells you what traders pay for Coinbase Global today, while forward-looking models sketch where professionals think the business could be a few years from now, and that gap can be revealing. Explore where analysts expect Coinbase Global to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com