
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Quality Stocks To Own In October 2026
Tokyo inflation recently reached 2.7% as subsidies rolled off, and the Bank of Japan is now openly weighing a rate hike. When money becomes more expensive, weaker balance sheets can feel the strain while financially robust Japanese companies are often better positioned to cope. This article highlights three stocks with strong returns on equity, resilient past performance and solid finances that investors may want to study more closely.
The three Japanese stocks covered below are just a sample, and the full screen surfaced 20 more businesses with similar return on equity profiles, steady past performance and balance sheet strength that are not discussed here. If you want to identify and analyze potential high conviction ideas built on this same criteria, head straight to the Solid Balance Sheet and Fundamentals screener.
Recruit Holdings (TSE:6098)
Overview: Recruit Holdings runs online hiring platforms like Indeed and Glassdoor alongside staffing and marketing services that connect people and businesses.
Operations: The group generates about ¥1.75t from Staffing, ¥1.57t from HR Technology and ¥570b from Marketing Matching Technologies.
Market Cap: ¥23.33t
Recruit Holdings fits this screener because its HR Technology platforms combine high return on equity with recurring, data-rich hiring services that rely on a strong balance sheet to support ongoing investment through different market conditions.
"The company's steady focus on developing new AI-powered and data-centric services for both jobseekers and employers is aimed at meeting demand for more intelligent, efficient talent matching and workforce solutions globally, with an emphasis on strengthening its service offering and competitive positioning."
The sustainability of its return on equity profile will depend on how changes in efficiency and pricing ultimately affect margins.
That margin story is only half the picture, and the full narrative for Recruit Holdings explains how Recruit Holdings’ capital allocation, competition and rate moves could be quietly reshaping its earnings power.

Tokyo Electron (TSE:8035)
Overview: Tokyo Electron develops and sells high-margin semiconductor production equipment such as coaters, etchers, and deposition tools. These products underpin its solid balance sheet profile.
Operations: The business generates about ¥2.63t from semiconductor production equipment, which is the key driver of its returns and cash generation.
Market Cap: ¥28.60t
Tokyo Electron matters for this solid balance sheet screener because its core chip equipment business combines high return potential with cash-rich operations that can fund growth without stretching the financial side of the house.
"The aggressive roll-out of next-generation smart factories and recently completed large-scale facilities in Miyagi, Kumamoto, and Iwate could drive a step-function improvement in operational efficiency and capacity, leading to meaningfully higher net margins and operating leverage than currently forecast."
What happens to those high return on equity metrics if a single assumption about long-term semiconductor equipment demand quietly shifts direction?
If that scenario is even partly in play, the full narrative for Tokyo Electron maps how Tokyo Electron’s capacity buildout, pricing power and capital choices could be quietly reshaping its risk reward profile.

Fujikura (TSE:5803)
Overview: Fujikura is a Tokyo based manufacturer of optical fibers, network equipment, electronic components and automotive wiring used in global infrastructure.
Market Cap: ¥8.89t
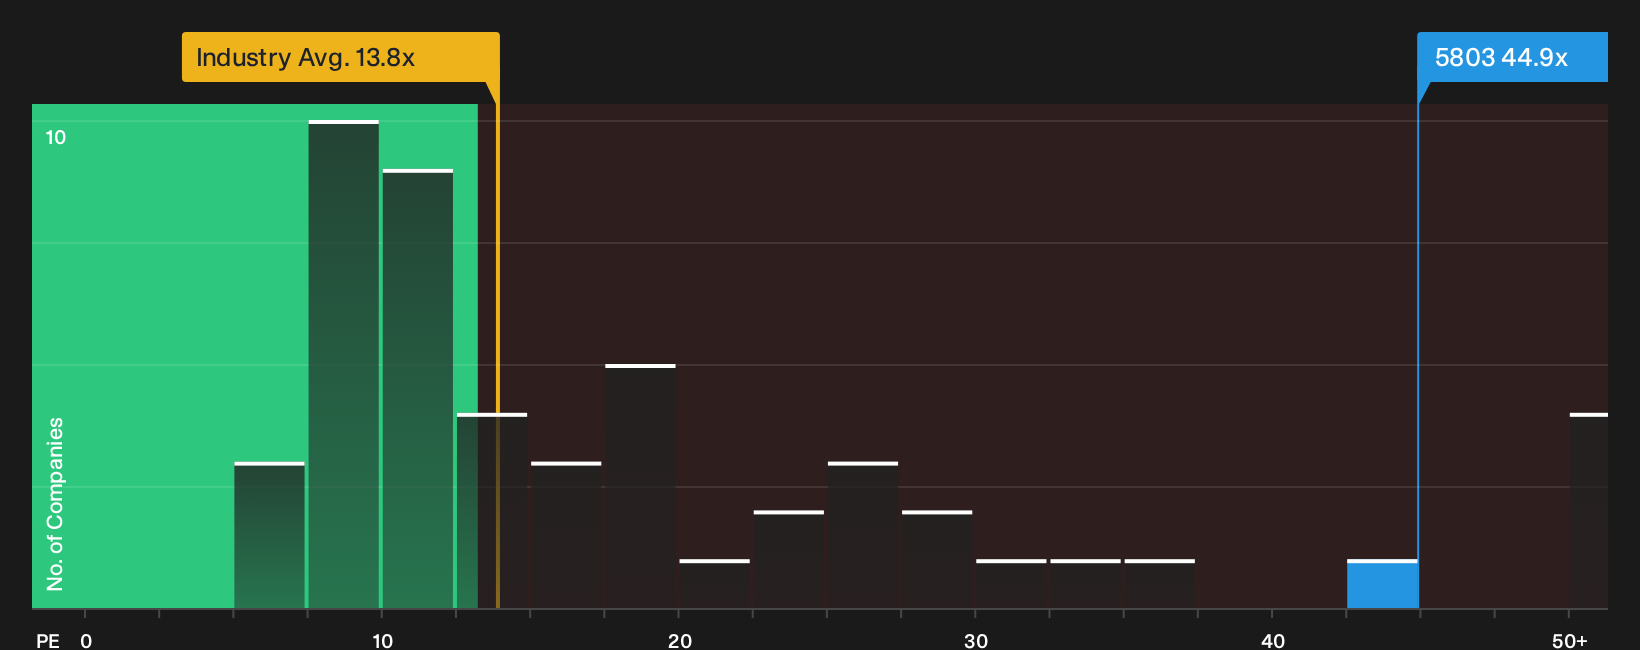
Fujikura fits the Solid Balance Sheet and Fundamentals theme through its telecom fiber and optical component activity. In this segment, high margin, capital intensive products support a 33% ROE and 15.7% net margin backed by high quality earnings. Shareholders still need to weigh how one unseen pressure on that premium 44.9x P/E could affect those hard won economics.
That premium P/E and ROE mix makes it worth studying the 2 key rewards and 1 important major warning sign to see what might be quietly accelerating or capping Fujikura’s momentum.
Seeking Fresh Alternatives Before Others?
Fresh opportunities do not wait. Strong balance sheets, rising momentum and new themes can move quickly out of reach. Review curated stock shortlists before the crowd and consider them early.
- Identify potential breakouts in smaller companies before they become widely covered by tracking 1 elite penny stocks with strong financials that already show financial underpinnings and business traction.
- Explore the AI momentum while it still flies under some radars by scanning 90 AI infrastructure stocks built around businesses involved in the compute, networking and data backbone.
- Review shifting energy priorities by considering 19 nuclear energy infrastructure stocks filled with infrastructure plays that could matter if investment into nuclear capacity continues building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com