
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Custom Chips And Nuclear Power Change Amazon Stock Narrative
- Amazon.com has entered a multiyear agreement worth over US$1b with Synopsys for advanced chip design technology and signed a 20-year nuclear power deal with Constellation to secure 690 megawatts of long term, carbon free electricity for its data and AI infrastructure.
- The combination of custom semiconductor spending and contracted nuclear power locks in two of the biggest inputs for AWS scale: computing performance and energy reliability, which directly affects Amazon.com’s cost base and capacity planning for AI workloads.
- The next area of focus will be how Amazon.com’s investment narrative around AI driven AWS growth intersects with these custom chip and nuclear power commitments.
Amazon.com Investment Narrative Recap
To own Amazon.com, you need to believe its heavy spending on AWS, AI infrastructure, and logistics will keep translating into higher quality earnings over time, even as capital needs stay high. In the short term, the key issue remains AWS execution under rising investment demands. The Rock Tavern strike puts a spotlight on safety, labor practices, and potential cost pressure but does not look like a core earnings driver by itself right now.
The bigger risk is that layers of labor disputes, legal actions on returns and marketplace rules, and higher fulfillment spend combine to squeeze margins just as capital expenditures for AI ramp up. If those issues escalate or replicate across more sites, they could weigh on Amazon.com’s flexibility to keep committing resources to long-duration projects such as custom chips and nuclear power deals.
Set the Rock Tavern strike next to Amazon’s September commitment to invest another US$1.9 billion into its Delivery Service Partner program in 2027 and more than US$543 million in delivery safety since 2022. The contrast is sharp. On one side, warehouse workers allege unsafe speeds and ignored complaints. On the other, delivery contractors see rising pay and more safety technology.
For you as an investor, that mismatch matters. Capital is flowing into AI data centers, custom silicon, and last mile networks, which supports the AWS and logistics catalysts. At the same time, unresolved warehouse issues and large settlements around return policies and marketplace conduct add to the regulatory and labor risk stack that could chip away at the operating leverage narrative if they become more widespread.
Amazon.com's narrative assumes revenues of US$1,152.4b and earnings of US$158.3b by 2029, with analysts building in 14.1% yearly top line growth and an earnings increase of about US$23b from US$135.3b today.
Uncover why Amazon.com's fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
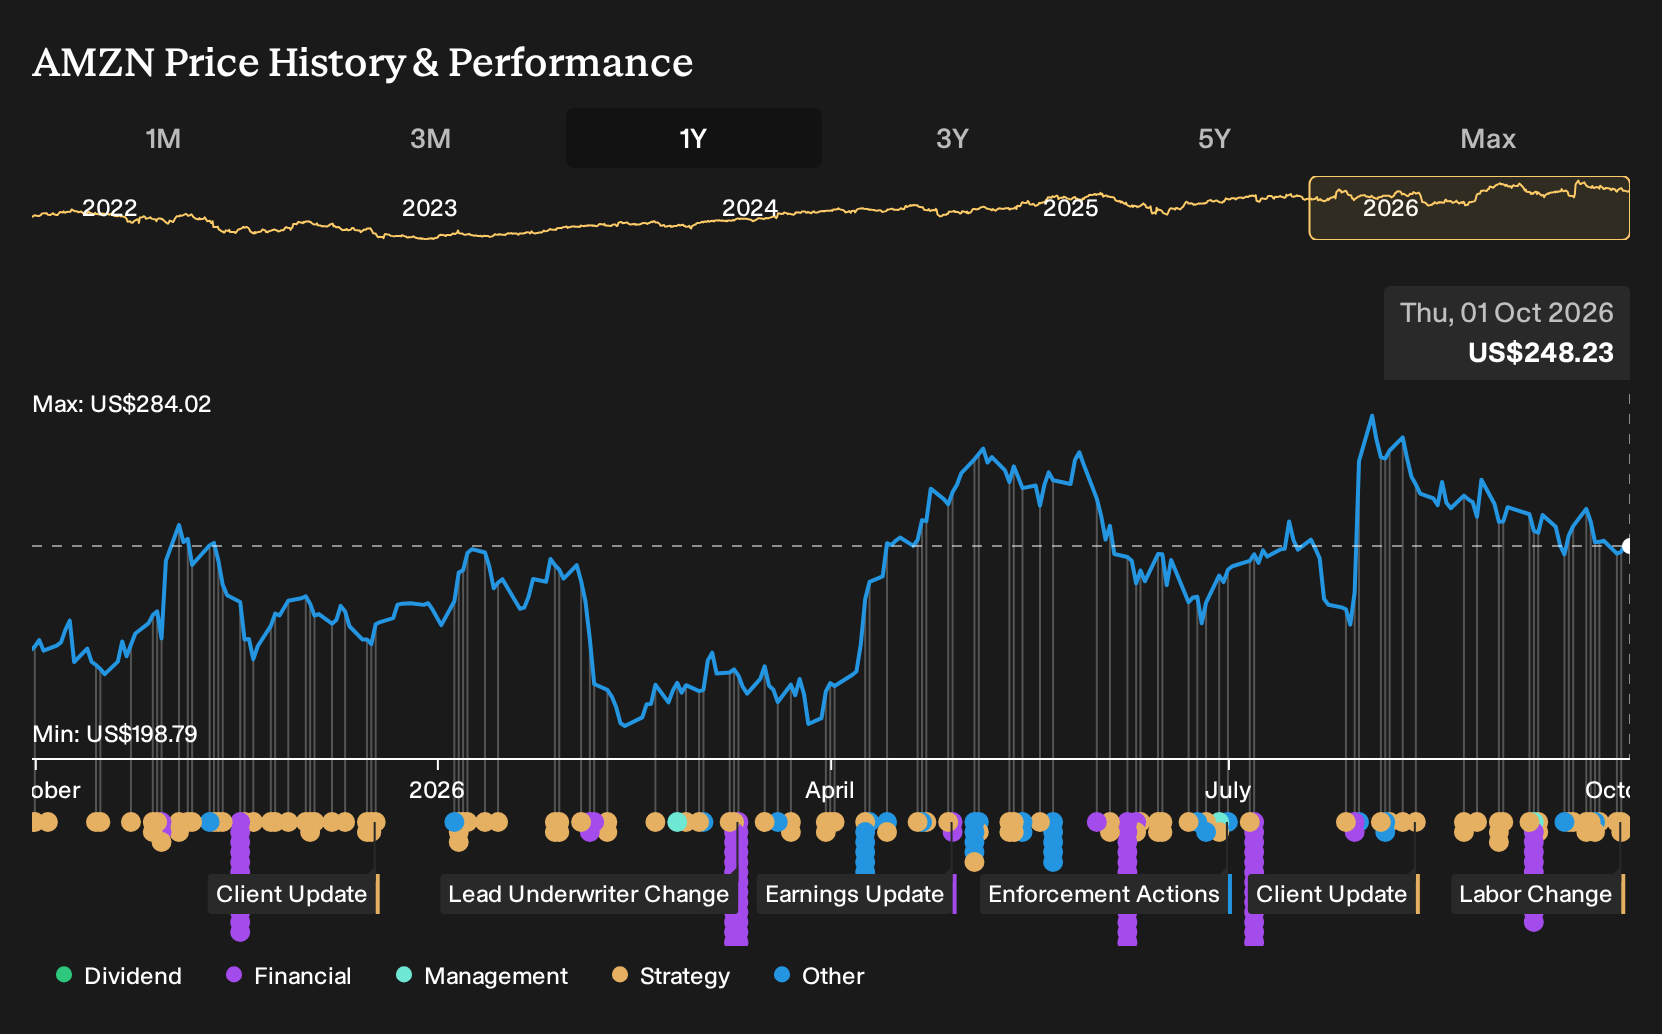
The 44 fair value estimates from the Simply Wall St Community cluster between about US$257 and US$475 per share, with a long tail of very optimistic forecasts. That spread tells you opinions on Amazon.com differ sharply. Set those expectations against ongoing labor disputes, significant AI and AWS capital needs, and legal settlements. Then decide which camp you lean toward and explore the full range of views.
Explore 43 other Amazon.com fair value estimates, including one that suggests as much as 91% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amazon.com research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amazon.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amazon.com's overall financial health at a glance.
Looking for more investment ideas beyond Amazon.com?
Once you have a view on Amazon.com, it can help to compare that thesis with other listed businesses that have very different risk and return profiles. The Simply Wall St Screener lets you quickly filter for specific qualities so you can build a watchlist that fits your own goals rather than leaning on a single stock.
- If you want potential growth with strict financial discipline, scan through a 31 resilient stocks with low risk scores that keep volatility and balance sheet risk in check.
- For investors who care about cash returns, use the screener focused on income to review 7 dividend fortresses that may suit a yield oriented portfolio.
- When you are hunting for mispriced quality, widen your opportunity set with a 19 high quality undiscovered gems that are not widely followed but still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com