
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Keyera (TSX:KEY) Earnings Beat
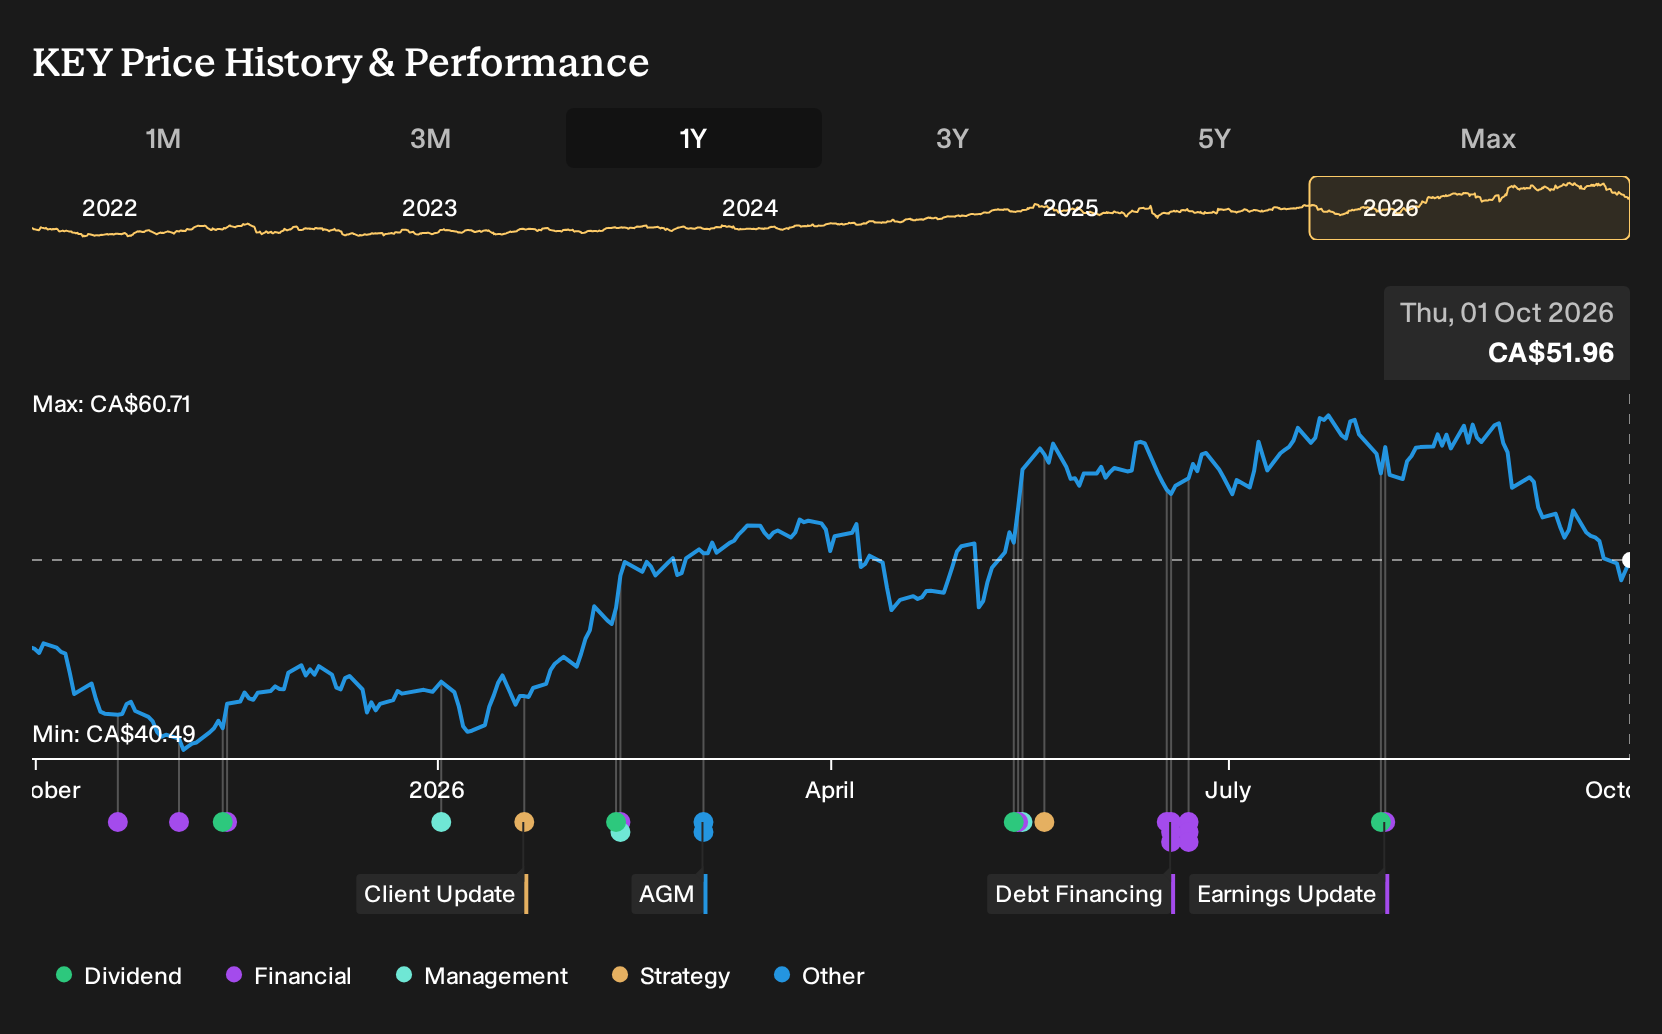
- Keyera recently reported its Q2 FY26 results, with earnings per share coming in above analyst estimates from its natural gas and NGL focused operations in Canada and the United States.
- The earnings beat highlights how Keyera’s integrated gathering, processing, and liquids infrastructure platform can influence profitability across its three segments when volumes and contract structures align.
- We will now look at how Keyera's investment narrative might be affected by this earnings beat on its recent quarterly results.
Scan how Keyera’s earnings surprise compares with other infrastructure and energy plays by reviewing our hand picked list of solid balance sheet and fundamentals (7 results) that are now benefiting from stronger balance sheets and resilient cash generation.
Keyera Investment Narrative Recap
For an investor in Keyera, the core belief is that its integrated natural gas and NGL network in Canada and the United States can keep earning solid fees as volumes move through gathering, processing, storage, and marketing. The recent Q2 FY26 EPS beat supports that view in the near term, but it does not erase the bigger questions around margin pressure, interest coverage, and dividend funding.
Right now, the key short term catalyst is execution on volume growth and utilization across the three segments, as LNG and petrochemical demand filters into the system. The main risk is that heavy exposure to the Western Canadian Sedimentary Basin, combined with intense competition and integration demands from prior NGL acquisitions, limits how much of that opportunity actually drops to the bottom line.
Given the lack of fresh deal announcements tied directly to this quarter, the most relevant backdrop for the earnings surprise remains the earlier acquisition of Plains' Canadian NGL business. That transaction increased Keyera's scale and connectivity, so a strong quarter provides a live look at how well those extra assets are being run inside the broader platform.
If volumes from resource rich areas such as the Montney and Duvernay continue to move through the expanded network, and if long term fee style contracts remain the backbone, that earlier expansion stays central to the story. Any signs that integration risk, higher funding costs, or tougher competition are eroding returns on that larger asset base would quickly move from background issue to front line concern for shareholders focused on near term catalysts.
Keyera's current earnings of CA$361.4 million are set against analyst expectations for CA$990.4 million of earnings on CA$11.2b of revenue by 2029. This implies 15.9% yearly revenue growth and an earnings increase of about CA$629 million to reach that 2029 consensus level.
Uncover how Keyera's fair value points to a 24% potential upside to its current price before momentum traders close the gap.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community now stretch from about CA$64 to nearly CA$139 per share. This is a wide band for a single stock like Keyera. That spread sits alongside integration risk around the Plains NGL deal and basin concentration, so you are seeing sharply different opinions. Explore those alternatives before anchoring on any one narrative.
Explore 2 other Keyera fair value estimates, including one that suggests upside of as much as 167% from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Keyera research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Keyera. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keyera's overall financial health at a glance.
Looking for more investment ideas beyond Keyera?
If this Keyera update has sharpened your thinking, you can build on that momentum by scanning a wider watchlist using the Simply Wall St Screener. Broaden your opportunity set so one earnings print never becomes your only reference point.
- For investors who want potential upside without moving away from quality, review a curated mix of attractively priced businesses through the 5 high quality undervalued stocks.
- If stability and income are higher on your checklist, focus on companies with stronger yield profiles by examining the 1 dividend fortresses.
- When capital preservation comes first, consider reducing left tail risk by starting with the 9 resilient stocks with low risk scores as a shortlist of sturdier options.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com