
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ACM Research (ACMR) Could Be 27% Below Fair Value Following Backlog Growth
Event backdrop and why ACM Research is on the radar
ACM Research (ACMR) has drawn fresh attention after its Shanghai subsidiary reported an 88.2% year-over-year backlog increase and flagged upcoming nine month financial results, putting demand trends and earnings expectations in sharper focus.
Recent buying interest has been strong, with ACM Research’s share price up 3.29% over the last day, 9.71% over the past week and 19.33% across 30 days, even though the 90 day share price return is down 14.51%. That short term momentum sits on top of an 86.23% year to date share price return and a 1 year total shareholder return of 92.94%. Meanwhile, the 3 year total shareholder return of about 4x and 5 year total shareholder return of 118.66% show how the stock has already rewarded investors who stayed the course as new orders, backlogs and investor events such as the upcoming CEO Investor Summit 2026 periodically reset expectations.
Scan beyond ACM Research and explore other semiconductor equipment stocks that are showing strong order books and backlog momentum using the curated 19 high quality undiscovered gems.
After a near doubling over 12 months and a sharp recent bounce, the real question on ACM Research is simple: Are you looking at early innings of upside, or a story where most of the rerating already happened?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, ACM Research screens as undervalued, with a fair value estimate of $115.14 versus the last close at $83.58. That view leans heavily on how its China footprint and capacity build out feed into longer term earnings power.
Localized semiconductor supply chains and production expansion in China, backed by favorable government policy and continued insulation from export restrictions, are enabling ACM to raise its China revenue target from $1.5B to $2.5B and overall long term revenue target to $4B, suggesting ACM will outpace industry revenue growth rates.
See why 91 investors see ACM Research as 27% undervalued.
Result: Fair Value of $115.14 (UNDERVALUED)
Still, the bullish ACM Research story leans heavily on China demand and relief from export controls, so any policy shock or weaker local spending could quickly test that 27% undervalued narrative.
Find out about the key risks to this ACM Research narrative.
Another View on ACM Research’s Valuation
The analyst narrative frames ACM Research as about 27% undervalued using future earnings and a P/E of 42.9x. A different lens tells a cooler story. The SWS DCF model estimates future cash flows at $53.71 per share, below the recent $83.58 price, which screens as overvalued. Which narrative feels closer to how you think ACM’s cash generation will actually play out?
Look into how the SWS DCF model arrives at its fair value.
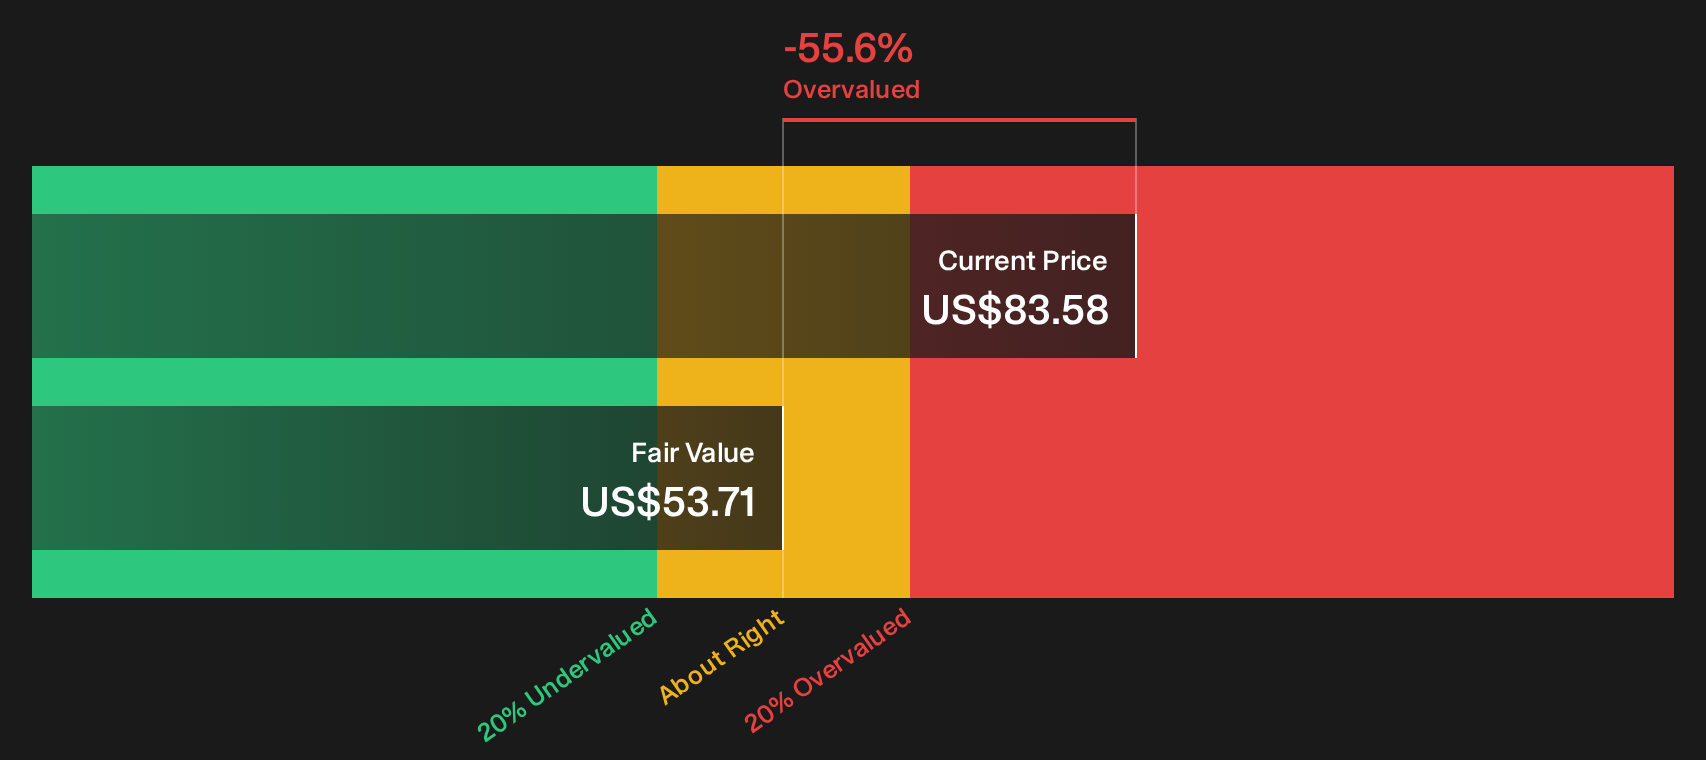
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ACM Research for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on ACM Research so far. If you think the clock is ticking and want to pressure test the bull and bear cases yourself, start with the 3 key rewards and 2 important warning signs.
Looking for more ACM Research style investment ideas?
If you stop at ACM Research, you risk missing other opportunities that fit your style. Put a few minutes aside and run them through a focused screener.
- Target robust portfolios by checking companies that combine quality fundamentals with appealing valuations using the 28 high quality undervalued stocks.
- Strengthen your downside protection by reviewing the 31 resilient stocks with low risk scores and zoom in on businesses with comparatively resilient risk profiles.
- Back long term compounding by scanning income focused opportunities through the 7 dividend fortresses before yields move away from you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com