
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Q3 Earnings Change The Bull Case For Capital One Stock (COF)?
- Capital One Financial recently rolled out a limited time perk package for existing Venture X Business cardholders, including up to $500 in Capital One Business Travel credits and a fourth night free at select hotels, tied to the card’s third anniversary.
- At the same time, investors are weighing this customer focused offer against weaker earnings per share, falling tangible book value per share, and return on equity that trails industry averages as the bank heads into its fiscal Q3 FY2026 report.
- We will look at how Capital One Financial's investment narrative is shaped by the upcoming Q3 earnings report and softer profitability.
Balance your view of Capital One Financial by scanning a curated set of resilient financials in our 31 resilient stocks with low risk scores before Q3 headlines start to move expectations.
Capital One Financial Investment Narrative Recap
To stay invested in Capital One Financial, you need to believe its heavy spend on technology, cards, and the Discover deal can outweigh weaker profitability metrics. The key near term swing factor is execution on earnings quality. Softer EPS, falling tangible book value per share, and sub industry return on equity keep pressure on management to show cleaner, more efficient profit.
The latest Venture X Business travel perks are a customer retention move, not a major earnings driver. They do little to shift the main near term risk, which is that elevated marketing, tech, and integration costs run ahead of revenue progress and further compress returns if Q3 comes in soft.
The Venture X Business travel credit and fourth night free offer is the clearest recent signal of how Capital One Financial is trying to deepen cardholder engagement. It leans into high spending small business customers, where the broader card and travel ecosystem, including Brex and in house travel tech, is meant to support more fee income over time.
For you as an investor, the relevance is about execution, not the headline perk. If perks like this keep valuable accounts active while the Discover integration and AI heavy fraud and servicing platforms scale, they can support volume and reduce churn. If reward intensity rises faster than spend and fee revenue, they risk adding to the already heavy marketing and operating expense load.
Capital One Financial's current analyst narrative points to US$79.6b in revenue and US$14.3b in earnings by 2029, based on forecast revenue growth of 18.3% a year and an earnings increase of about US$4.5b from US$9.8b today.
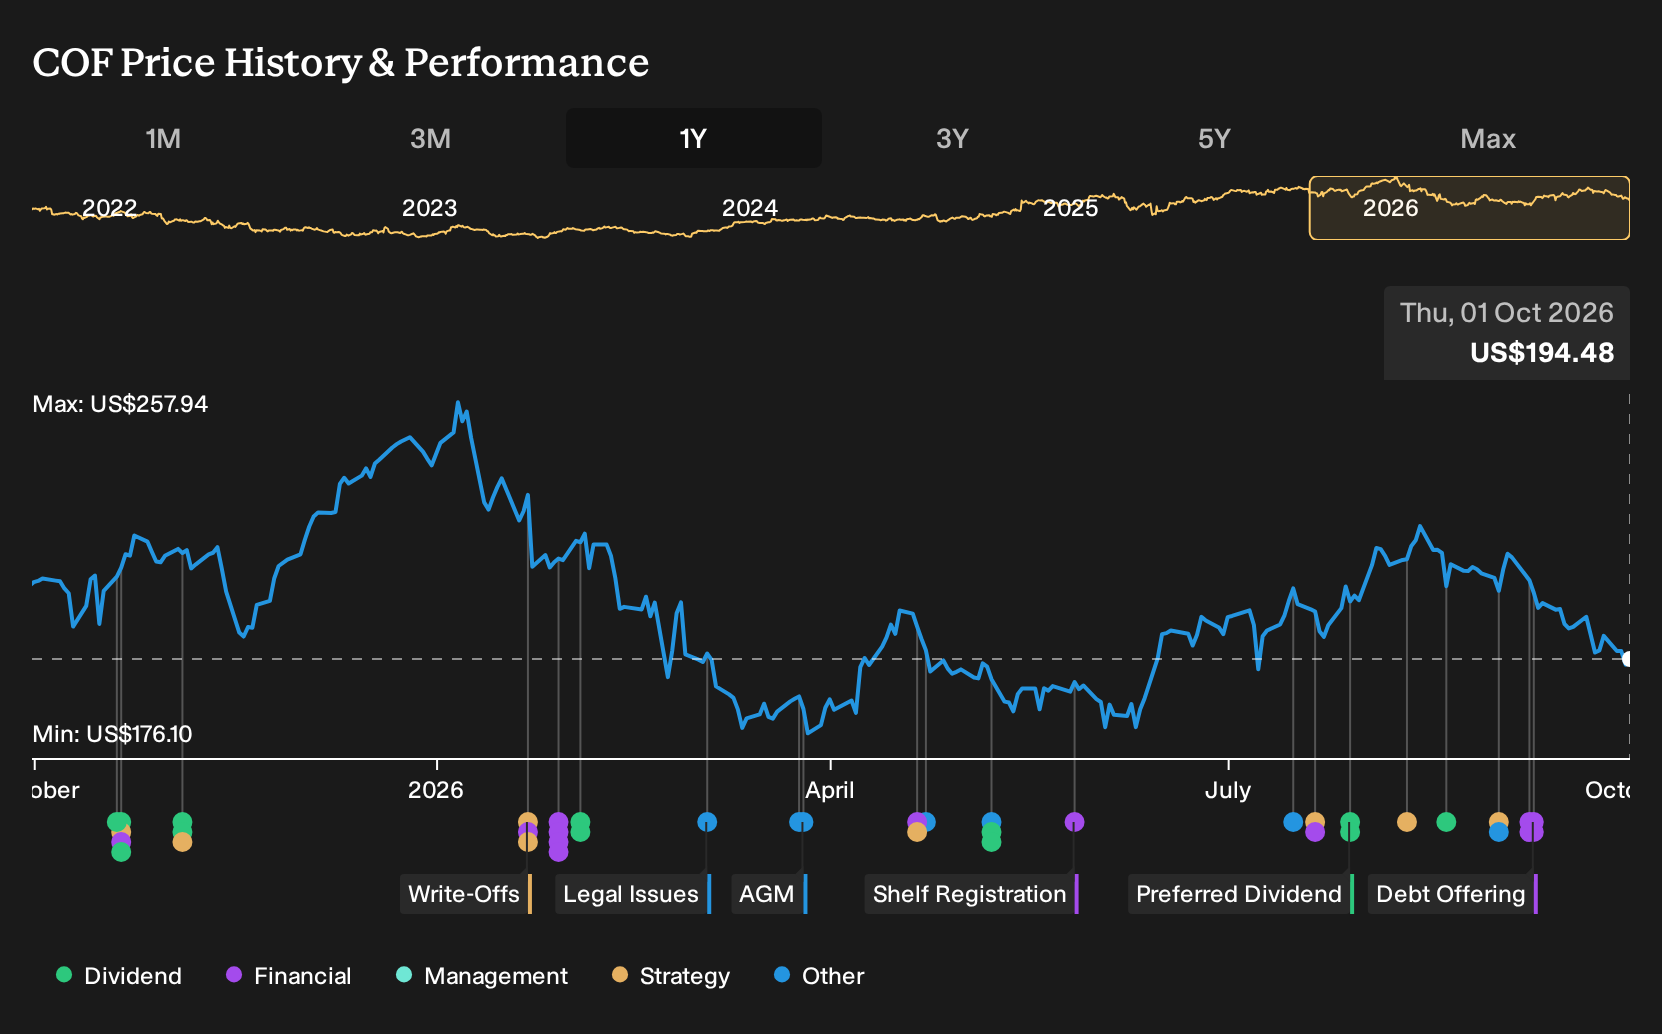
Uncover how Capital One Financial's fair value indicates a 33% potential upside to its current price before sentiment around Q3 results begins to shift expectations.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Capital One Financial’s earnings power after Discover and Brex are fully integrated, not on short term perks like the Venture X Business travel credits. They were pencilling in about US$79.3b of revenue and US$15.0b of earnings by 2029. Those forecasts came before this offer, so use them as one reference point while you explore how opinions and the narrative might shift from here.
Explore 4 other Capital One Financial fair value estimates, including one that suggests as much as 69% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Capital One Financial research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Capital One Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital One Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Capital One Financial?
If the Capital One Financial story leaves you wanting a broader watchlist, use the Simply Wall St screener to line up alternatives with different risk, income, and valuation profiles that fit your own approach.
- For investors who put downside protection first, scan a curated 31 resilient stocks with low risk scores that may help you focus on businesses with steadier risk profiles.
- If value is your priority, compare Capital One Financial with a 28 high quality undervalued stocks that combine stronger fundamentals with potentially more attractive pricing.
- For those building an income focused portfolio, look at a 7 dividend fortresses that concentrate on higher yielding payouts backed by solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com