
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What BioMarin Pharmaceutical (BMRN)'s AI Drug Discovery Deal Means For Shareholders
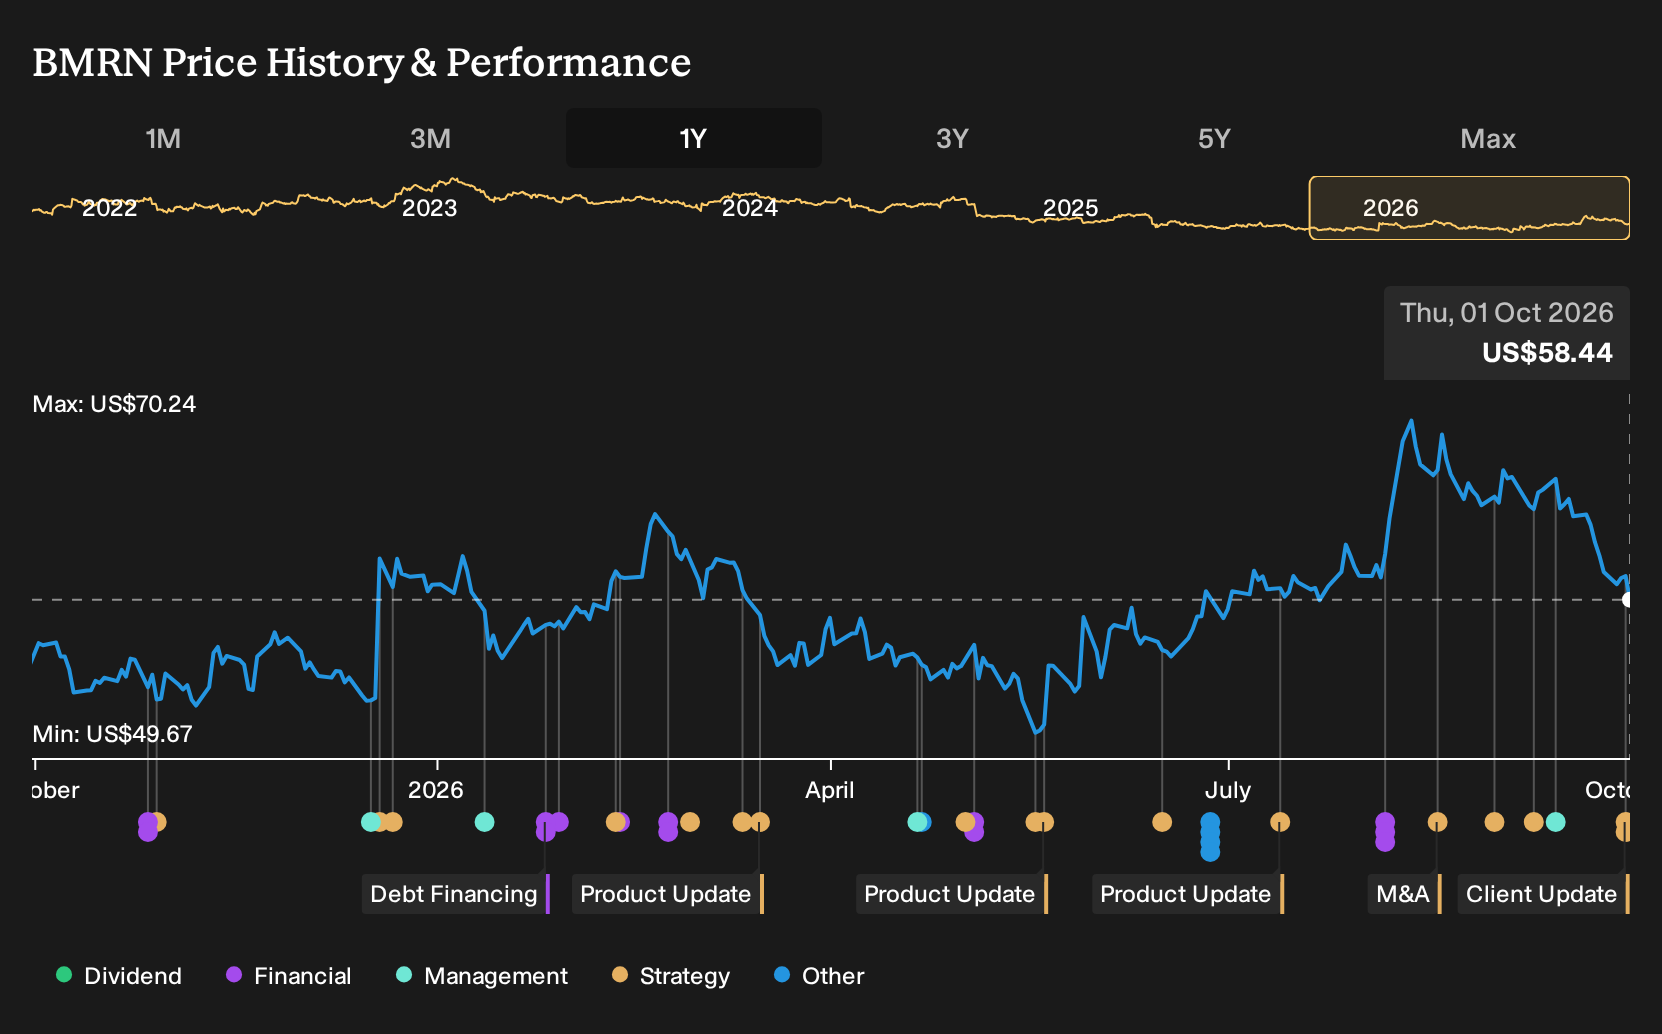
- In late September 2026, Profluent announced a collaboration with BioMarin Pharmaceutical to apply AI protein design models to identify novel enzyme therapy candidates. In the same period, BioMarin entered a global settlement and royalty-bearing patent license with Ascendis Pharma covering TransCon CNP and related products.
- The combination of AI enabled discovery support for BioMarin Pharmaceutical's enzyme pipeline and royalty income tied to Ascendis Pharma's CNP products may influence how future R&D productivity and non-product revenue contribute to the rare disease portfolio.
- This article reviews how BioMarin Pharmaceutical's investment narrative is affected by AI led drug design through the Profluent partnership.
Scan beyond BioMarin Pharmaceutical and this Profluent deal by reviewing hand picked rare disease and biotech peers in the 19 high quality undiscovered gems that could also be leveraging AI or licensing income pivots.
BioMarin Pharmaceutical Investment Narrative Recap
For a shareholder in BioMarin Pharmaceutical, the core belief is that a broad rare disease portfolio and newer assets like VOXZOGO, GALAFOLD and POMBILITI+OPFOLDA can eventually translate into stronger margins and better returns on capital. The recent AI collaboration and the Ascendis license mainly sit around the edges of that story, rather than reshaping the near term operating setup.
The key near term swing factor remains whether management can tighten costs and lift profitability from a 2.1% net margin while dealing with high debt and recent one off items. The main risk is that earnings and margin improvement do not materialise, leaving the business with weaker profitability than analysts expect at a time when the stock already embeds high growth assumptions.
The settlement and royalty bearing license with Ascendis around TransCon CNP looks most relevant for today’s debate on BioMarin Pharmaceutical. It converts an area of patent dispute into potential non product income tied to global sales of Yuviwel and related CNP products, while clearing litigation and removing some legal overhang around BioMarin’s skeletal growth franchise.
For catalysts, the agreement matters because it runs through May 2030 and could sit alongside VOXZOGO, BMN333 and potential label extensions as another way to monetise BioMarin Pharmaceutical’s work in skeletal conditions. The flip side is that execution risk on core therapies and acquisitions remains untouched, so investors still need to watch whether cost synergies, margin targets and free cash flow delivery track the ambitious expectations already embedded in forecasts.
BioMarin Pharmaceutical's current analyst storyline points to about US$5.1b of revenue and US$1.2b of earnings by 2029, built on an assumed 14.0% yearly increase in sales and an earnings move of roughly US$1.1b from about US$73.0m today to the 2029 consensus level.
Discover how BioMarin Pharmaceutical's fair value indicates a 57% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You could look at this news through a different lens. Bearish analysts focus on the risk that BioMarin Pharmaceutical becomes more dependent on royalties and a concentrated group of rare disease drugs. Before this update, the lowest forecasts were about US$4.8b of 2029 revenue and US$527.2m of earnings. Those expectations might shift in either direction as investors reassess the story.
Explore 3 other BioMarin Pharmaceutical fair value estimates, including one that suggests it could be worth just $91.62!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BioMarin Pharmaceutical research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BioMarin Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioMarin Pharmaceutical's overall financial health at a glance.
Looking For More Investment Ideas Beyond BioMarin Pharmaceutical?
If the BioMarin Pharmaceutical story has sharpened your thinking and you want to pressure test your thesis against other opportunities, the Simply Wall St Screener can help you quickly surface stocks that fit very different risk and return profiles.
- For investors who care most about resilience and capital preservation, consider starting with 31 resilient stocks with low risk scores that combine sturdier balance sheets with lower overall risk scores.
- If income is a priority, you can narrow the field to companies offering higher yields and more robust payout profiles through the 7 dividend fortresses that focus on 5%+ payments.
- For growth oriented readers who still want fundamentals to matter, there is also a 19 high quality undiscovered gems that highlights under the radar businesses with stronger quality markers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com