
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TSX Growth Companies With High Insider Ownership
In recent months, the Canadian equity markets have shown remarkable resilience despite global economic challenges, such as fluctuating oil prices and persistent inflation concerns. As investors navigate these turbulent times, focusing on growth companies with significant insider ownership can be a strategic approach, as it often indicates confidence in the company's long-term potential and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 20.8% |
| Electrovaya (TSX:ELVA) | 34.9% | 41.2% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Let's dive into some prime choices out of the screener.
Highlander Silver (TSX:HSLV)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Highlander Silver Corp. focuses on the acquisition, exploration, and evaluation of mineral properties in Peru and has a market capitalization of CA$1.52 billion.
Operations: Highlander Silver Corp. does not currently report any revenue segments.
Insider Ownership: 27.2%
Earnings Growth Forecast: 67% p.a.
Highlander Silver exhibits strong growth potential with insider ownership trends favoring substantial buying over selling in recent months. The company forecasts earnings growth of 67% annually, outpacing the Canadian market's 11.7%. Recent debt financing for the Corani Silver Project suggests robust development plans, supported by a US$330 million facility. Despite past shareholder dilution and a recent net loss of US$11.73 million in Q2, revenue is expected to grow at 46.8% per year, significantly above market averages.
- Get an in-depth perspective on Highlander Silver's performance by reading our analyst estimates report here.
- Insights from our recent valuation report point to the potential overvaluation of Highlander Silver shares in the market.

North American Construction Group (TSX:NOA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: North American Construction Group Ltd. offers mining and heavy civil construction services to the resource development and industrial construction sectors in Australia, Canada, and the United States, with a market cap of CA$461.30 million.
Operations: The company's revenue segments include CA$507.09 million from Heavy Equipment in Canada and CA$827.12 million from Heavy Equipment in Australia.
Insider Ownership: 10.7%
Earnings Growth Forecast: 28.2% p.a.
North American Construction Group is experiencing substantial insider buying, indicating confidence in its growth trajectory. The company forecasts significant earnings growth of 28.2% annually, outpacing the Canadian market's average. Recent executive changes with Brad Rogers as CEO may enhance strategic direction given his extensive industry experience. The firm's revenue guidance has been raised to between C$1.6 billion and C$1.8 billion for 2026, reflecting expansion efforts and increased equipment capacity at key mining sites in Canada’s north.
- Click here to discover the nuances of North American Construction Group with our detailed analytical future growth report.
- Insights from our recent valuation report point to the potential undervaluation of North American Construction Group shares in the market.
Propel Holdings (TSX:PRL)
Simply Wall St Growth Rating: ★★★★★☆
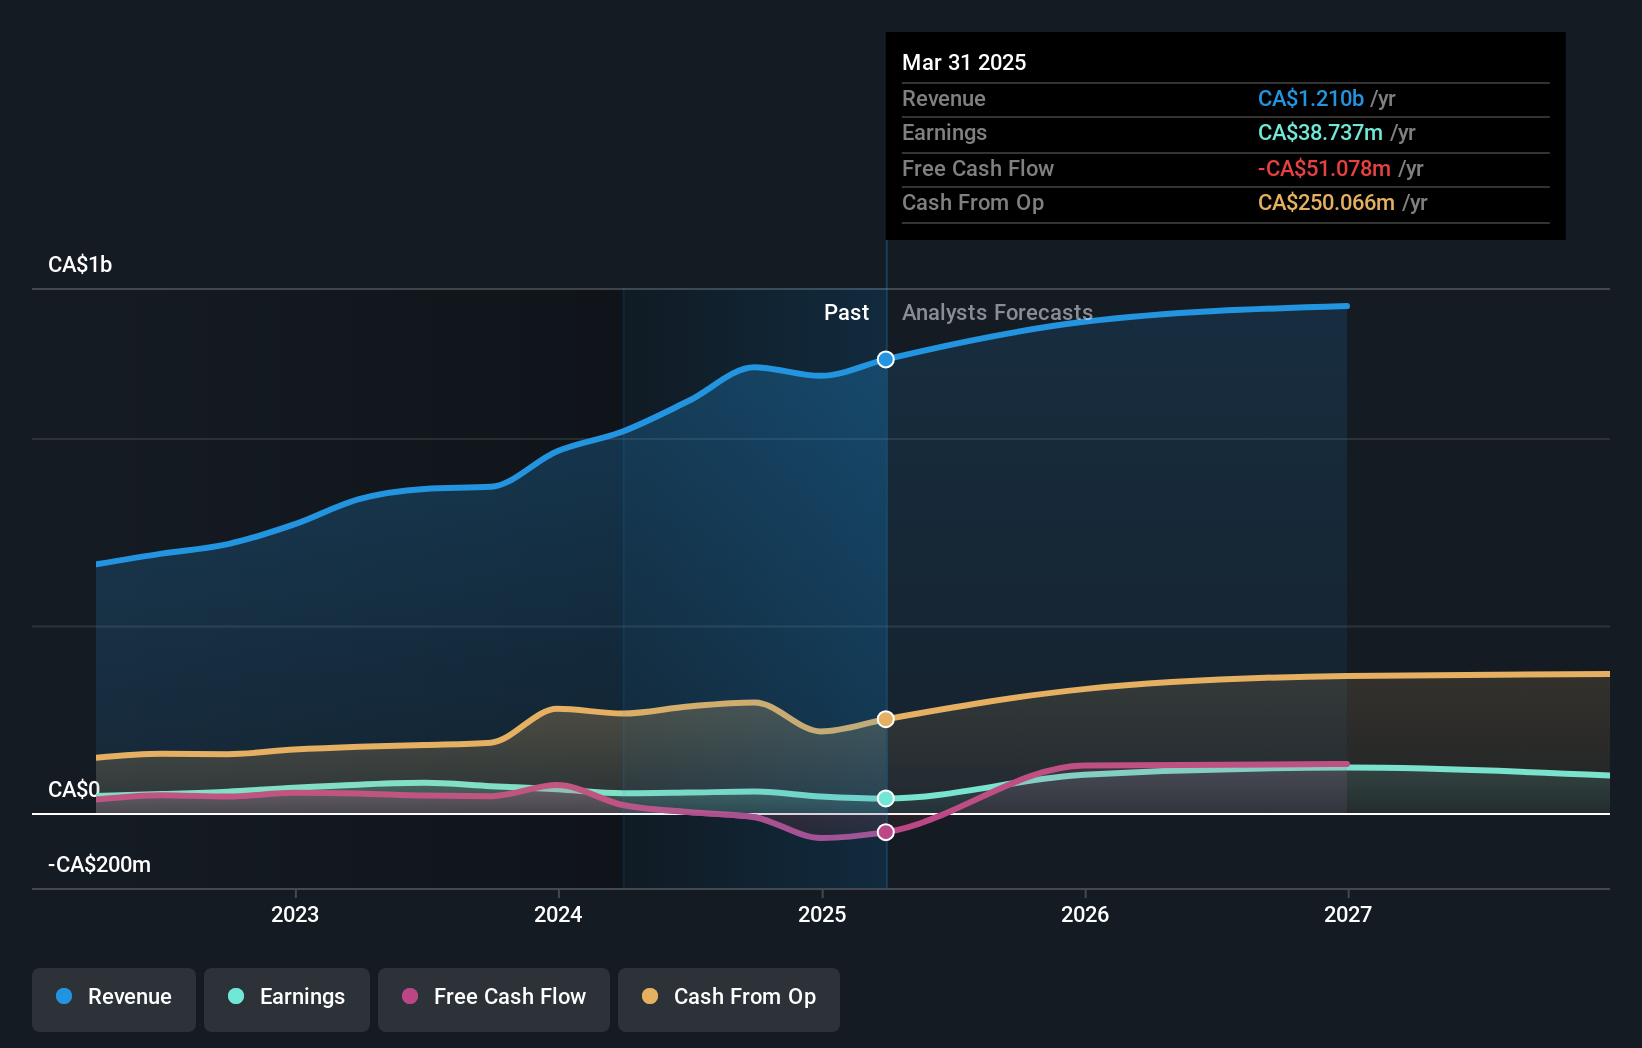
Overview: Propel Holdings Inc., along with its subsidiaries, operates as a financial technology company with a market cap of CA$989.37 million.
Operations: The company's revenue primarily comes from providing lending-related services to borrowers, banks, and other institutions, amounting to $653.59 million.
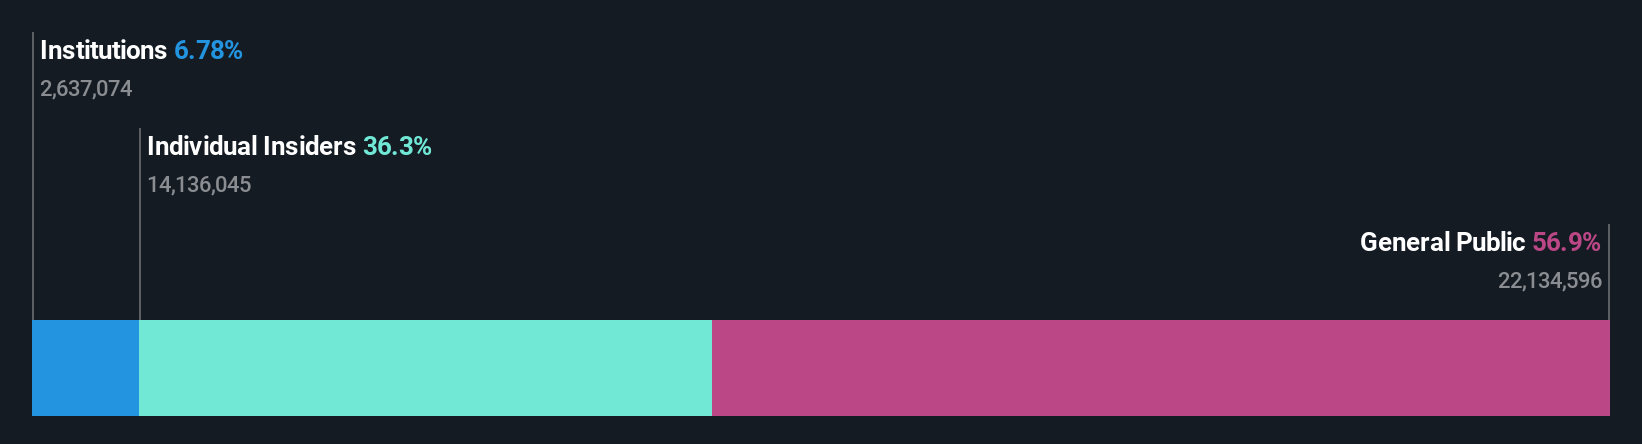
Insider Ownership: 25.7%
Earnings Growth Forecast: 39.7% p.a.
Propel Holdings exhibits strong growth potential, with revenue projected to grow 24.9% annually, outpacing the Canadian market. Earnings are expected to rise significantly by 39.7% per year. However, its dividend yield of 4.02% is not well covered by free cash flows, and debt coverage is a concern. Despite significant insider selling recently, the company reported increased Q2 earnings and announced its twelfth consecutive quarterly dividend increase to CAD 0.255 per share annually.
- Click to explore a detailed breakdown of our findings in Propel Holdings' earnings growth report.
- Our comprehensive valuation report raises the possibility that Propel Holdings is priced lower than what may be justified by its financials.
Taking Advantage
- Delve into our full catalog of 49 Fast Growing TSX Companies With High Insider Ownership here.
- Searching for a Fresh Perspective? Explore 25 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com