
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
General Motors (GM) Battery Push Puts Its Valuation Back In Focus
General Motors (GM) is back in focus after Ultium Cells, its joint venture with LG Energy Solution, outlined a US$1b upgrade to the Spring Hill battery plant to mass produce lithium manganese rich cells.
Recent trading has been choppy for General Motors, with the share price up 3.00% over the last day to US$79.31 but down 7.38% over the past 30 days and slightly lower year to date. At the same time, the 1 year total shareholder return of 34.76% and 3 year total shareholder return of about 1.7x indicate that longer term momentum has been strong. These figures continue to frame battery related announcements such as the Spring Hill upgrade and the closed loop recycling pilot as key signals for how investors are reassessing both growth potential and execution risk in GM's EV push.
Scan how General Motors fits into the wider EV supply chain story by comparing it to a curated 39 power grid technology and infrastructure stocks that are also tied to electrification and energy infrastructure.
General Motors now carries a strong recent shareholder return story alongside fresh EV investment headlines, so is the stock priced for execution risk, or does it still reflect a discount that the current numbers do not support?
Most Popular Narrative: 24% Undervalued
Against a last close of $79.31, the most followed narrative assigns General Motors a fair value of $104.22 using a 12.54% discount rate. This frames recent battery and software developments as central to the investment case.
The growing base of subscription and software enabled services, including roughly US$3b of expected high margin digital revenue in 2026 and a deferred revenue balance approaching US$7.5b, can increase recurring revenue and raise overall net margins as this mix expands.
See why 99 investors see General Motors as 24% undervalued.
Result: Fair Value of $104.22 (UNDERVALUED)
Still, the General Motors narrative could be knocked off course if quality issues escalate or if its limited hybrid presence results in it missing key pockets of demand.
Find out about the key risks to this General Motors narrative.
Another View: How General Motors Looks On P/E
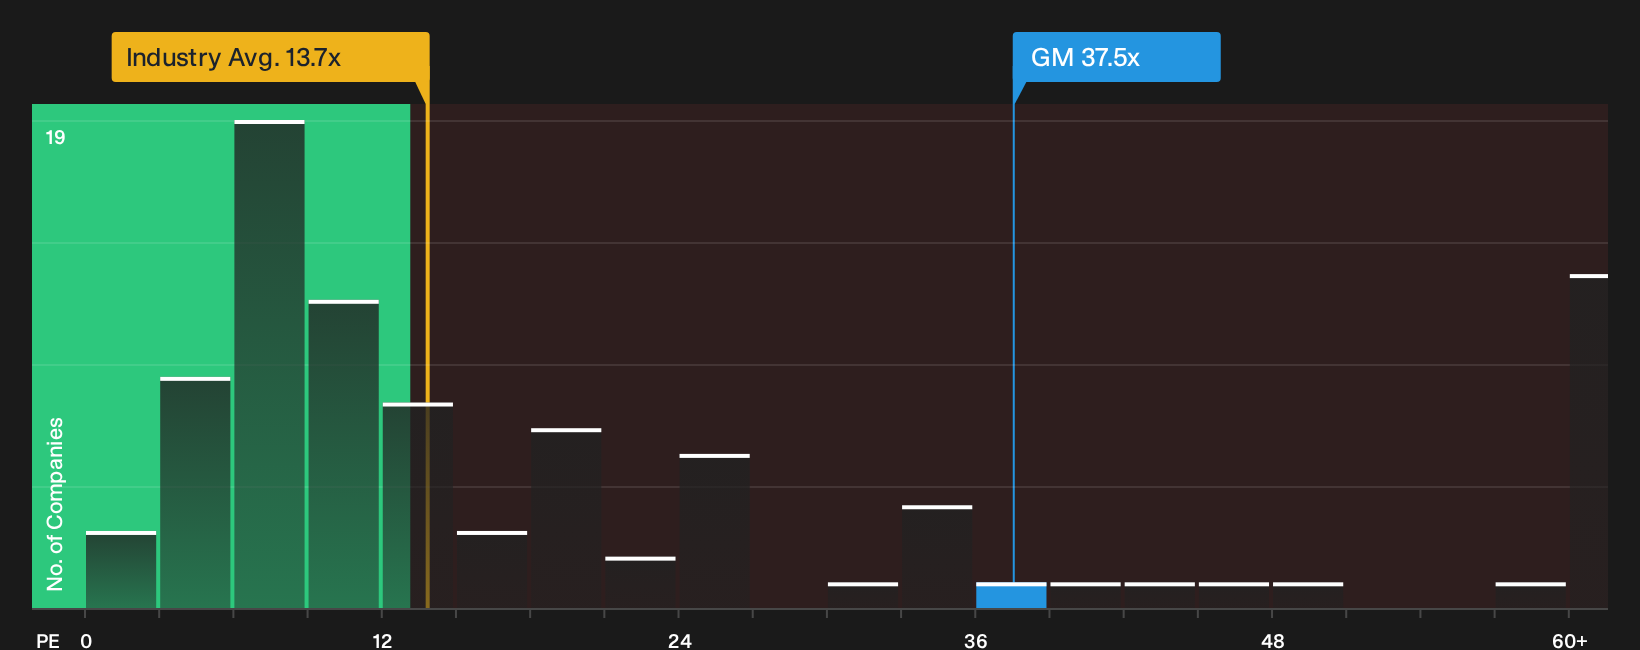
That SWS DCF model points to General Motors trading below an estimated future cash flow value of $137.58, yet the market is pricing the shares at a P/E of 37.5x. Both the US Auto industry on 13.7x and peers on 27.3x sit well lower, while the fair ratio is 24.3x. Is the market rewarding momentum, or just stretching the risk you are taking on earnings?
See what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around General Motors can feel messy, so move fast, test the data for yourself, and weigh both the upside and the pressure points. Start by lining up the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond General Motors?
If you want a fuller picture of opportunities around General Motors, it may help to widen your lens and compare it with other stocks that match your risk and return preferences.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio.
- Hunt for quality at a price that still looks reasonable by reviewing a focused 28 high quality undervalued stocks that filters for strong businesses on sensible metrics.
- Spot underfollowed opportunities early by running through a hand picked 19 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com