
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Uranium Energy (UEC) Stock Looks Fully Priced On Its 209% Run
Uranium Energy has been through a big shift in recent years, and the stock’s sharp moves now leave a simple question for investors who care about fundamentals. Is today’s share price really supported by what the company has built up on its balance sheet, especially its book value?
- Over the past 5 years the stock has returned 208.9%, which puts real pressure on the question of whether its current valuation can be grounded in underlying net assets.
- Recent news that Uranium Energy increased production, expanded into multiple mines and ended the latest reported period debt free with a sizeable pool of liquid assets can affect how much weight investors put on its equity base relative to future growth spending.
- There is a second opinion on Uranium Energy worth weighing. See what analysts think Uranium Energy's shares could be worth.
The issue now is whether Uranium Energy’s current market price lines up with its book value when set against the industry average.
To compare Uranium Energy with other opportunities that are built on balance sheet strength, start a fresh comparison using the solid balance sheet and fundamentals stocks screener (25 results).
Does Uranium Energy Look Pricey on Book Value?
P/B is a useful lens for Uranium Energy because investors are weighing a large pool of assets against a business that is still working toward consistent free cash flow.
The stock trades on a P/B of 3.4x, compared with an Oil and Gas industry average of about 1.5x and a similar 1.5x level for peers. That puts Uranium Energy at more than double the valuation investors are paying for the typical balance sheet in its sector, which points to an overvalued reading on this metric relative to asset backing alone.
Because the company recently reported sizeable liquid reserves and no debt, the market appears willing to pay a premium for that financial position and for its expanded uranium footprint. For you as a shareholder, the question is whether those qualities justify paying such a rich multiple versus other asset-heavy energy stocks that trade much closer to book value. Explore the numbers behind Uranium Energy's P/B valuation.
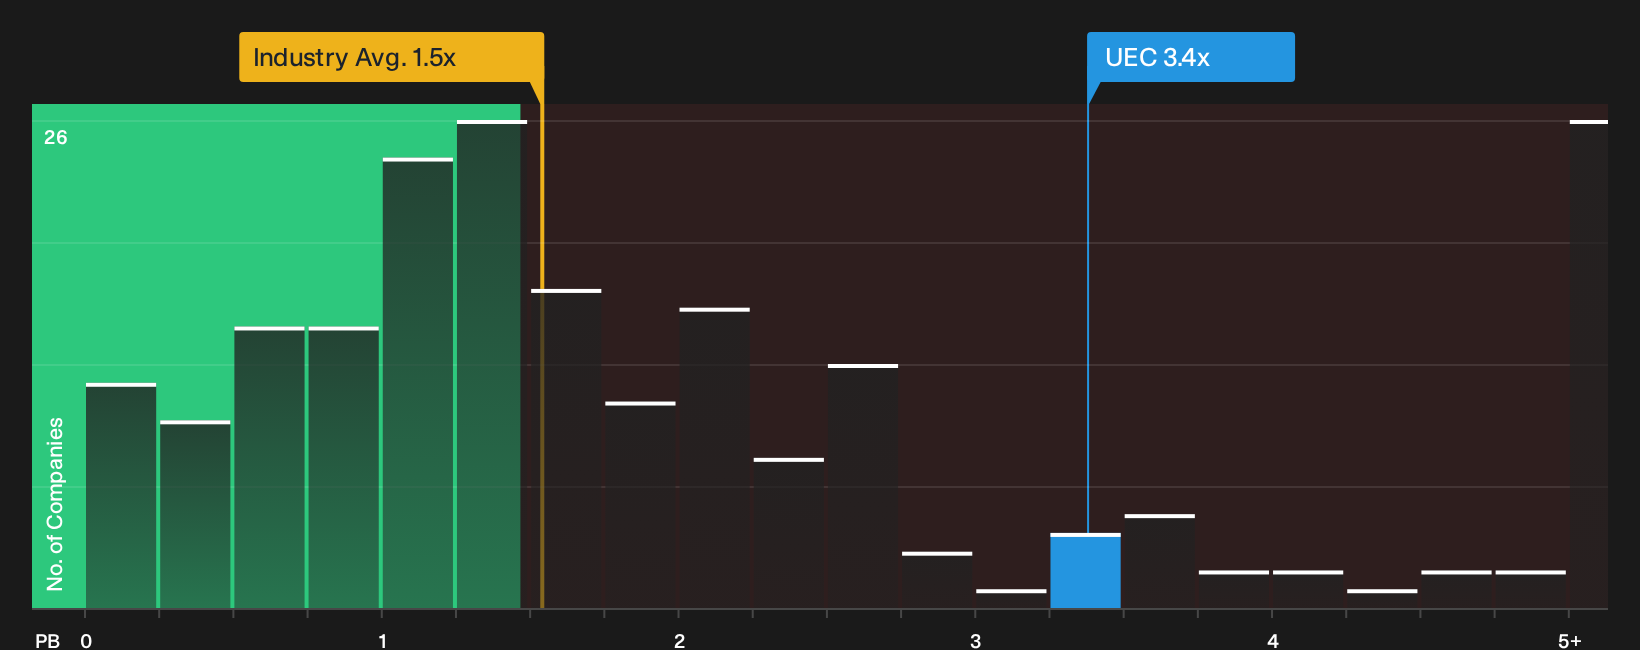
The Uranium Energy Narrative: What Would Justify Today's Price?
Narratives on Uranium Energy pick up where the book value question leaves off and explain what kind of future growth, profitability and earnings profile would need to unfold for the current P/B multiple to appear either stretched or conservative. Each narrative links its number to a clear view on how Uranium Energy's growth, margins and exposure to risks might develop, which you can revisit as new information is reported, and they are available on Simply Wall St's Community page.
One of the top community narratives on Uranium Energy: 44% undervalued
"Debt free balance sheet with approximately $698 million in cash, inventory and liquid assets and a growing low cost physical uranium inventory..."
Discover why this Narrative puts Uranium Energy at 44% undervalued.
One more Uranium Energy check that sits outside the balance sheet
Price and book tell only part of the story for Uranium Energy, because there is a separate lens that compares where the share trades today with where professional forecasts see the business in a few years. Explore where analysts expect Uranium Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com