
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Scorpio Tankers (STNG) Shares Climbed After Its Latest Update
Why Scorpio Tankers’ Newbuild Orders Matter Now
Scorpio Tankers (STNG) has committed to four newbuilding vessels, including two LR2 product tankers and two VLCCs, with deliveries scheduled across 2028 and 2029. This decision will influence the company’s future fleet capacity and long term capital needs.
Recent trading has been strong, with Scorpio Tankers’ share price delivering a 7.76% 1 month return and a 17.50% 3 month share price return. The 1 year total shareholder return of 56.13% and 5 year total shareholder return above 4x suggest momentum has been building over both shorter and longer horizons as investors weigh the newbuild program alongside earlier capital moves such as the late September shelf registration.
Scan beyond Scorpio Tankers and see how other shipping and energy carriers with strong recent momentum compare using our curated 28 high quality undervalued stocks.
Scorpio Tankers trades below both intrinsic estimates and analyst targets, even after the newbuild news. Is that a sign of excessive caution, or a fair discount for heavier capital commitments ahead?
Most Popular Narrative: 13.5% Undervalued
Scorpio Tankers last closed at $85.79, while the most followed narrative sets fair value near $99.22. That gap sets up a debate between a low headline P/E and a story that leans heavily on fleet quality, balance sheet repair, and future earning power under a 9.03% discount rate.
Industry-wide fleet aging, together with stricter environmental regulations and limited new ordering activity, is constraining effective supply growth. Scorpio's young, fuel-efficient fleet stands to capture market share and command premium rates as older vessels lose utilization, thereby supporting net margins and sustained earnings growth.
See why 21 investors see Scorpio Tankers as 14% undervalued.
Analysts behind this fair value narrative expect revenue to decline by an average of 9.7% a year and earnings to fall by 45.3% a year over the next three years, yet still anchor on a higher valuation than the current share price. For that view to hold together, Scorpio Tankers would need to be earning about $244.0 million, or $6.59 per share, around June 2029 and trade on a future P/E of roughly 23x, compared with about 7x implied today.
That future multiple sits well above the current 13.1x P/E cited for the broader US Oil and Gas industry in the narrative. This means the story leans on Scorpio Tankers sustaining stronger earnings quality or capital returns than the average peer despite forecast declines in both revenue and margins from current levels. The same narrative also assumes profit margins step down from 48.4% to around 31.9%, so a lot of the heavy lifting in the fair value comes from what investors might be willing to pay for each dollar of earnings, not from growth in those dollars themselves.
For readers weighing that setup, the tension is straightforward. The market is applying a much lower P/E than the 23.3x embedded in the fair value, even though recent trailing metrics show high profitability, strong Return on Equity of 22.4%, and very strong 1 year earnings growth of 127.4% supported by at least one large one off gain. The narrative effectively argues that, after factoring in a 9.03% discount rate and steeper modeled declines in revenue and margins, Scorpio Tankers still deserves to trade closer to that higher earnings multiple over time.
Result: Fair Value of $99.22 (UNDERVALUED)
Still, if product tanker ordering accelerates toward overcapacity or regulatory pressure has a stronger impact on refined fuel demand, the Scorpio Tankers narrative could look very different.
Find out about the key risks to this Scorpio Tankers narrative.
Another View On Scorpio Tankers’ Valuation
While the fair value narrative leans on a future P/E of about 23x, Scorpio Tankers currently trades on roughly 4.8x earnings. That compares with a 12.3x average for the US Oil and Gas group and a fair ratio of 5x. This points to far less stretch in today’s price than the story implies. The question is whether investors should pay more attention to the discounted cash flow view or to these much lower current earnings multiples.
See what the numbers say about this price — find out in our valuation breakdown.
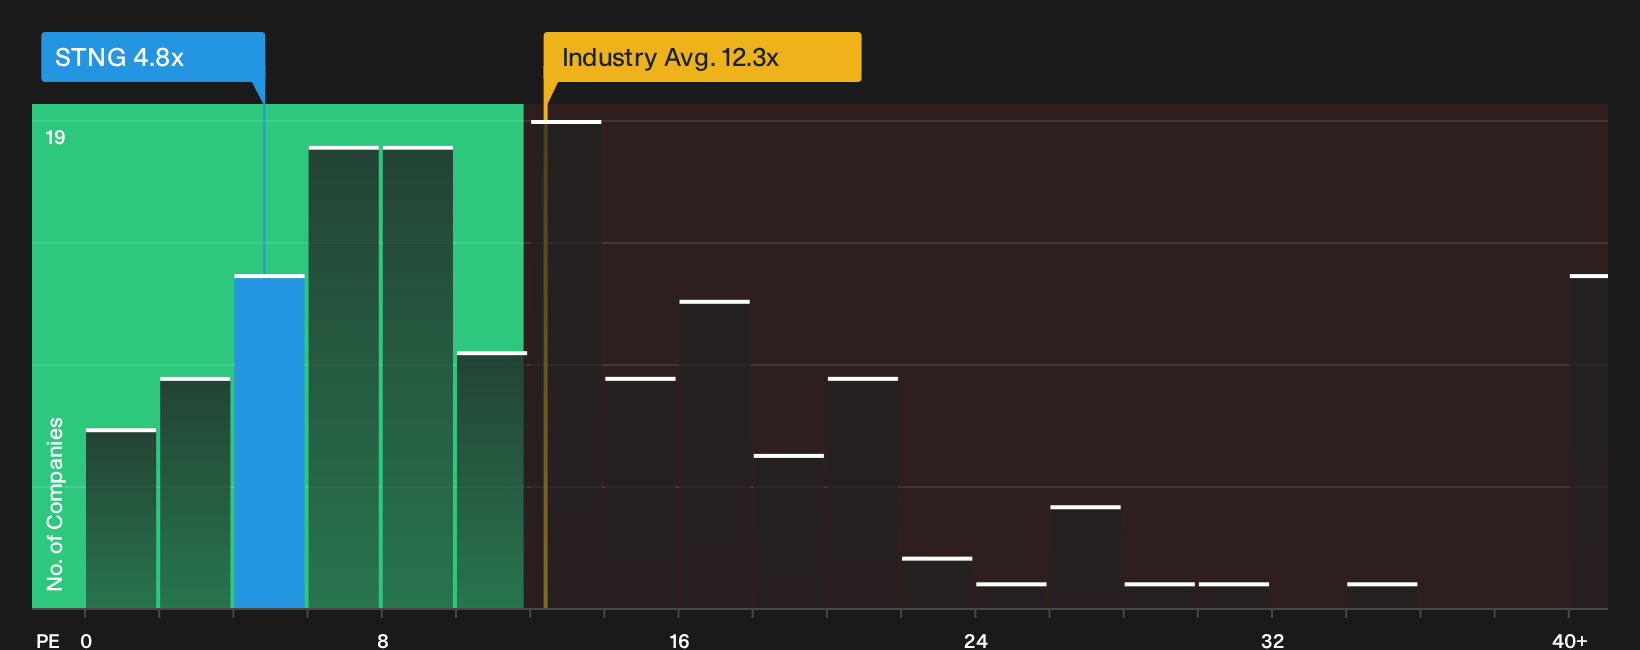
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scorpio Tankers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Scorpio Tankers is clearly mixed, with both caution and optimism in play. Move quickly, review the underlying data, and pressure test the key assumptions for yourself with 3 key rewards and 4 important warning signs
Looking For More Ideas Beyond Scorpio Tankers?
Do not stop with Scorpio Tankers. Use the Simply Wall St Screener to quickly surface fresh opportunities that fit your style before the crowd focuses on them.
- Hunt for potential bargains with stronger fundamentals by scanning our 28 high quality undervalued stocks, which is tailored to quality and pricing discipline.
- Explore potential income ideas by reviewing the 7 dividend fortresses that highlights higher yielding businesses.
- Strengthen your watchlist by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com