
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Record Quarter Might Change The Case For Investing In Kaiser Aluminum Stock (KALU)
- Kaiser Aluminum reported record net sales, conversion revenues, net income and adjusted EBITDA in the second quarter of 2026, supported by strong demand and pricing while continuing to work through cost and supply chain pressures.
- The company is focusing on efficiency measures, pricing discipline and capacity investments at facilities such as Trentwood and Warrick to manage costs and support a higher value product mix across aerospace and packaging.
- We will now look at how Kaiser Aluminum's reported financial results could influence the existing investment narrative built around margin recovery.
Scan how Kaiser Aluminum’s record-heavy quarter compares with other materials players pushing through cost and supply pressures by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) today.
Kaiser Aluminum Investment Narrative Recap
For Kaiser Aluminum, the core belief is that its aerospace, packaging and engineering exposure can support healthy conversion revenue, even while cost and supply chain pressures persist. The recent quarter showed record net sales, net income and adjusted EBITDA, which reinforces that the mills can run profitably under stress rather than resetting the story.
The near term catalyst remains execution at Trentwood and Warrick, as higher value coated packaging and aerospace plate volumes ramp. The biggest risk still sits with costs and leverage. Debt is not well covered by operating cash flow, so any setback in demand or pricing discipline could squeeze margins and limit flexibility quickly.
The most relevant update for this news is Kaiser Aluminum’s record second quarter of 2026, with all time highs in net sales, conversion revenues, net income and adjusted EBITDA. That result gives investors a fresh operational reference point while the business is still absorbing inflation, logistics issues and higher input costs.
For the catalyst path, this print links directly to the Trentwood Phase 7 and Warrick coated line build out. Strong earnings while those projects are still maturing suggests that the margin recovery thesis now rests less on a turnaround and more on sustaining mix, pricing discipline and efficiency gains, against the ongoing risk from debt and softer forecast earnings.
Kaiser Aluminum's current analyst narrative points to revenues of $4.4b and earnings of $202.2 million by 2029, based on an assumed 1.8% yearly revenue growth rate and a move from earnings today of $227.0 million. That profile reflects an expected earnings decrease of $24.8 million over the period, even as the business scales top line and positions around higher value aerospace and packaging volumes.
Uncover why Kaiser Aluminum's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
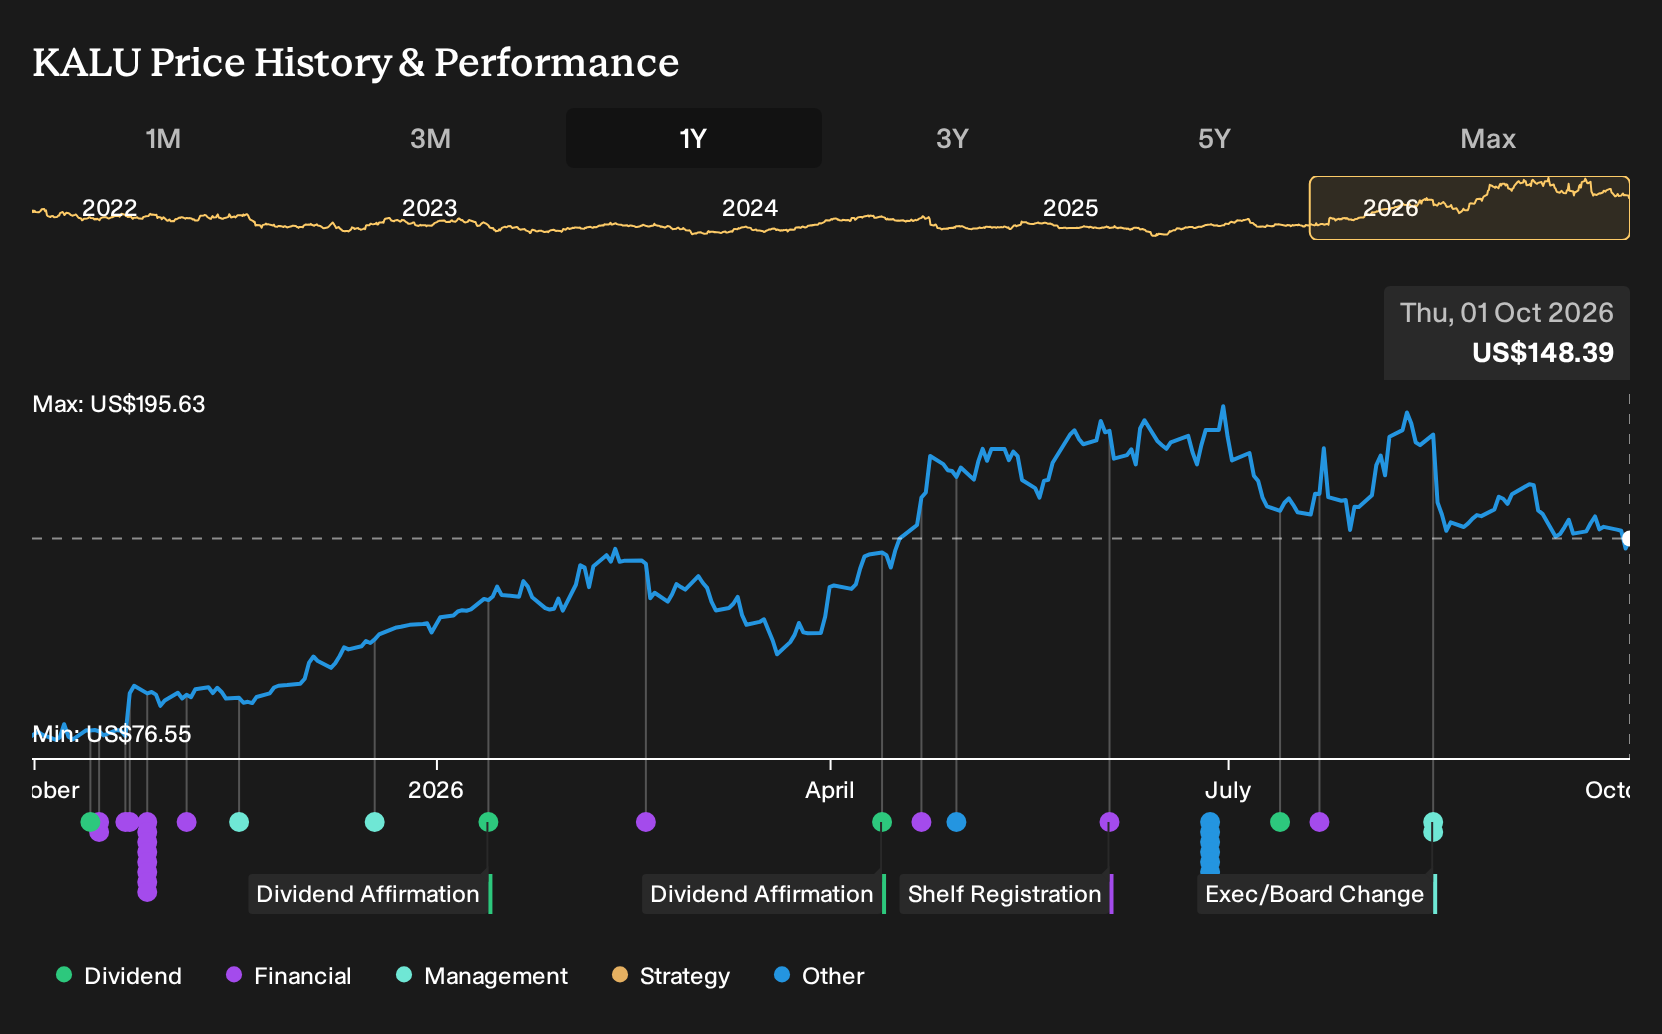
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Kaiser Aluminum’s Warrick coated packaging ramp as the real swing factor. Before this record quarter, they were pencilling in revenue of about $5.2b and earnings of $246.9 million by 2029. That is far above consensus, and this fresh result may challenge both camps.
Explore 2 other Kaiser Aluminum fair value estimates, including one that suggests up to 358% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kaiser Aluminum research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kaiser Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kaiser Aluminum's overall financial health at a glance.
Looking for more investment ideas beyond Kaiser Aluminum?
If Kaiser Aluminum has sharpened your focus on margins, balance sheets and long term earnings power, it can be useful to compare this thesis with other businesses that share similar qualities or offer a different risk profile entirely. The Simply Wall St Screener gives you a fast way to line up those alternatives side by side so you can pressure test your view before committing fresh capital.
- For investors who care most about quality at a reasonable price, scan a curated set of companies that combine strong fundamentals with appealing valuations through our 28 high quality undervalued stocks.
- If portfolio resilience is your priority, filter for businesses with sturdier finances and steadier risk profiles by checking the 31 resilient stocks with low risk scores.
- To widen the opportunity set and spot potential future compounders early, review a tight 19 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com