
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How FTSE All World Removal At Trimble Stock Has Changed Its Investment Story
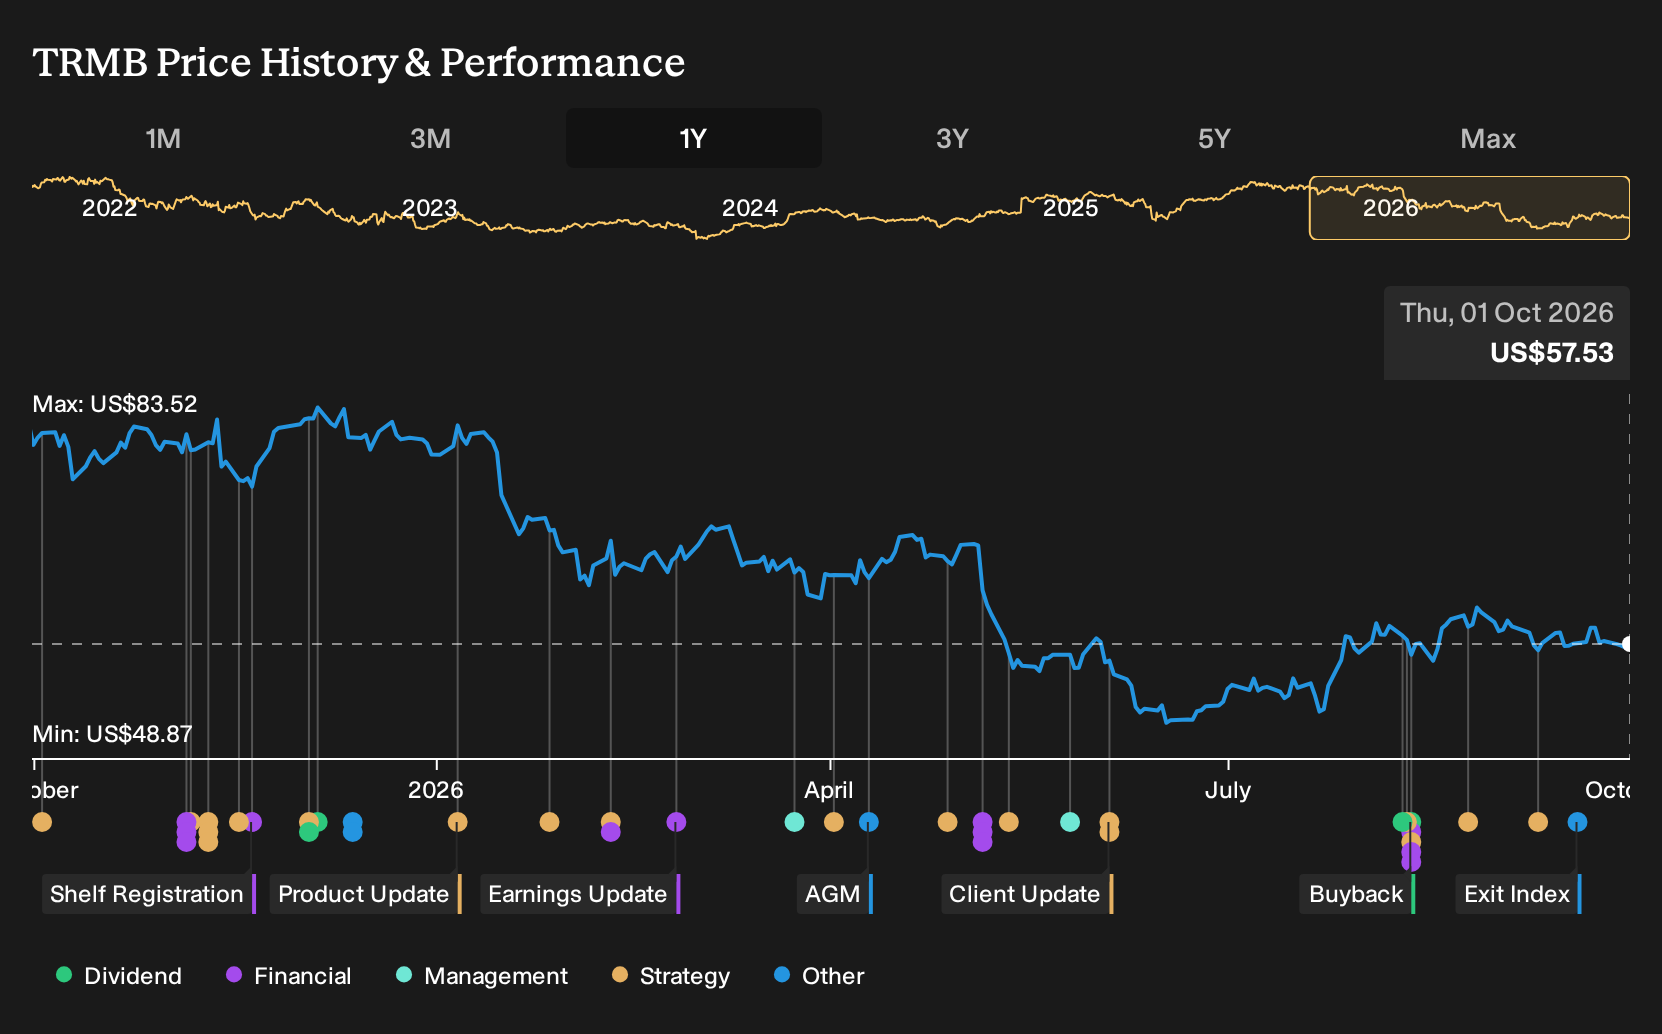
- Trimble Inc. was removed from the FTSE All-World Index in September 2026, a change that can influence how index tracking funds hold the stock and how the business is represented in global equity benchmarks.
- The index exit may shift the mix of Trimble’s shareholder base toward active investors who focus more on its recurring software revenue, AI enabled workflows and margin ambitions than on benchmark inclusion.
- The next area of focus is how Trimble’s investment narrative around recurring software, AI workflows and margins is affected by its index removal.
Compare Trimble’s shift out of the FTSE All-World with other potential breakout candidates by scanning our hand picked 19 high quality undiscovered gems that remain off most major benchmarks.
Trimble Investment Narrative Recap
To own Trimble, you need to believe the shift toward AI enabled, cloud workflows and high recurring software revenue can outweigh the drag from legacy hardware and transition projects. The recent FTSE All World removal looks more like a trading event than a hit to day to day operations, so it does not change that core thesis.
The near term swing factor is execution on subscription bundles and connected workflows across AECO, Field Systems and Transportation and Logistics while the business is still loss making at the net income line. The biggest risk remains operational, not index related, around governance control remediation and the Field Systems product transition weighing on ARR and profitability.
There are no fresh operational announcements directly tied to the FTSE decision, so the most relevant backdrop is Trimble's ongoing pivot toward roughly US$2.5b of ARR with a 79% software mix. That recurring base, plus raised guidance earlier in 2026, is what many active holders are likely to focus on when they reassess the stock after the index exit.
For you as a shareholder, the key question is whether that subscription engine, plus tools like Trimble Connect and AI powered construction workflows, can offset the drag from the Field Systems reset and the acknowledged control weaknesses targeted for 2027 remediation. Index removal may amplify volatility, but the real test is still day to day execution against those operational catalysts and risks.
Trimble's analyst narrative points to revenues of US$4.8b and earnings of US$1.6b by 2029, built on an assumed 7.9% yearly top line growth rate and a shift from a loss of US$104.7m today to that future profit. This represents roughly a 15x change in earnings.
Uncover why Trimble's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Trimble’s FTSE All World exit very differently. They lean heavily on the AI workflow catalyst, with prior forecasts built around about US$4.9b of revenue and US$1.6b of earnings by 2029. You can treat this as one possible path, knowing those pre news projections may shift as views evolve.
Explore 2 other Trimble fair value estimates, including one that suggests as much as 98% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Trimble research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trimble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trimble's overall financial health at a glance.
Looking For More Ideas Beyond Trimble?
If Trimble has you thinking more broadly about where to put fresh capital to work, it can help to line it up against a wider field of potential opportunities. The Simply Wall St Screener lets you do exactly that by filtering for the kind of balance sheets, income profiles, and risk levels that fit your own plan.
- If you want businesses that look financially sturdy first, then everything else second, start by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on resilience before returns.
- If income is your priority and you prefer cash in hand while you wait, narrow the universe to companies in our 7 dividend fortresses that meet a 5%+ yield hurdle.
- If you are hunting for potential bargains that still clear quality checks, filter for a 28 high quality undervalued stocks that combines fundamental strength with pricing that may not fully reflect it yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com