
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sanmina (SANM) Could Be 15% Below Fair Value As Growth And Buybacks Stay In Focus
Sanmina (SANM) is back in focus after robust recent revenue growth, solid profitability, and an active share buyback program drew fresh attention to the electronics manufacturing services specialist’s current valuation and market positioning.
Recent trading has been strong for Sanmina, with a 1 month share price return of 18.51% and a year to date share price gain of 39.34%. Total shareholder return over 1 year sits at 90.13% and at very large multiples over 3 and 5 years, pointing to momentum that has been building rather than fading as investors react to revenue growth, profitability and buybacks.
Scan how Sanmina’s momentum compares with other potential breakouts by running your filters through our curated list of 19 high quality undiscovered gems.
Sanmina now appears to be a high quality operator with increasing focus on its revenue growth, profitability and share buybacks. After this sharp rerating, does the current share price still represent a reasonable entry point for new investors?
Most Popular Narrative: 14.6% Undervalued
On the most widely followed view, Sanmina’s fair value of $260 sits above the latest close at $221.96, which puts the recent surge in context and frames the current debate around how durable its earnings story really is.
The imminent acquisition of ZT Systems is expected to add $5–6 billion of annual run-rate revenue, positioning Sanmina to double its net revenue within three years and capitalize on explosive growth in data center and AI infrastructure investment. This should provide a multi-year boost to overall revenue and EPS accretion from synergies and integration.
See why 17 investors see Sanmina as 15% undervalued.
Result: Fair Value of $260 (UNDERVALUED)
Still, Sanmina’s story can shift quickly if the planned ZT Systems acquisition places a drag on working capital or if any large client reduces orders materially.
Find out about the key risks to this Sanmina narrative.
Another View: SWS DCF Marks Sanmina As Overvalued
The analyst fair value of $260 paints Sanmina as 14.6% undervalued. A very different picture comes from the Simply Wall St DCF model, which estimates future cash flow value at $34.67 per share against the current $221.96 price. That points to a steep premium instead. Which story do you think is closer to reality?
For a closer look at how those future cash flows are modeled and discounted, review the Look into how the SWS DCF model arrives at its fair value..
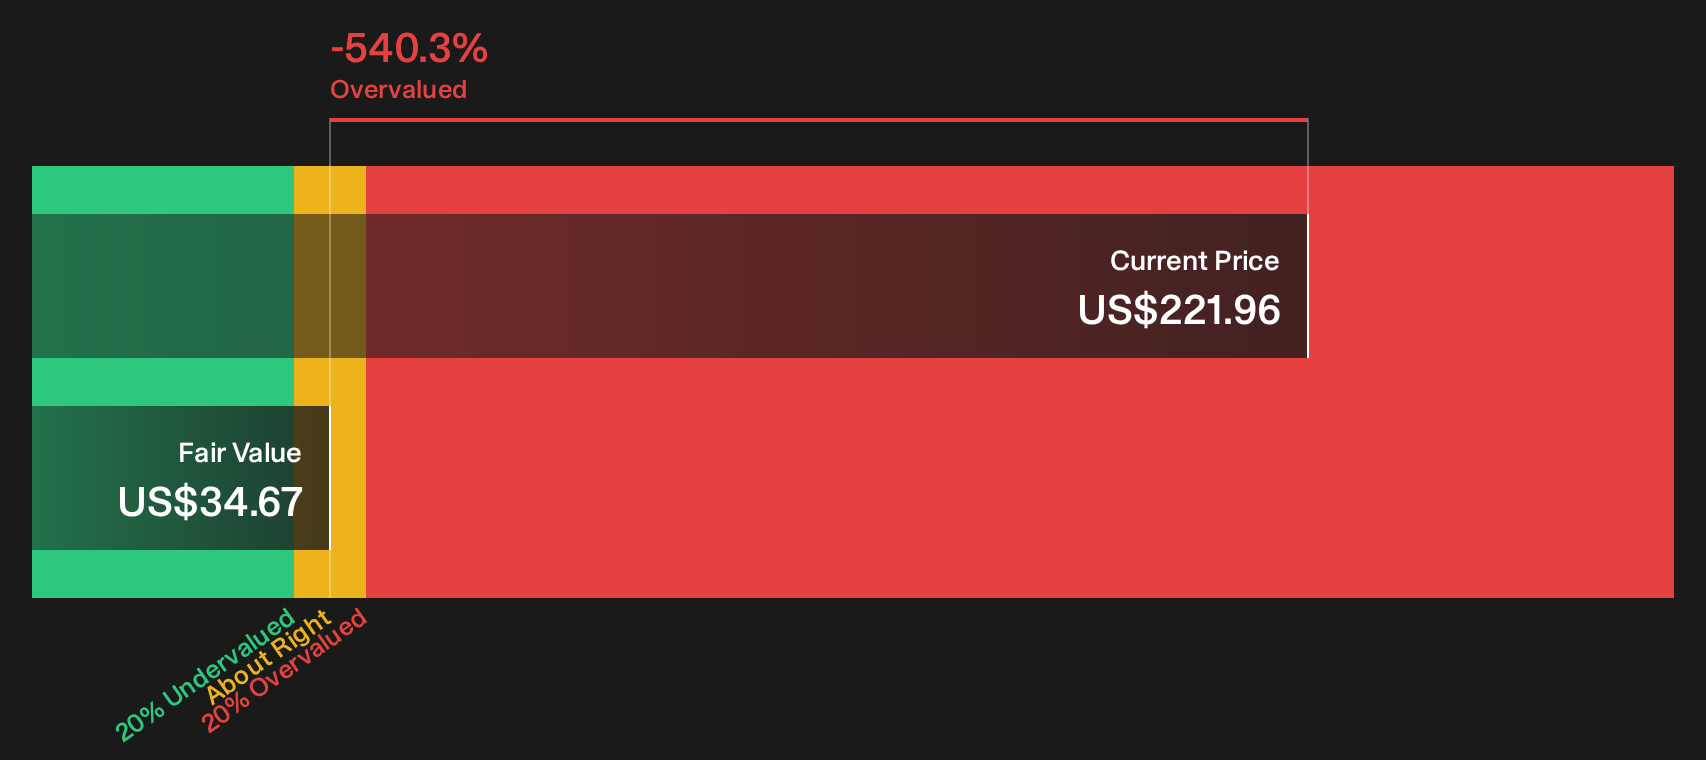
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanmina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sanmina is split, with clear positives and clear concerns sitting side by side. Consider moving quickly, testing the data yourself, and weighing both sides with the help of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sanmina?
If Sanmina has sharpened your focus, do not stop there. Fresh opportunities often show up first in the data, then in your portfolio returns.
- Target potential mispricings by scanning a curated pool of strong fundamentals through the 28 high quality undervalued stocks.
- Build resilience into your holdings by filtering for healthy financing and liquidity using the list of solid balance sheet and fundamentals (25 results).
- Focus on income-oriented opportunities by screening for recurring payouts with the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com