
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Shelf Stock Filing Require Action From Digital Turbine Stock Investors?
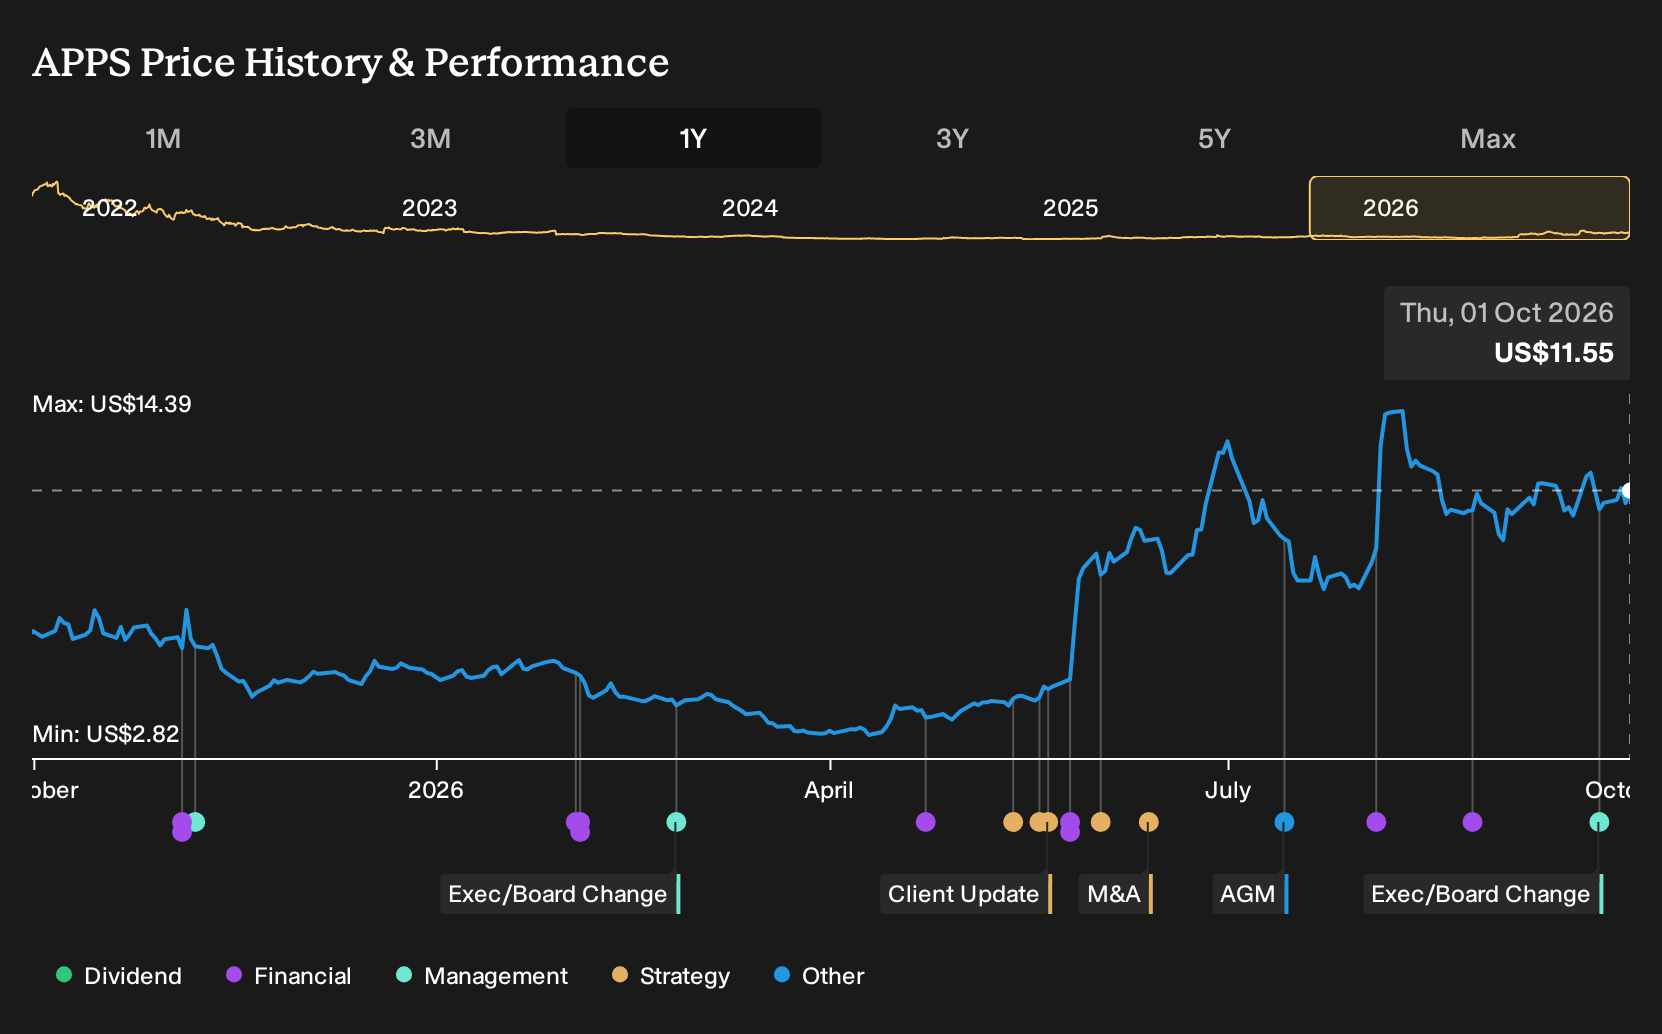
- Digital Turbine filed a shelf registration covering up to 1,222,418 common shares, with an aggregate value of about $7.9 million, and previously announced that its Chief Business Officer, Michael Akkerman, resigned in September 2026 effective October 30, 2026.
- The planned share availability, combined with senior commercial leadership turnover, points to management balancing capital flexibility with execution continuity across its mobile growth platform partnerships.
- We will now look at how Digital Turbine's investment narrative could shift in light of the new shelf registration filing.
Compare how Digital Turbine’s capital moves stack up against other mobile and tech platforms by scanning 19 high quality undiscovered gems that could be flying under most investors’ radar.
Digital Turbine Investment Narrative Recap
To own Digital Turbine, you need to buy into the idea that its mobile growth platform can stay relevant even as Apple and Google keep tightening control over app distribution. In the near term, the focus is on stabilising profit trends in an unprofitable business while keeping carrier and OEM relationships productive. The new shelf registration itself does not materially change that operating picture.
Your biggest swing factor in the short run remains execution on the On Device Solutions and App Growth Platform segments, which together generated about US$600.3 million of revenue. The key risk is still operational. Any stumbles on data, privacy, or partner renewals would likely matter more than this relatively small US$7.9 million shelf capacity.
The shelf registration stands out as the announcement most tied to today’s discussion. It covers up to 1,222,418 Digital Turbine common shares, with an indicated value of about US$7.9 million. That is a modest amount against a roughly US$1.3b market value, so it appears more like a tool for flexibility than a transformational event.
For you as a shareholder, the practical question is how any future use of that shelf interacts with already volatile trading and an unprofitable earnings profile. Potential issuance could slightly dilute per share metrics. The trade off is that extra funding capacity might support execution on the mobile platform, which is where the real catalysts and risks still sit.
What The New Shelf Means Against Consensus Expectations
Digital Turbine's narrative projects US$842.3 million revenue and US$14.9 million earnings by 2029. This implies analysts are assuming 12.0% yearly top line growth and an earnings swing of about US$49.9 million, from a US$35.0 million loss today to that US$14.9 million profit.
Uncover how Digital Turbine's fair value indicates a 49% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
For a different angle on Digital Turbine, focus on the bullish catalyst that open app distribution could expand its addressable market. The most optimistic analysts were pencilling in about US$861.3 million of revenue and US$125.5 million of earnings by 2029. That is far above consensus and shows how sharply opinions might shift after the shelf filing and leadership change.
Explore 4 other Digital Turbine fair value estimates, including one that suggests as much as 103% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Digital Turbine research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Digital Turbine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Digital Turbine's overall financial health at a glance.
Looking For More Investment Ideas Beyond Digital Turbine?
If the Digital Turbine story has sharpened your thinking about risk, cash flows, and execution, it can be useful to compare it with other companies that fit different profiles on the Simply Wall St Screener.
- For investors hunting for value with quality fundamentals, review a curated 28 high quality undervalued stocks that combine stronger balance sheets with healthier cash generation.
- If capital preservation is front of mind, narrow your search to a 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- For those who care most about resilience and financial footing, scan a list of solid balance sheet and fundamentals (25 results) to see which businesses might offer a sturdier foundation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com