
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Methanex (TSX:MX) Look Overvalued After Its 55% Run?
Methanex has had a strong run over the past year, and the question for you now is whether a share price around $83 puts too much or too little weight on what the business is currently earning. Heavy exposure to global methanol pricing and recent balance sheet moves both feed into the same issue: how much of its earnings power is already reflected in that valuation.
- The stock has gained 54.6% over the past year, which raises the question of whether recent earnings strength already explains that move or if expectations have started to stretch beyond the current profit base.
- Recent news around record adjusted EBITDA and the decision to redeem US$300 million of senior notes signals that cash generation and leverage may support a different earnings profile than investors had been assuming.
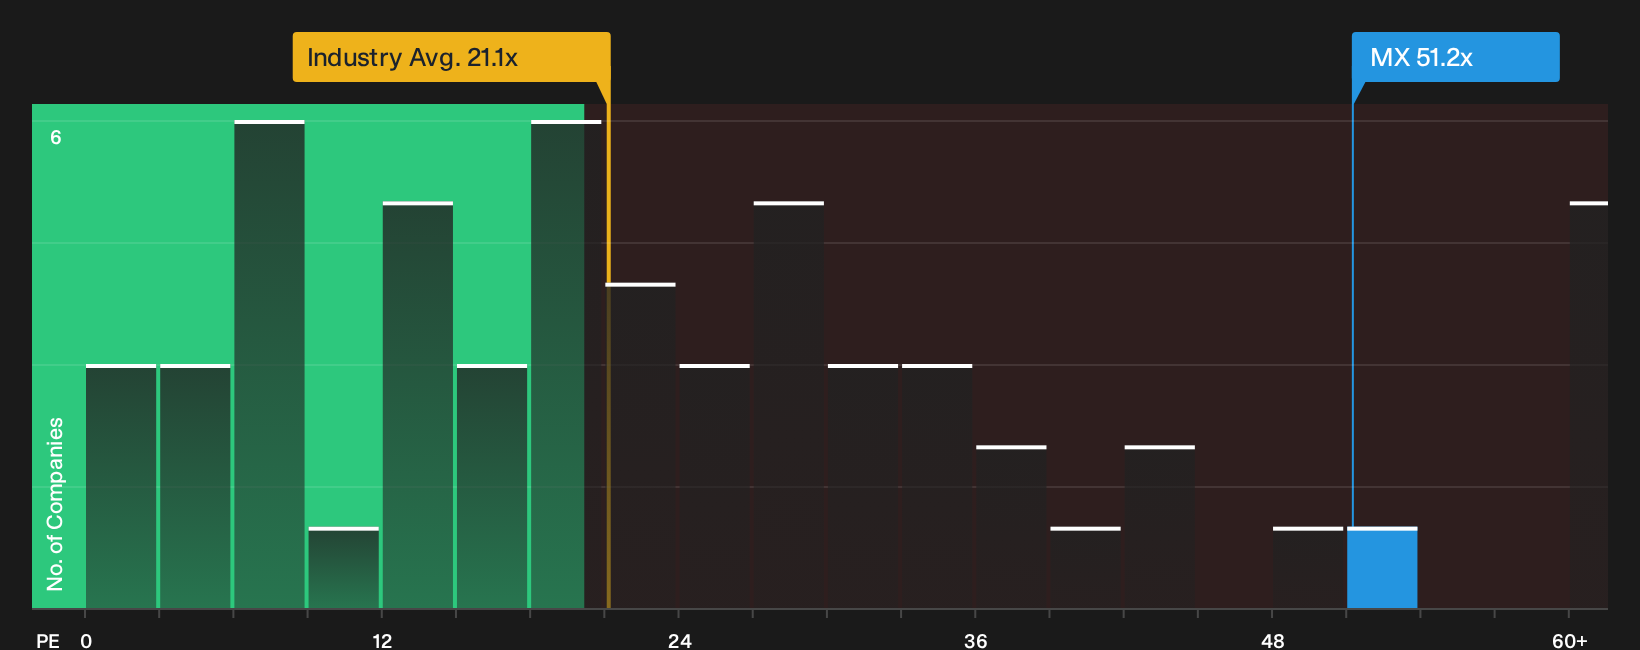
- Methanex's multiple only means something next to the competition. See how Methanex's 51.2x P/E compares with its peers.
The issue now is whether Methanex's current share price is adequately grounded in its earnings, once those profits are set against the Fair Ratio benchmark.
If you want a second reference point while you assess Methanex against its Fair Ratio benchmark, you can also run the same earnings lens over 5 high quality undervalued stocks.
Does Methanex Look Pricey on Earnings?
The P/E ratio is a useful way to assess Methanex because earnings remain the main lens investors use to judge a commodity producer that can generate substantial free cash flow in strong pricing periods. On that metric, the stock trades on a P/E of 51.2x, which is higher than both the Chemicals industry average of 19.6x and the peer group at about 37.9x.
That leaves the current valuation above the level suggested by a Fair Ratio that blends Methanex specific growth profile, profitability, size and risk. Despite the lift from record adjusted EBITDA and the US$300 million bond redemption, the market is assigning a richer multiple than this tailored benchmark would indicate. For you as a shareholder or potential buyer, the key question is whether the methanol exposure, balance sheet moves and cash generation justify paying a P/E that already appears to price in more than the benchmark implies is warranted. Explore the numbers behind Methanex's P/E valuation.
The Methanex Narrative: What Would Justify Today's Price?
Narratives on Methanex pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to unfold for the current P/E to look either too rich or too conservative, and they sit on Simply Wall St's Community page. Each scenario ties a fair value estimate to a distinct view of Methanex's possible catalysts and risks, so you can track over time which storyline is coming through in the actual results.
One of the top community narratives on Methanex: 9% undervalued
"The OCI acquisition expands capacity and market reach, improving earnings and operational efficiency while deleveraging strengthens financial stability…"
Discover why this Narrative puts Methanex at 9% undervalued.
Before You Act on Methanex’s Valuation, Look at Who Is Steering the Ship
Price, profits and balance sheet moves only tell part of the Methanex story, because the people making capital decisions and how they are rewarded can heavily shape what happens next. See who runs Methanex and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com