
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Choice Hotels International (CHH) Trading At A Discount After Its $130 Million Deal?
Choice Hotels International has been busy expanding its footprint, yet the share price is still down over the longer run, which naturally raises a question about how firmly today’s valuation rests on its earnings power. With the stock changing hands at about US$102.31, investors are asking whether the earnings behind that quote fully support it.
- The share price has fallen 20.5% over the past 5 years, which puts the spotlight on whether the current earnings multiple still makes sense after a weaker long term return.
- The planned US$130 million all cash purchase of Harvest Hosts may support future earnings if the RV and outdoor travel business scales well inside Choice Hotels’ asset light model, but it also commits capital that could otherwise have been used for other purposes.
- The analysts covering Choice Hotels International have run their own numbers. See what analysts think Choice Hotels International's shares could be worth.
The stock’s next move may depend on whether Choice Hotels International’s current earnings are strong and dependable enough to justify the price investors are paying today.
If you are weighing Choice Hotels International against other opportunities tied to earnings power and business quality, it can help to compare it with companies in the solid balance sheet and fundamentals stocks screener (25 results).
Is Choice Hotels International Still Cheap on Earnings?
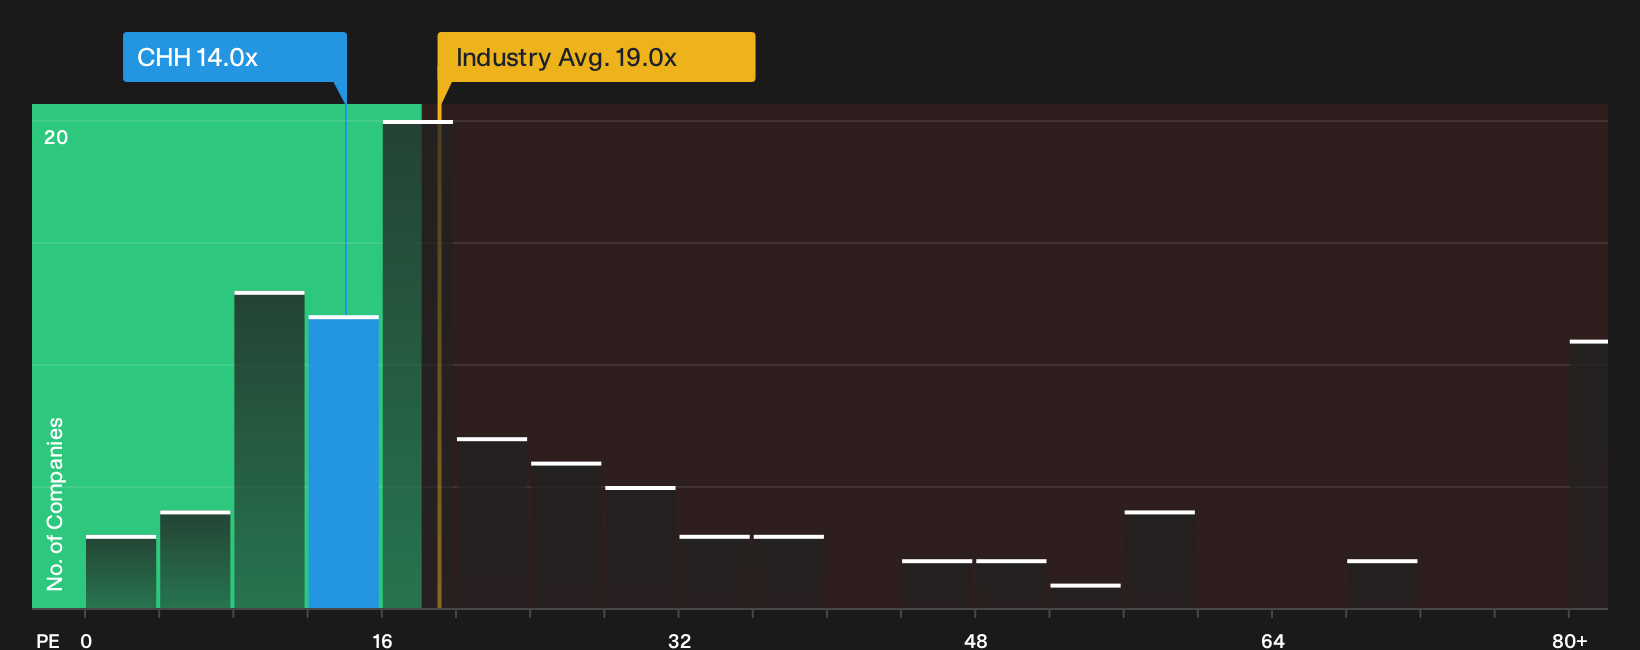
The P/E ratio is a useful lens for Choice Hotels International because earnings are a key focus for an asset light hotel group. On current figures, the stock trades at about 14.0x earnings, which is well below the hospitality industry average of 19.0x and far under the peer group near 57.4x. That is a wide gap for a business that still leans on fee based cash flows from franchising rather than heavy owned real estate.
The fair multiple implied by a model that weighs Choice Hotels International’s margins, growth profile, size and risk sits above the current 14.0x. This suggests the shares screen as undervalued on this earnings yardstick. Because the recent Harvest Hosts acquisition adds a new RV and outdoor travel stream at a time when the market is assigning a relatively low P/E, the current price tags that optionality at a modest level compared with both sector and tailored fair value benchmarks. Explore the numbers behind Choice Hotels International's P/E valuation.
The Choice Hotels International Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E discussion leaves off by explaining which future paths for Choice Hotels International's growth, margins, and earnings would need to occur for the current share price to appear high, low, or roughly fair. Each scenario sets out its own assumptions rather than relying on a single model output, so you can track those expectations against Choice Hotels International's reported results over time on Simply Wall St's Community page.
One of the top community narratives on Choice Hotels International: 9% undervalued
"Ongoing investment in digital platforms, guest mobile/online experiences, and the enhanced Choice Privileges loyalty program directly boost customer acquisition, retention, and direct bookings..."
Discover why this Narrative puts Choice Hotels International at 9% undervalued.
The share price is only one piece of the Choice Hotels International puzzle
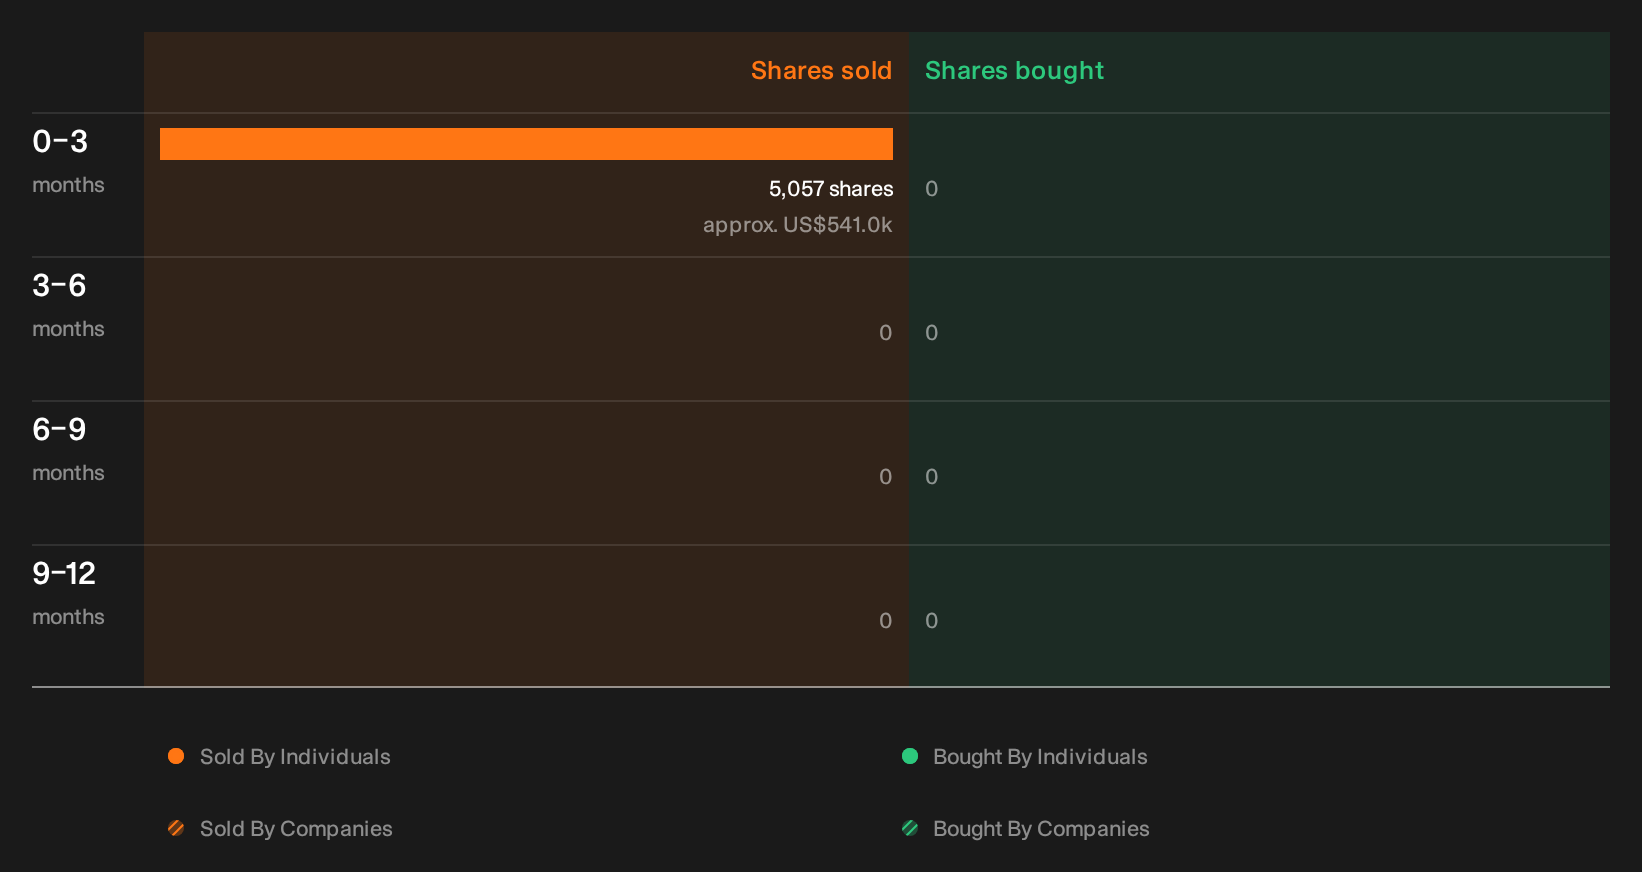
Price, earnings and acquisitions tell part of the Choice Hotels International story, but recent activity in the boardroom share register raises a separate question that deserves its own look. See the recent insider selling flagged for Choice Hotels International.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com