
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Asian Stocks That May Be Undervalued By As Much As 47.1%
Amidst a backdrop of fluctuating global markets and inflationary pressures, Asian equities have captured the attention of investors seeking value opportunities. With economic indicators showing mixed signals across the region, identifying undervalued stocks can be a strategic move for those looking to capitalize on potential market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shanghai Flyco Electrical Appliance (SHSE:603868) | CN¥31.09 | CN¥61.85 | 49.7% |
| Morinaga Milk Industry (TSE:2264) | ¥1060.50 | ¥2118.18 | 49.9% |
| Kingnet Network (SZSE:002517) | CN¥16.01 | CN¥31.51 | 49.2% |
| Innodisk (TPEX:5289) | NT$1290.00 | NT$2523.21 | 48.9% |
| Hainan Jinpan Smart Technology (SHSE:688676) | CN¥61.53 | CN¥122.18 | 49.6% |
| Foxconn Industrial Internet (SHSE:601138) | CN¥58.20 | CN¥114.13 | 49% |
| ENN Energy Holdings (SEHK:2688) | HK$48.70 | HK$96.79 | 49.7% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2851.00 | ¥5577.13 | 48.9% |
| AK Medical Holdings (SEHK:1789) | HK$4.87 | HK$9.52 | 48.8% |
| 3SBio (SEHK:1530) | HK$16.57 | HK$33.11 | 49.9% |
We'll examine a selection from our screener results.
CSPC Pharmaceutical Group (SEHK:1093)
Overview: CSPC Pharmaceutical Group Limited is an investment holding company involved in the manufacture and sale of pharmaceutical products across Mainland China, other Asian regions, Europe, North America, and internationally, with a market cap of approximately HK$114.96 billion.
Operations: The company's revenue is primarily derived from Finished Drugs (CN¥26.40 billion), Bulk Products - Vitamin C (CN¥2.05 billion), and Bulk Products - Antibiotics (CN¥1.35 billion).
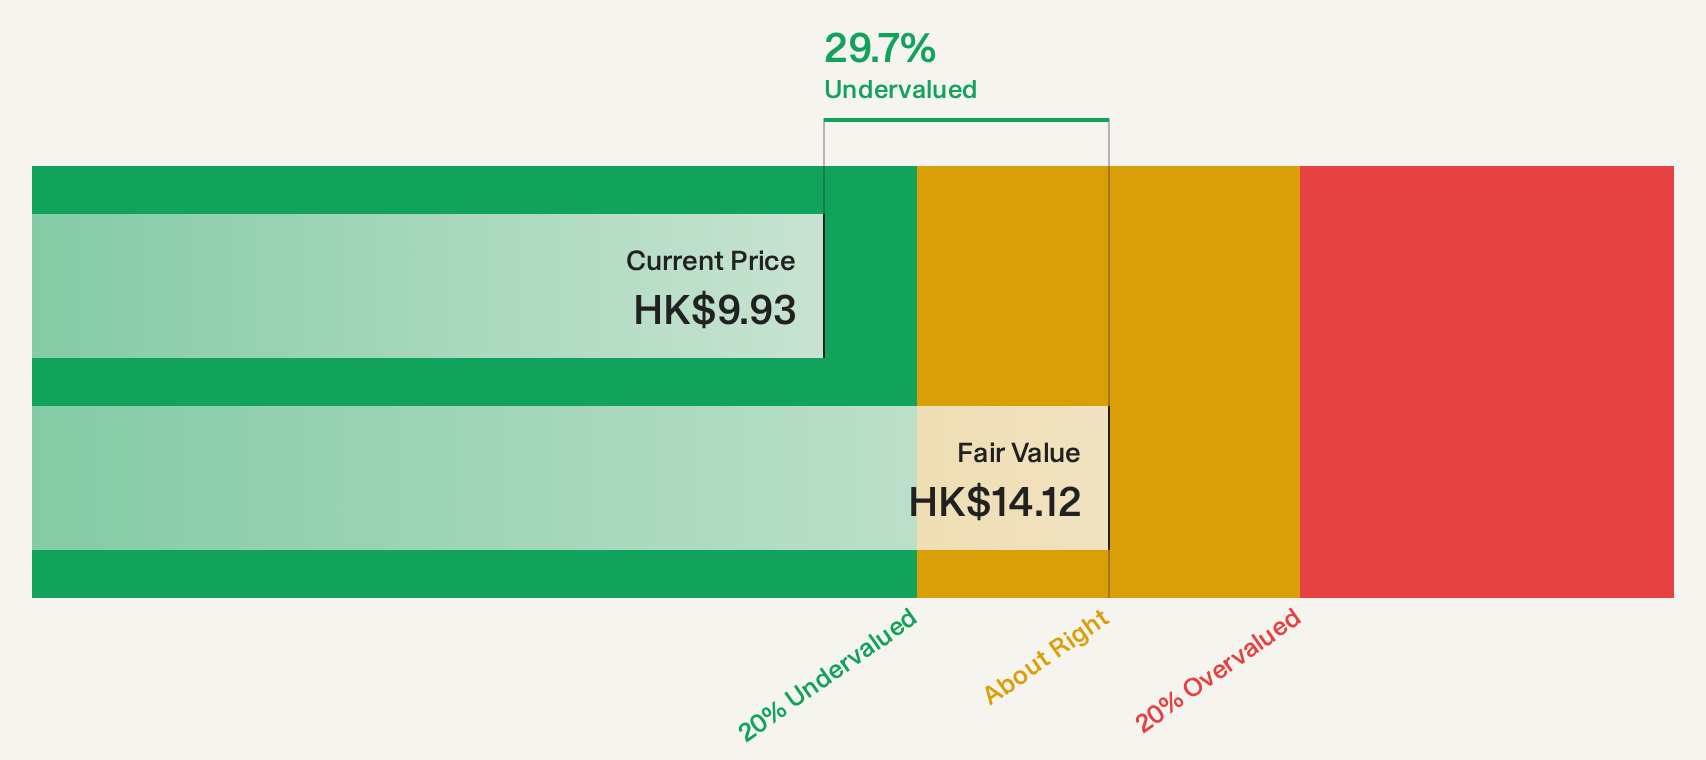
Estimated Discount To Fair Value: 28.7%
CSPC Pharmaceutical Group, trading at HK$10.07, is undervalued relative to its discounted cash flow estimate of HK$14.11, offering a potential value opportunity despite forecasted annual earnings decline of 7.6% over the next three years. Recent positive clinical trial results for diabetes and lung cancer treatments highlight CSPC's strong R&D pipeline, potentially offsetting slow revenue growth projections of 1.3% annually compared to the Hong Kong market's 8.9%.
- Our comprehensive growth report raises the possibility that CSPC Pharmaceutical Group is poised for substantial financial growth.
- Unlock comprehensive insights into our analysis of CSPC Pharmaceutical Group stock in this financial health report.
Mizuho Financial Group (TSE:8411)
Overview: Mizuho Financial Group, Inc. operates in banking, trust banking, securities, and other financial services across Japan and internationally with a market cap of ¥20.79 trillion.
Operations: Mizuho Financial Group's revenue segments include The Retail & Business Banking Company at ¥1.03 trillion, The Global Corporate & Investment Banking Company at ¥860.00 billion, The Corporate & Institutional Company at ¥796.38 billion, The Global Markets Company at ¥804.74 billion, and The Asset Management Company contributing ¥71.61 billion.
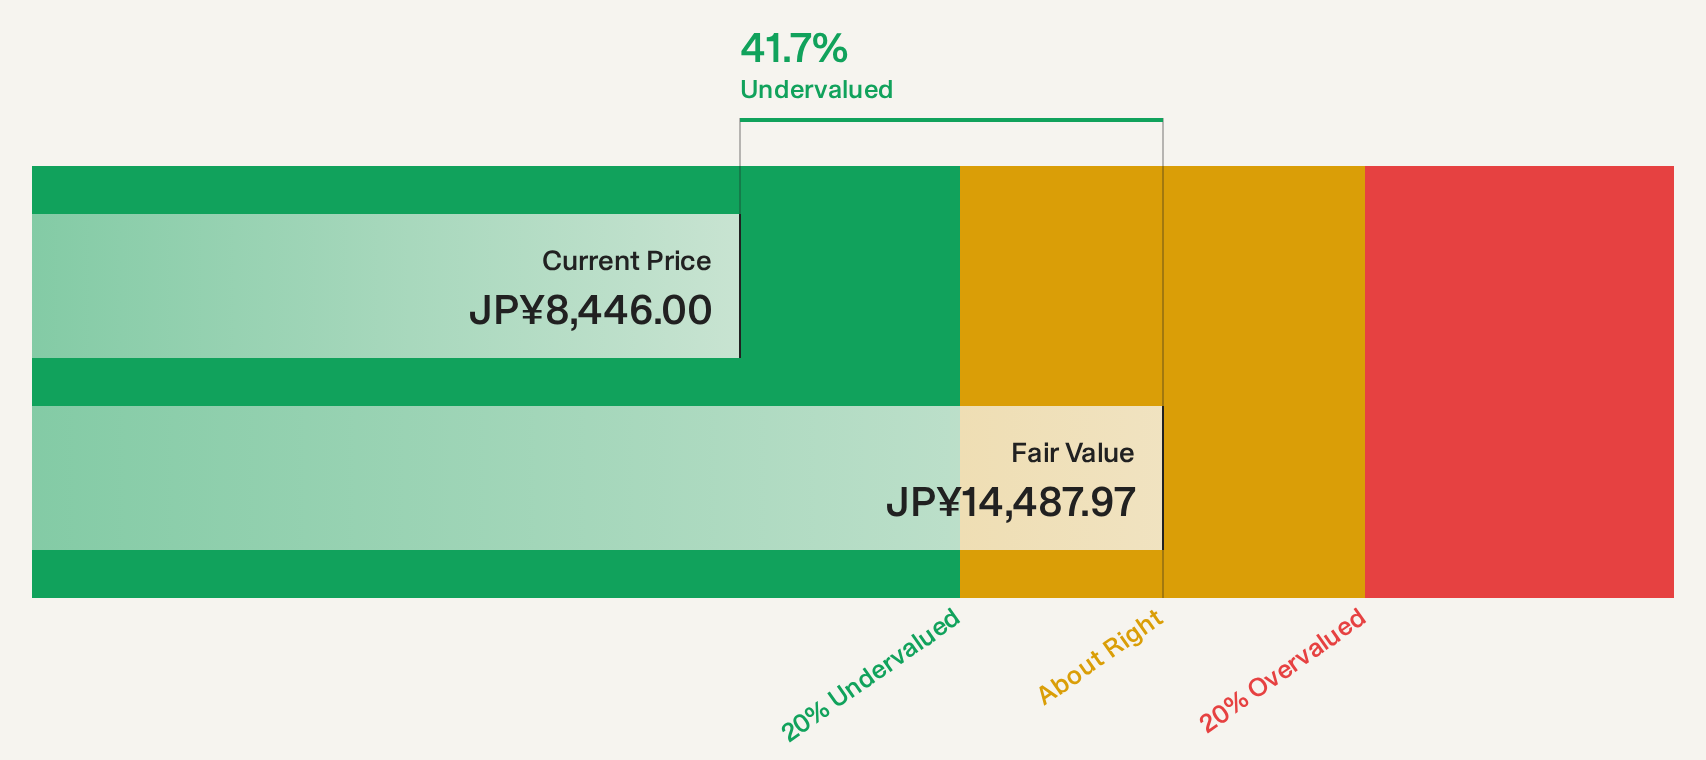
Estimated Discount To Fair Value: 39%
Mizuho Financial Group is trading at ¥8,611, significantly below its estimated future cash flow value of ¥14,115.50. Despite earnings forecasted to grow at 7.6% annually—slower than the Japanese market's 9.2%—the stock presents a good relative value compared to peers and industry standards. Recent share buybacks totaling ¥199,999.94 million enhance shareholder value, while a robust net interest income increase supports its financial health amidst slower revenue growth projections of 2.9% annually.
- Insights from our recent growth report point to a promising forecast for Mizuho Financial Group's business outlook.
- Click here to discover the nuances of Mizuho Financial Group with our detailed financial health report.
Nanya Technology (TWSE:2408)
Overview: Nanya Technology Corporation engages in the research, development, manufacturing, and sale of semiconductor products across various countries including Taiwan, Japan, Malaysia, China, and the United States with a market cap of approximately NT$1.79 trillion.
Operations: The company's revenue is primarily derived from its Manufacturing Division, which accounts for NT$180.23 billion, and its Overseas Sales Division, contributing NT$64.63 billion.
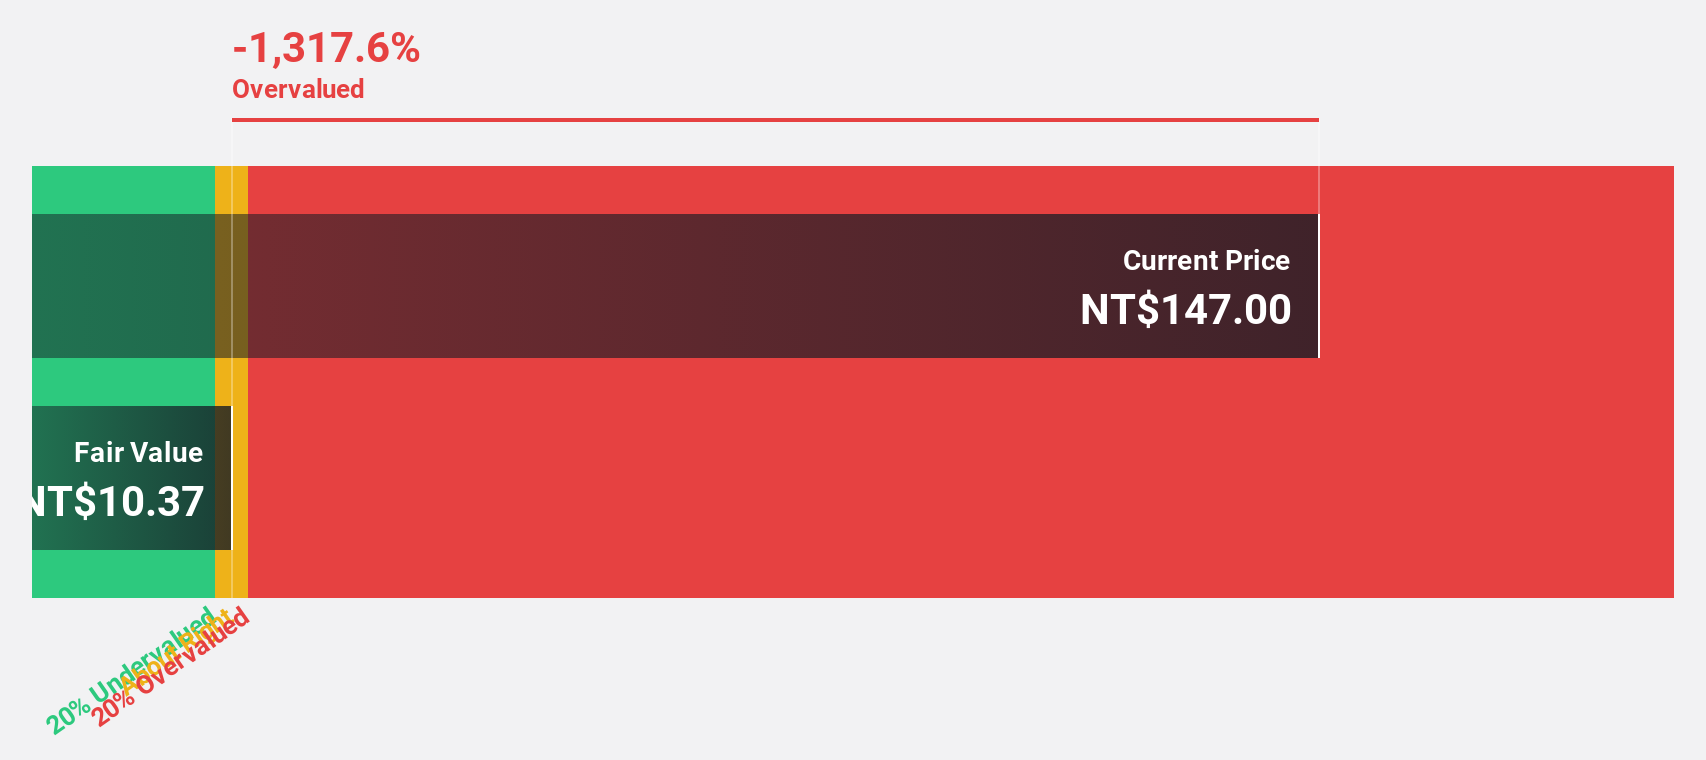
Estimated Discount To Fair Value: 47.1%
Nanya Technology is trading at NT$519, significantly below its estimated future cash flow value of NT$981.22, indicating it is undervalued based on cash flows. The company's earnings and revenue are forecast to grow significantly faster than the Taiwan market, with earnings expected to rise 49.4% annually. Despite recent share price volatility, Nanya's profitability turnaround and strong financial performance in the second quarter highlight its potential as an undervalued investment opportunity.
- According our earnings growth report, there's an indication that Nanya Technology might be ready to expand.
- Take a closer look at Nanya Technology's balance sheet health here in our report.
Make It Happen
- Get an in-depth perspective on all 166 Undervalued Asian Stocks Based On Cash Flows by using our screener here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com