
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PG&E (PCG) Stock Looks Stretched Following Its 25% Slide This Year
PG&E shares have fallen sharply this year, which puts fresh focus on a simple question for income focused investors: whether today's price is adequately backed by the utility's dividend stream.
- The stock is down 25.2% year to date, so any reassessment of PG&E now hinges on what that lower price implies for the value of its future dividends.
- Recent headlines around wildfire liability reform delays in California highlight how future capital spending and potential legal costs can influence how much cash is available for shareholders over time.
- Prefer to judge PG&E on earnings? See why PG&E's 8.8x P/E tells a different valuation story.
For investors, the debate is whether PG&E's current share price fairly reflects the value of the dividend stream that the business can sustain over the long run.
If you want a reference point for how other dividend focused investors are pricing similar trade offs between income and risk, it can help to scan 7 dividend fortresses.
Has PG&E Run Too Far on Dividends?
The Dividend Discount Model (DDM) looks at what PG&E can realistically pay out to you in dividends over time and then compares that stream to today's $12.17 share price. Here the inputs point to a relatively low starting dividend base, with dividend per share of about $0.34 and an earnings payout ratio above 7%, combined with a capped dividend growth rate of 3.7% that sits well below the model's raw expected growth estimate of 8.18%.
This gap between underlying growth assumptions and the tighter 3.7% dividend growth cap suggests PG&E may need to reinvest a large share of profits or keep a cushion for risks, rather than returning most of it to shareholders. That dynamic helps explain why the DDM output sits meaningfully below where the stock trades today. Because the recent UBS downgrade focused on wildfire liability reform delays and the potential impact on long term capital spending, that concern fits neatly with a valuation picture where the current price implies a richer dividend path than the model is willing to underwrite. Find out what PG&E could be worth using our Dividend Discount Model (DDM) estimate.
The PG&E Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for PG&E leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to end up worth materially more or less than today’s price, and setting each view up as a thesis about PG&E's business that you can watch over time rather than a single static snapshot on its Community page.
One of the top community narratives on PG&E: 13% undervalued
"This could delay when those projects flow into rate base and affect the timing of revenue and earnings recognition…"
Discover why this Narrative puts PG&E at 13% undervalued.
One more PG&E signal to weigh before making a move
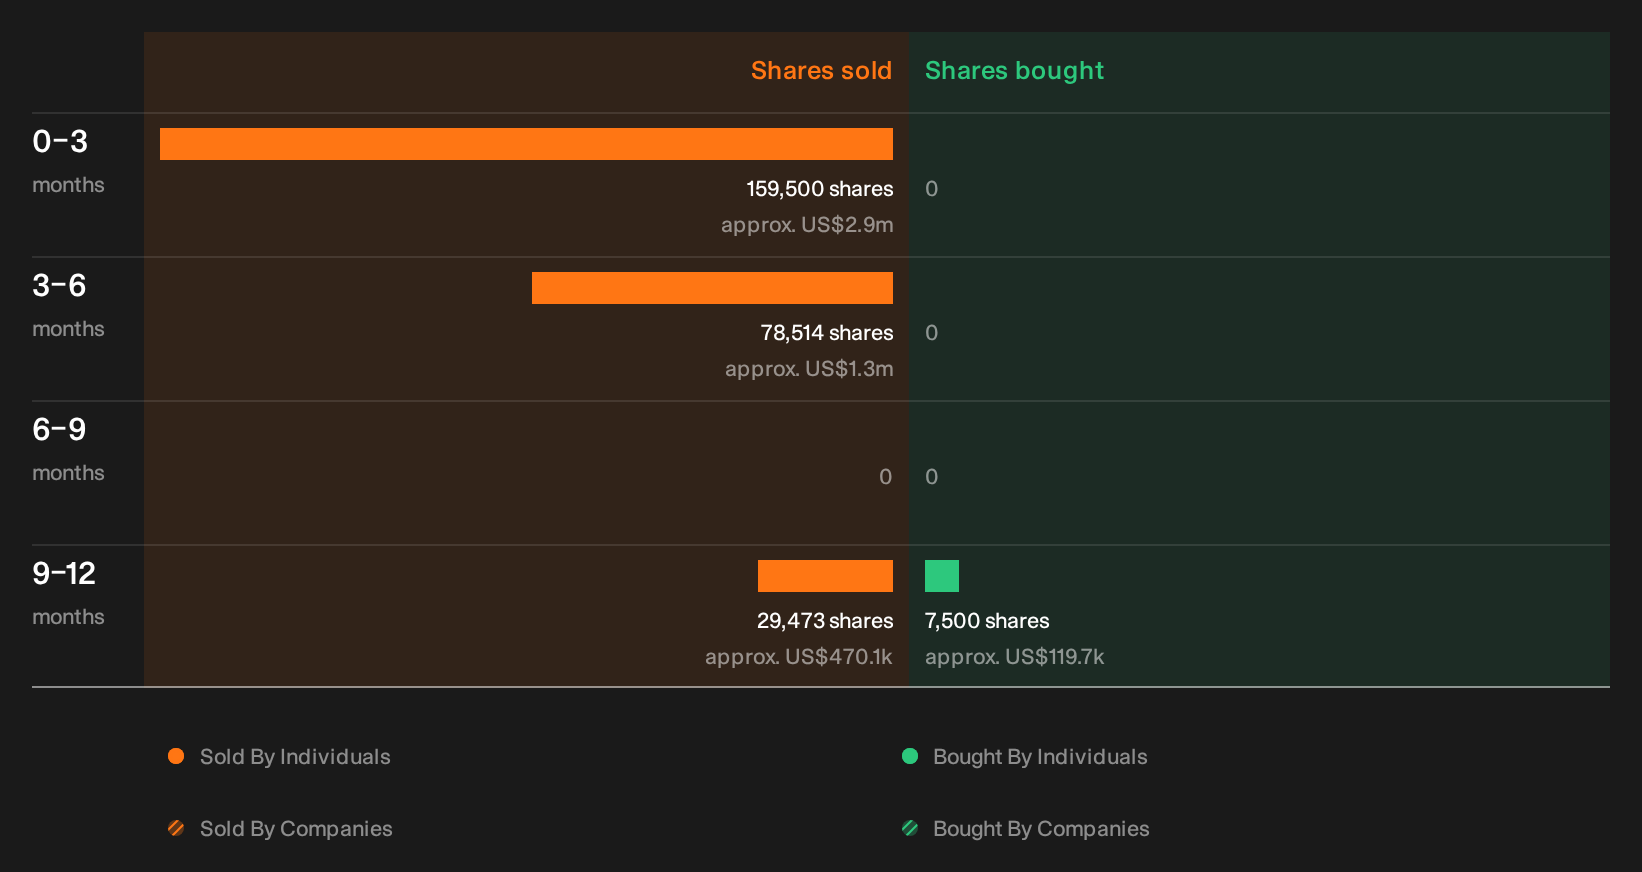
Before you treat PG&E's current valuation as the whole story, it is worth checking what recent selling by company insiders might suggest about how those closest to the business are acting. See the recent insider selling flagged for PG&E.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com