
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fevertree Drinks And 2 British Founder Run Stocks To Own
Global bond markets have pushed UK long term borrowing costs to 28 year highs, putting pressure on heavily indebted firms and management teams with short time horizons. That kind of backdrop can reward British businesses where the founder still owns the legacy and mindset, not just the job title. This article breaks down three founder led UK stocks from our screener that exemplify that alignment and why they merit closer examination at this time.
The three founder led companies below are just a sample, with the full screen surfacing 59 more businesses where owners are still on the hook reputationally and financially in ways hired managers are not.
If you want to identify and analyze those additional founder run opportunities with the highest conviction potential, head straight into the Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks is a founder-built mixer specialist where the original co-founders shaped everything from tonic recipes to brand identity, and that legacy mindset still frames how the group thinks about product focus, capital allocation and long-term value for shareholders.
Fevertree Drinks develops and sells premium mixer drinks under the Fever-Tree brand across the UK, Europe, the US and other international markets, and currently carries a market value of about £937 million.
"The partnership with Molson Coors is intended to secure U.S. profit growth, but an overreliance on one strategic partner may expose Fevertree to unfavorable contract renegotiations, possible margin dilution if guaranteed royalties fail to match rising costs, and slower than expected U.S. market penetration, all of which could weigh on future profits."
What happens to Fevertree Drinks’ earnings profile hinges on how one unseen pressure ultimately flows through pricing power and cost discipline.
That pressure point is exactly where Fevertree Drinks could surprise on the upside, so read the full narrative for Fevertree Drinks to see how pricing power and partnerships might still accelerate value.

Computacenter (LSE:CCC)
Computacenter is a long-established IT services provider where founder-era leadership influence still runs through a seasoned management bench and founder-family shareholding. The group generates about £12.1b from computer services across sourcing, cloud, networking and support work, and carries a market value of roughly £5.7b.
Computacenter interests investors using this founder-led lens because long-tenured leadership is pairing double digit earnings and revenue growth with high forecast ROE around 23%. The P/E of 28.1x sits below key IT peers. The main consideration is how one subtle shift in margins could shape that earnings trajectory.
That hinge on margins makes it worth pulling up the DCF valuation analysis for Computacenter to see where earnings strength could be masking mispriced upside.
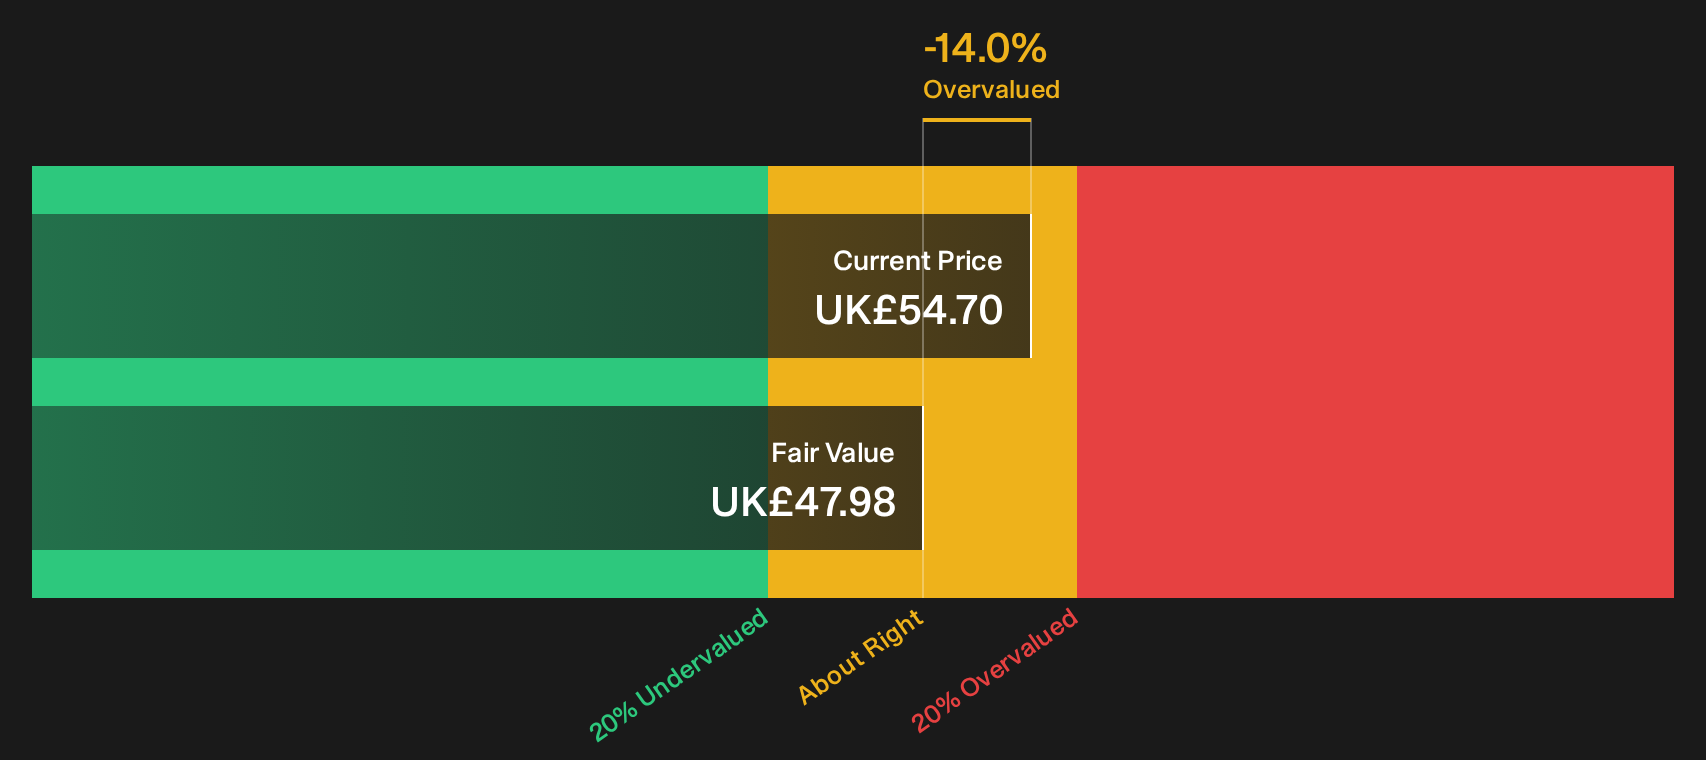
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is a listed asset manager that channels capital into founder and management-led businesses through its private equity and venture arms, while also running a sizeable real assets franchise. Real Assets produced about £114.8 million in revenue and Private Equity about £50.1 million, with the group valued around £513 million.
For investors who want exposure to founder-led growth through the capital providers backing those entrepreneurs, Foresight Group Holdings offers a bridge between infrastructure, private markets and listed funds that is now being reshaped by a more assertive capital return play.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters is how one shift in where new money is raised and deployed ultimately filters through to fee growth and shareholder payouts.
That shift in capital flows is exactly what the full narrative for Foresight Group Holdings unpacks, showing where Foresight Group Holdings could see compounding returns accelerate while key risks remain contained.

Curious About What You Might Be Missing?
Fresh opportunities do not wait. While attention clings to headlines, other stocks quietly build momentum, set up for potential breakouts, then fly once the crowd finally notices. Getting in early can be important.
- Spot cash-rich businesses before sentiment catches up by scanning the list of solid balance sheet and fundamentals (9 results). It filters for financial strength while it still flies under the radar for now.
- Explore structural themes in automation by reviewing the 89 robotics and automation stocks, which is packed with companies building the systems other industries may rely on as demand develops.
- Target income ideas with a focus on resilience by checking the 1 dividend fortresses, where yields and balance sheet quality are combined before the best opportunities attract more attention from yield hunters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com