
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For CBL & Associates Properties (CBL) Could Change Following Land Sales
- CBL & Associates Properties recently closed two additional land sales at Harford Mall in Maryland and Friendly Center in North Carolina, supporting the development of more than 515 class-A multifamily units and contributing to over US$30 million in year-to-date gross proceeds from land deals with mixed-use developers.
- The transactions highlight CBL & Associates Properties' push to monetize underused land while pairing retail assets with multifamily projects. This approach can reshape foot traffic patterns, tenant mix, and the long-run cash flow potential for its broader shopping center portfolio.
- The focus now turns to how CBL & Associates Properties' mixed-use land sales program, including these multifamily projects, may influence the broader investment narrative.
Scan how CBL & Associates Properties' mixed-use push compares with other real estate players monetizing underused sites through curated list of solid balance sheet and fundamentals (25 results).
What Is CBL & Associates Properties' Investment Narrative?
To own CBL & Associates Properties, you need to be on board with a fairly simple idea. The REIT is trying to turn underused mall parking lots and excess land into cash today and more diversified rent streams over time. The latest land deals at Harford Mall and Friendly Center fit directly into that effort, adding over US$30 million in year to date proceeds while seeding 515 plus units of class A multifamily next to existing retail. For a business with 85 properties and capital intensive assets, those transactions can matter for near term funding flexibility.
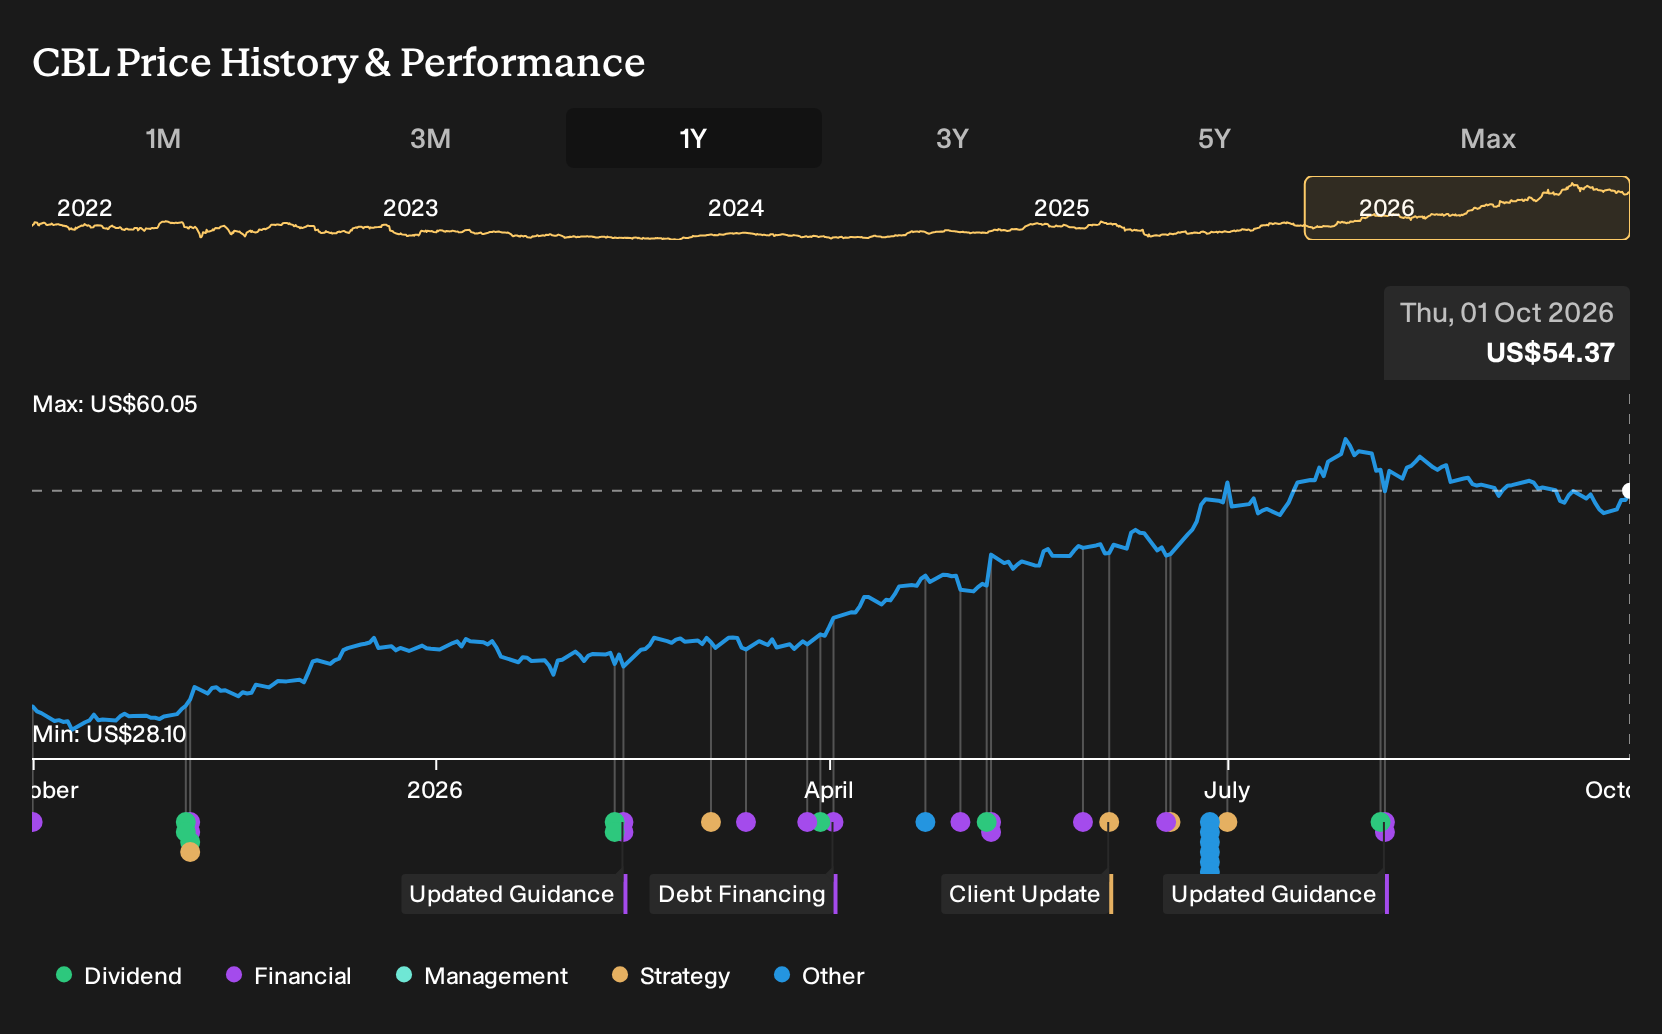
In the short term, the key questions are about execution and balance sheet resilience rather than headline revenue growth. CBL & Associates Properties has posted recent earnings growth of 232.8% and carries a P/E of 7.9x, which screens below the broader US market but not far from some fair value estimates that place the shares near US$44.52. Forecasts point to a decline in earnings over the next three years and interest costs are not comfortably covered, so any cash raised from land sales only helps if management maintains discipline on leverage, reinvestment and the quality of new mixed use tenants.
Even so, there is a structural pressure on this story that could matter a lot if ...
There's only one way to know the right time to buy, sell or hold CBL & Associates Properties. Head to Simply Wall St's company report for the latest analysis of CBL & Associates Properties's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$44.52 and US$63, which already shows how far opinions on CBL & Associates Properties can stretch. Because these figures were set before the latest mixed use land sales, you should treat them as a starting point and then explore several alternative viewpoints.
Explore another CBL & Associates Properties fair value estimate, including one that indicates as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CBL & Associates Properties research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for CBL & Associates Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBL & Associates Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond CBL & Associates Properties?
If you want to stress test the CBL & Associates Properties thesis, the next step is to compare it with a wider set of listed real estate and income focused businesses. The Simply Wall St Screener lets you line up opportunities by balance sheet strength, valuation, income profile and more, so you can see where CBL & Associates Properties fits in your broader watchlist.
- For investors who care most about durable finances and staying power, start with a curated 31 resilient stocks with low risk scores that have historically scored well on resilience and balance sheet quality.
- If you are hunting for mispriced opportunities with quality fundamentals, line CBL & Associates Properties up against a hand picked set of 19 high quality undiscovered gems that may not yet be on every investor's radar.
- Income focused readers can compare the REIT to a universe of 7 dividend fortresses that combine higher yields with financial profiles that clear a basic sustainability screen.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com