
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Silicon Motion Technology (SIMO) Beats Estimates, Is It Still Below Fair Value?
Why Silicon Motion Technology Is Back On Investors’ Radar
Silicon Motion Technology (SIMO) has jumped into focus after quarterly results topped both revenue and earnings per share expectations, followed by rising earnings estimates and a stronger analyst rating that is feeding fresh investor attention.
Recent enthusiasm around Silicon Motion Technology is showing up in the tape. The share price has climbed 15.96% over the past month and the year to date share price return of 193.56%, alongside a 1 year total shareholder return of 173.35%, points to momentum that has built over several years, with management’s recent conference appearances and the upcoming AGM helping keep the story in front of investors.
Scan beyond Silicon Motion Technology and see how it compares with other fast moving chip specialists in the 90 AI infrastructure stocks.
The question now is whether Silicon Motion Technology’s sharp re-rating has already captured most of the good news, or if the current price still leaves meaningful upside on the table once you run the valuation numbers.
Most Popular Narrative: 26% Undervalued
On the numbers used most widely by followers of Silicon Motion Technology, a fair value of about $369.70 sits well above the last close at $275.24. This puts the current debate squarely on whether the AI and storage story justifies that gap.
The rapid expansion of high-performance storage demand from AI, data centers, cloud computing, and edge computing is fueling adoption of advanced NAND controller solutions, particularly Silicon Motion's PCIe Gen 5 and enterprise-focused MonTitan controllers, supporting robust future revenue and margin growth as these markets scale.
See why 62 investors see Silicon Motion Technology as 26% undervalued.
On this framework, the fair value of $369.70 is built using a 12.12% discount rate, analyst assumptions for earnings rising from roughly $289.8 million today to $636.9 million by around 2029, and a future P/E of 28.6x. The same narrative also leans on expected revenue of $3.1 billion and profit margins near 20.6%, together with the view that current AI related demand for SSD and enterprise controllers supports that earnings profile.
For you as an investor, the key question is whether those inputs feel reasonable. That includes the pace of AI infrastructure build out, the durability of Silicon Motion Technology's controller position with major NAND makers, and the ability to sustain margins in what is described as a highly price competitive set of end markets.
Result: Fair Value of $369.70 (UNDERVALUED)
Still, the Silicon Motion Technology narrative can crack if aggressive AI driven controller forecasts meet tougher price competition, or if rising R&D and operating costs squeeze profitability.
Find out about the key risks to this Silicon Motion Technology narrative.
Another View On Silicon Motion Technology’s Valuation
A different lens comes from the SWS DCF model, which puts Silicon Motion Technology’s value at about $158.90 per share, well below the recent $275.24 price and flagged as overvalued on this cash flow view. That is a sharp contrast to the analyst fair value. Which story do you lean toward?
For a closer look at how that cash flow based figure is built and what would need to change in the assumptions for the result to move closer to the current price, Look into how the SWS DCF model arrives at its fair value.
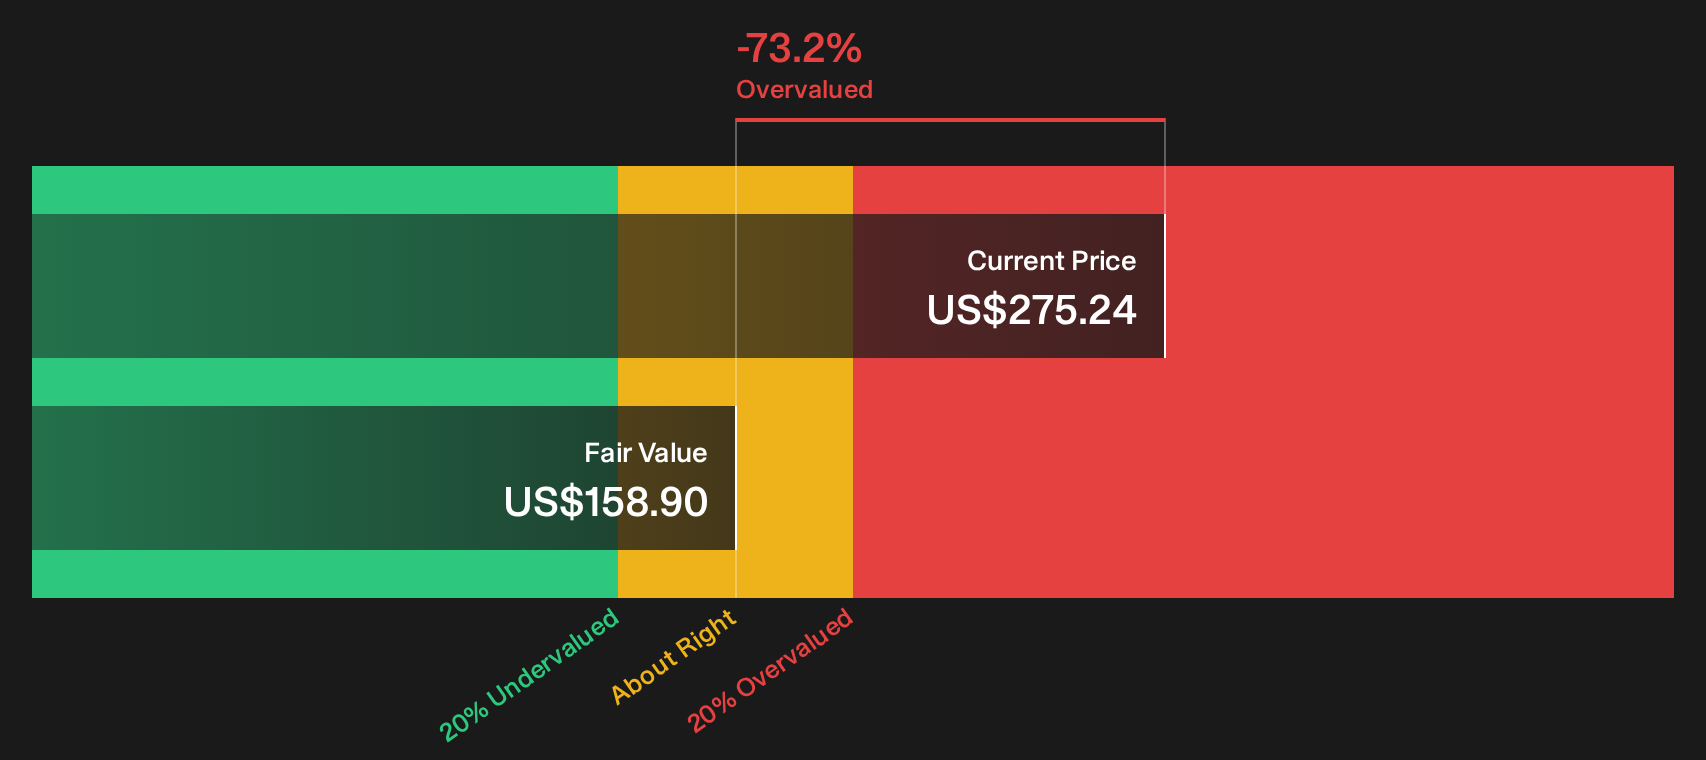
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silicon Motion Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Silicon Motion Technology leaves you undecided, move quickly and review the numbers yourself, weighing both the potential upside and the pressure points highlighted in the 5 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Silicon Motion Technology?
Do not stop with Silicon Motion Technology. Broaden your watchlist now with fresh ideas that match your goals before the next wave of opportunities moves without you.
- Target potential mispricing by scanning a focused 28 high quality undervalued stocks that highlight companies combining quality fundamentals with prices that may not fully reflect their financial strength.
- Protect your capital by reviewing a 31 resilient stocks with low risk scores that feature resilient businesses with steadier earnings profiles and stronger balance sheet support.
- Spot tomorrow's potential leaders early by tracking a curated 19 high quality undiscovered gems where strong fundamentals have not yet attracted widespread attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com