
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arcus Biosciences (RCUS) Dropped, What Is Behind The Latest Attention?
Why the Arcus Biosciences event matters for investors
Arcus Biosciences (RCUS) has scheduled an in-person investor event on October 20, 2026, in New York City, centered on fresh ARC-20 study data for its HIF-2a inhibitor casdatifan in kidney cancer.
The session is set to cover safety and early efficacy readouts across first-line TKI-free combinations, second-line TKI-containing regimens, and late-line monotherapy, all in clear cell renal cell carcinoma. For anyone tracking the stock, this is effectively a concentrated update on the progress of Arcus Biosciences’ lead asset.
Arcus Biosciences’ latest event lands after a mixed stretch for the ticker, with the share price up 8.33% year to date but down 15.08% over 30 days and 16.81% over 90 days. At the same time, the 1-year total shareholder return of 88.71% and 3-year total shareholder return of 54.03% point to strong longer term gains, making the recent weakness appear more like cooling momentum than a broken story.
Scan beyond Arcus Biosciences and line up other cancer-focused developers with similar breakout potential using the curated 19 high quality undiscovered gems.
Arcus Biosciences has already delivered a powerful 1-year run, yet the latest pullback and upcoming casdatifan readout leave a harder question. Is most of the reward now in the rear-view mirror, or does valuation still point to meaningful upside ahead?
Most Popular Narrative: 34% Undervalued
Analyst modelling pegs Arcus Biosciences’ fair value at $38 per share, which sits well above the last close at $25.23 and frames the kidney cancer franchise as the main swing factor in that gap.
Arcus Biosciences is prioritizing the launch of its late-stage development program for the HIF-2 alpha inhibitor, casdatifan, which has shown significant efficacy differentiation relative to existing market competitors. This could enhance future revenue through competitive advantage in the RCC market.
See why 10 investors see Arcus Biosciences as 34% undervalued.
Result: Fair Value of $38 (UNDERVALUED)
Still, the Arcus Biosciences story can change quickly if key casdatifan trials disappoint, or if competing HIF-2a therapies gain clinical or commercial traction first.
Find out about the key risks to this Arcus Biosciences narrative.
Another View: What Arcus Biosciences’ Sales Multiple Is Telling You
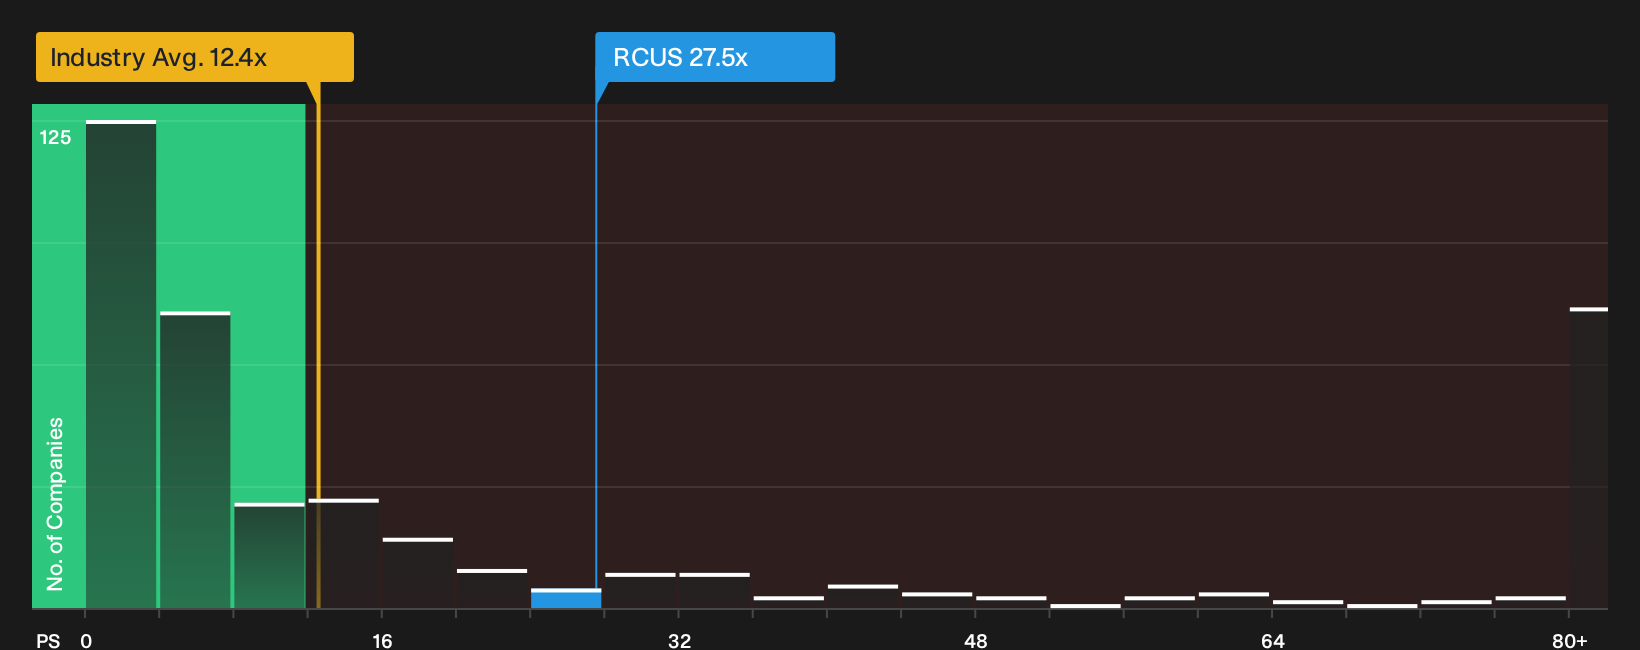
There is a catch. While the analyst fair value points to Arcus Biosciences looking cheap, the current P/S ratio near 27.5x is more than double the US Biotechs average of 12.4x and far above a fair ratio of 0.2x. This signals that a lot of success is already priced into every dollar of revenue. Does that mismatch represent opportunity, or does it simply raise the bar for future trial results?
See what the numbers say about this price in the detailed valuation workup, including how Arcus Biosciences compares to peers and that fair ratio the market could move toward over time, in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Arcus Biosciences can feel noisy, so act while sentiment is still in flux and review the key data yourself, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more Arcus Biosciences sized ideas?
If Arcus Biosciences has your attention, do not stop here. Broaden your watchlist, compare fresh setups, and let high quality filters surface your next lead.
- Target potential mispricings by running screens for quality businesses that currently look inexpensive using the 28 high quality undervalued stocks.
- Prioritize resilience in tougher markets and focus on companies with stronger finances through the list of solid balance sheet and fundamentals (25 results).
- Balance return potential with capital preservation by zeroing in on stocks with lower risk profiles via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com