
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Henkel (XTRA:HEN3) Stock Could Be Reasonable With Room To Rerate
Henkel KGaA shares have inched higher over the past few years, which puts the spotlight firmly on what investors are paying for its earnings today. With the stock changing hands around €71.92, the central question is whether that price still lines up with what the business is generating in profit.
- Over the past 3 years the share price has returned about 15.0%, which makes it important to ask if earnings strength alone can carry the next phase.
- The group relies heavily on steady cash generation from its consumer and industrial product lines, so any shift in margins or reinvestment needs can change what a fair earnings multiple looks like.
- Your read on Henkel KGaA is one view; the desks covering it have another. See what analysts think Henkel KGaA's shares could be worth.
The issue now is whether Henkel KGaA's current share price is properly supported by the earnings power of the underlying business.
If you are evaluating Henkel KGaA based on its earnings alone, it may be helpful to compare that metric with other companies screened on similar criteria through 190 high quality undervalued stocks
Is Henkel KGaA Still Cheap on Earnings?
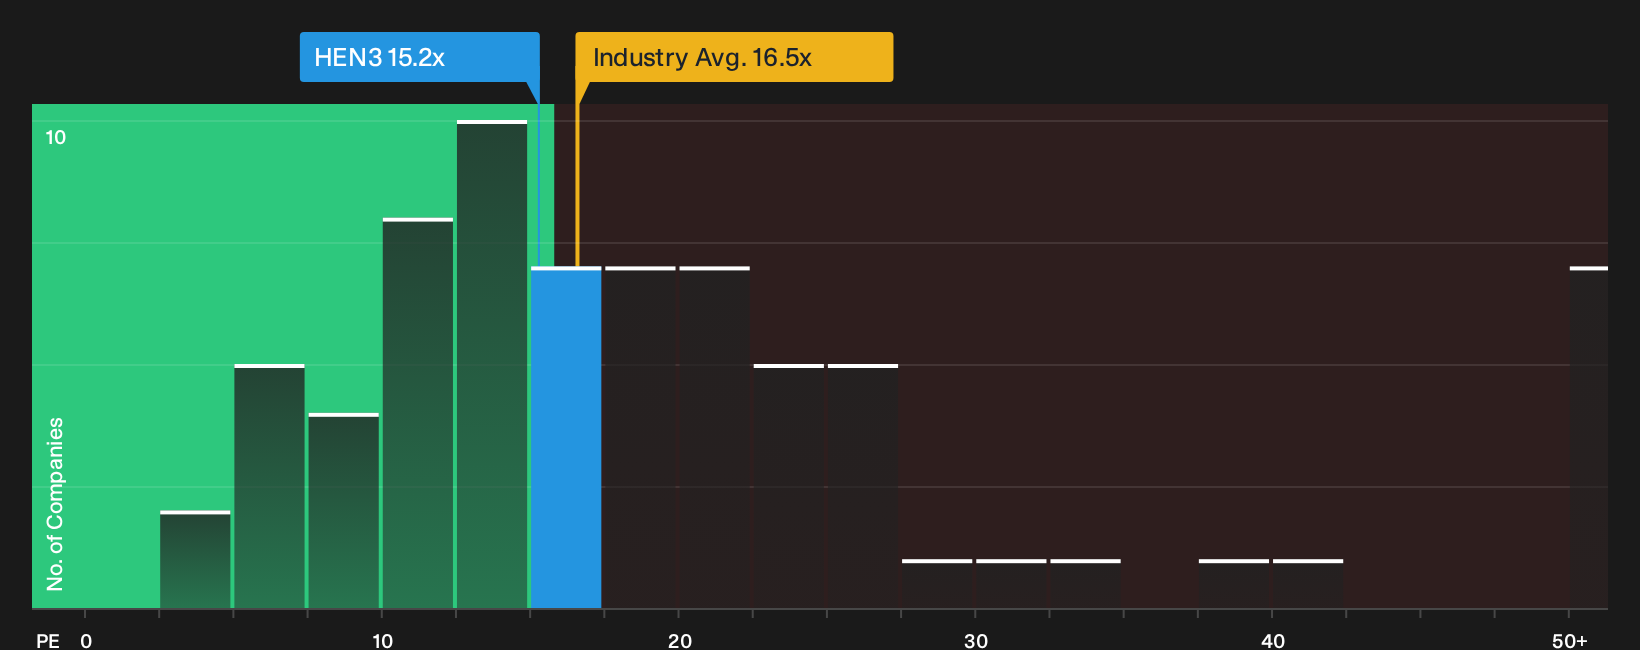
The P/E ratio suits Henkel KGaA because earnings remain the main reference point for what buyers are paying for the underlying business. At around 15.2x earnings, the stock trades below the Household Products industry average of roughly 16.5x and also below the broader peer group on about 19.2x. That gap indicates the market is currently assigning a lower earnings tag to Henkel KGaA than to many comparable consumer and industrial product companies.
The fair P/E that falls out of the model, which blends the company’s growth profile, profitability, sector context and perceived risk, sits above the current 15.2x level. This places the stock in undervalued territory on this framework, because the present earnings multiple is lower than what those fundamentals would typically support. For an investor weighing Henkel KGaA, the key question is whether the quality and resilience of its profit stream justify the P/E moving closer to that fair level over time. Explore the numbers behind Henkel KGaA's P/E valuation.
The Henkel KGaA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/E puzzle for Henkel KGaA leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the share price to look meaningfully higher or lower than today. Each narrative ties a fair value estimate to a particular mix of potential catalysts and risks, allowing you to see over time which version of Henkel KGaA's story is actually unfolding on the Community page.
One of the top community narratives on Henkel KGaA: 8% undervalued
"Portfolio optimization via divestment of low-margin private label or retailer brands and focus on top 10 core brands in Consumer will enhance product mix and margin profile…"
Discover why this Narrative puts Henkel KGaA at 8% undervalued.
One more Henkel KGaA checkpoint that sits beyond the P/E
Price and earnings only tell part of the story, because the people setting priorities and their pay structures can shape how those profits are pursued over time. See who runs Henkel KGaA and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com