
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UK Workplace Pension Stocks Facing An Auto Enrolment Turning Point
Workplace pensions in the UK are under quiet but meaningful strain, as younger employees weigh rising bills against long term saving and some start to step away from auto enrolment. That shift could reshape who gathers retirement money, who loses it and who adapts quickest. This article walks through three UK pension platform and administration stocks exposed to that trend, and why their responses might matter for your portfolio decisions.
The three stocks below are a starting slice of this theme. The full screen on Simply Wall St surfaced 10 more UK workplace pension platforms and administrators with equally detailed narratives that are not covered here. To identify and analyze those extra potential providers directly, head straight to the UK Workplace Pension Platforms and Administrators screener.
Quilter (LSE:QLT)
Overview: Quilter is a UK wealth manager that blends financial advice, investment platforms and pension-focused solutions for affluent and high net worth clients.
Operations: Quilter generates most of its £13.0b revenue from the Affluent segment at £11.7b, with £247m from High Net Worth activities.
Market Cap: £2.3b
Quilter matters in this pensions-focused screen because its advice network and platform sit close to where workplace retirement savings get invested.
"The ongoing shift from defined benefit to defined contribution pensions places more responsibility on individuals for retirement savings, which in turn increases demand for Quilter's advisory and managed solutions and expands the company's potential revenue opportunity."
What happens if one quiet pressure on Quilter's margins and fees sharpens just as more pension savers start seeking guided support?
If that margin squeeze is the real fulcrum, the full narrative for Quilter shows how Quilter’s model could still turn rising pension complexity into accelerating client stickiness.

Standard Life (LSE:SDLF)
Overview: Standard Life is a long-term savings and retirement provider focused on UK workplace pensions, auto-enrolment schemes, and related retirement products.
Operations: Standard Life reports £2.7b revenue from Retirement Solutions, with reported declines in Pensions & Savings, With-profits, and Europe & Other segments.
Market Cap: £8.6b
Standard Life sits right in the flow of UK workplace pension contributions, so its decisions on capital, products and partnerships matter a lot for how those long-term savings are managed.
"The commitment to deleverage and reduce the leverage ratio to 30% by 2026 is expected to lower financial risk and interest expenses, potentially improving net margins and increasing investor confidence."
What happens if one unresolved pressure on Standard Life’s funding costs breaks differently just as workplace pension reforms start to reshape flows?
If that funding pivot is the hinge, the full narrative for Standard Life shows how Standard Life could turn deleveraging into accelerating pension flows and a stronger franchise story.
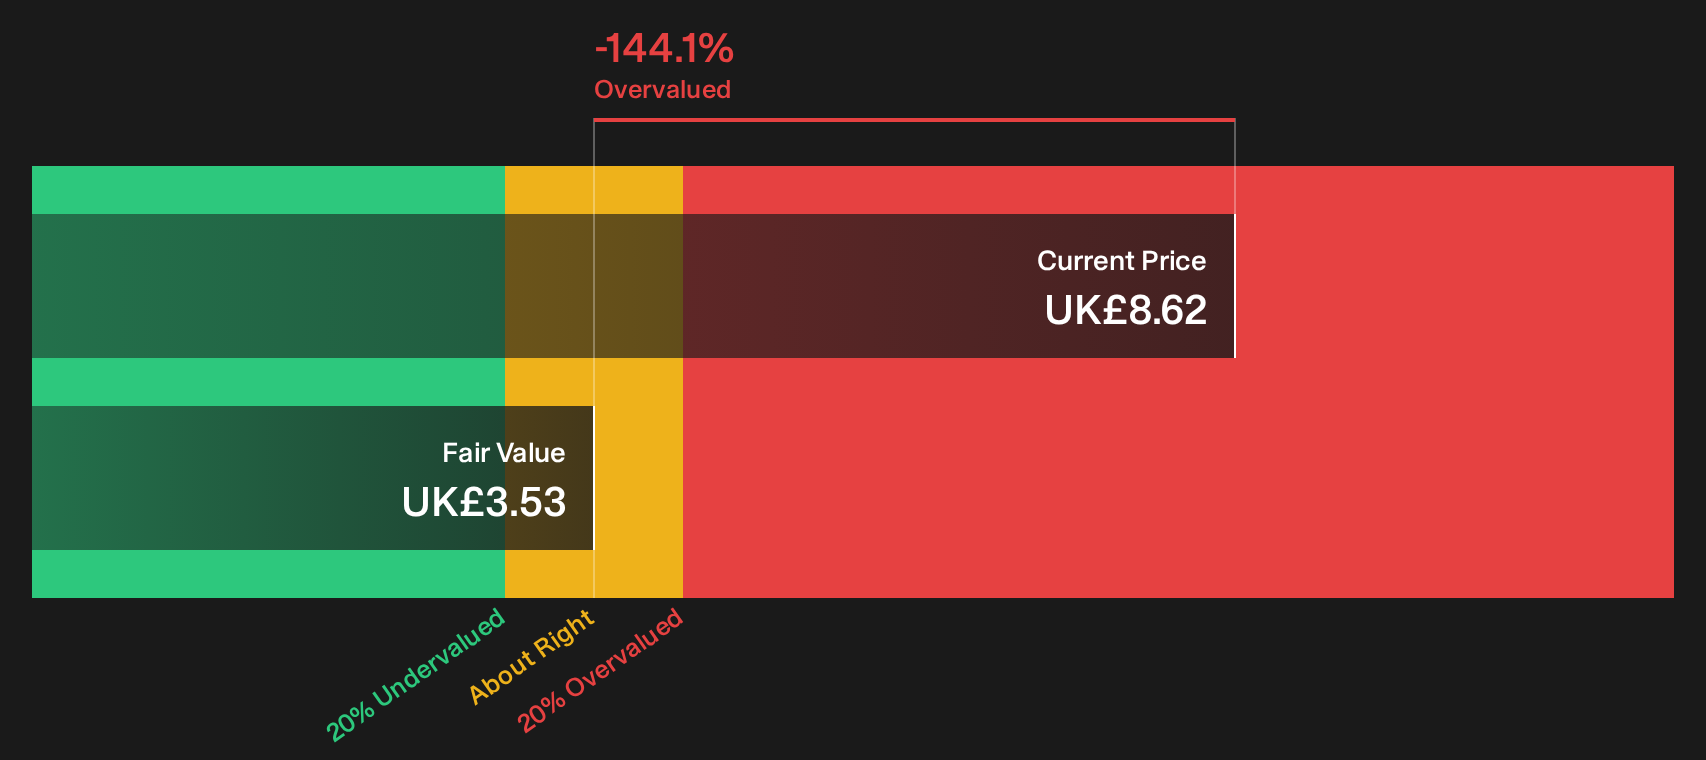
XPS Pensions Group (LSE:XPS)
Overview: XPS Pensions Group provides UK-focused pensions consulting, workplace scheme design, and administration services that run the nuts and bolts of retirement plans.
Operations: XPS Pensions Group generates £262.7 million in revenue from Consulting and Administration Services, all from clients in the United Kingdom.
Market Cap: £600.0 million
XPS Pensions Group is a pure play on UK workplace pensions, earning fees from advising and administering the schemes affected by auto enrolment, regulatory changes, and participation trends. Investors gain direct exposure to that ecosystem; however, returns may be significantly influenced by how any single pressure on pension scheme demand or pricing develops over time.
Those fee and demand pressures make timing critical, so review the 3 key rewards and 2 important warning signs to see what could rapidly tilt XPS Pensions Group’s risk reward balance.

Seeking Alternatives Before Everyone Else?
Fresh ideas move first. Some stocks are building quiet breakout momentum while the crowd watches yesterday's headlines and gets caught late. Scan what is flying under the radar for now and consider your options.
- Spot dependable payers that could help steady your portfolio and keep income flowing by reviewing the curated 1 dividend fortresses before yields start dropping.
- Track early infrastructure names tied to AI and cloud demand by scanning the focused 90 AI infrastructure stocks while the story is still forming.
- Review under-the-radar operators connected to rising electricity demand through the specialist 39 power grid technology and infrastructure stocks while these grid plays remain quietly priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com