
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Eurofins Scientific (ENXTPA:ERF) Could Change Following Central Lab Growth
- Eurofins Scientific has recently been highlighted in global central lab market research as a major provider benefiting from rising clinical trial outsourcing, precision medicine programs, AI supported analytics and decentralized trial models.
- The same industry work suggests Eurofins Scientific could see steadier contract volumes as sponsors seek standardized, globally coordinated lab services across multi country clinical studies.
- We will now explore how Eurofins Scientific's position in central lab outsourcing could influence the broader investment narrative around the business.
Scan how Eurofins Scientific’s central lab story compares with other research heavy compounders by reviewing our curated list of 616 high quality undiscovered gems that may still be flying under most investors' radar.
Eurofins Scientific Investment Narrative Recap
To own Eurofins Scientific, you need to believe its broad testing platform and central lab services can turn steady clinical outsourcing into durable cash generation, even with only moderate growth. The recent central lab market work points to a €3.0b sector in 2025 growing to €4.4b by 2032, which supports the idea of a reasonably firm demand backdrop rather than a step change.
In the near term, the key swing factor remains how efficiently Eurofins Scientific converts that demand into margins and cash while managing high capex and integration projects like SYNLAB Spain. The biggest operational risk is that weaker biopharma and genomics activities keep dragging on organic growth, which would make debt more uncomfortable and slow any balance sheet improvement.
The most relevant news item here is Eurofins Scientific being flagged as a major competitor in the global central labs report through 2032. That reference aligns with the existing thesis around automation, digital infrastructure and a hub and spoke lab model, because it highlights where the platform already carries weight in multinational clinical trials and precision medicine work.
For catalysts, the central lab spotlight speaks directly to the idea of more stable, contract based workflows that could support margin improvement if cost discipline holds. The main risk is that integration challenges, pricing pressure in long contracts and elevated investment needs dilute the benefit of any extra clinical volumes, particularly if structurally weaker segments do not recover as anticipated.
Eurofins Scientific’s current analyst script points to revenues of €8.9b and earnings of €894.2m by 2029, up from current earnings of €469.9m, which implies 6.4% yearly revenue growth and an earnings increase of about €424m if that consensus plays out.
Uncover why Eurofins Scientific's fair value indicates a 3% potential downside to its current price, leaving little room for error.
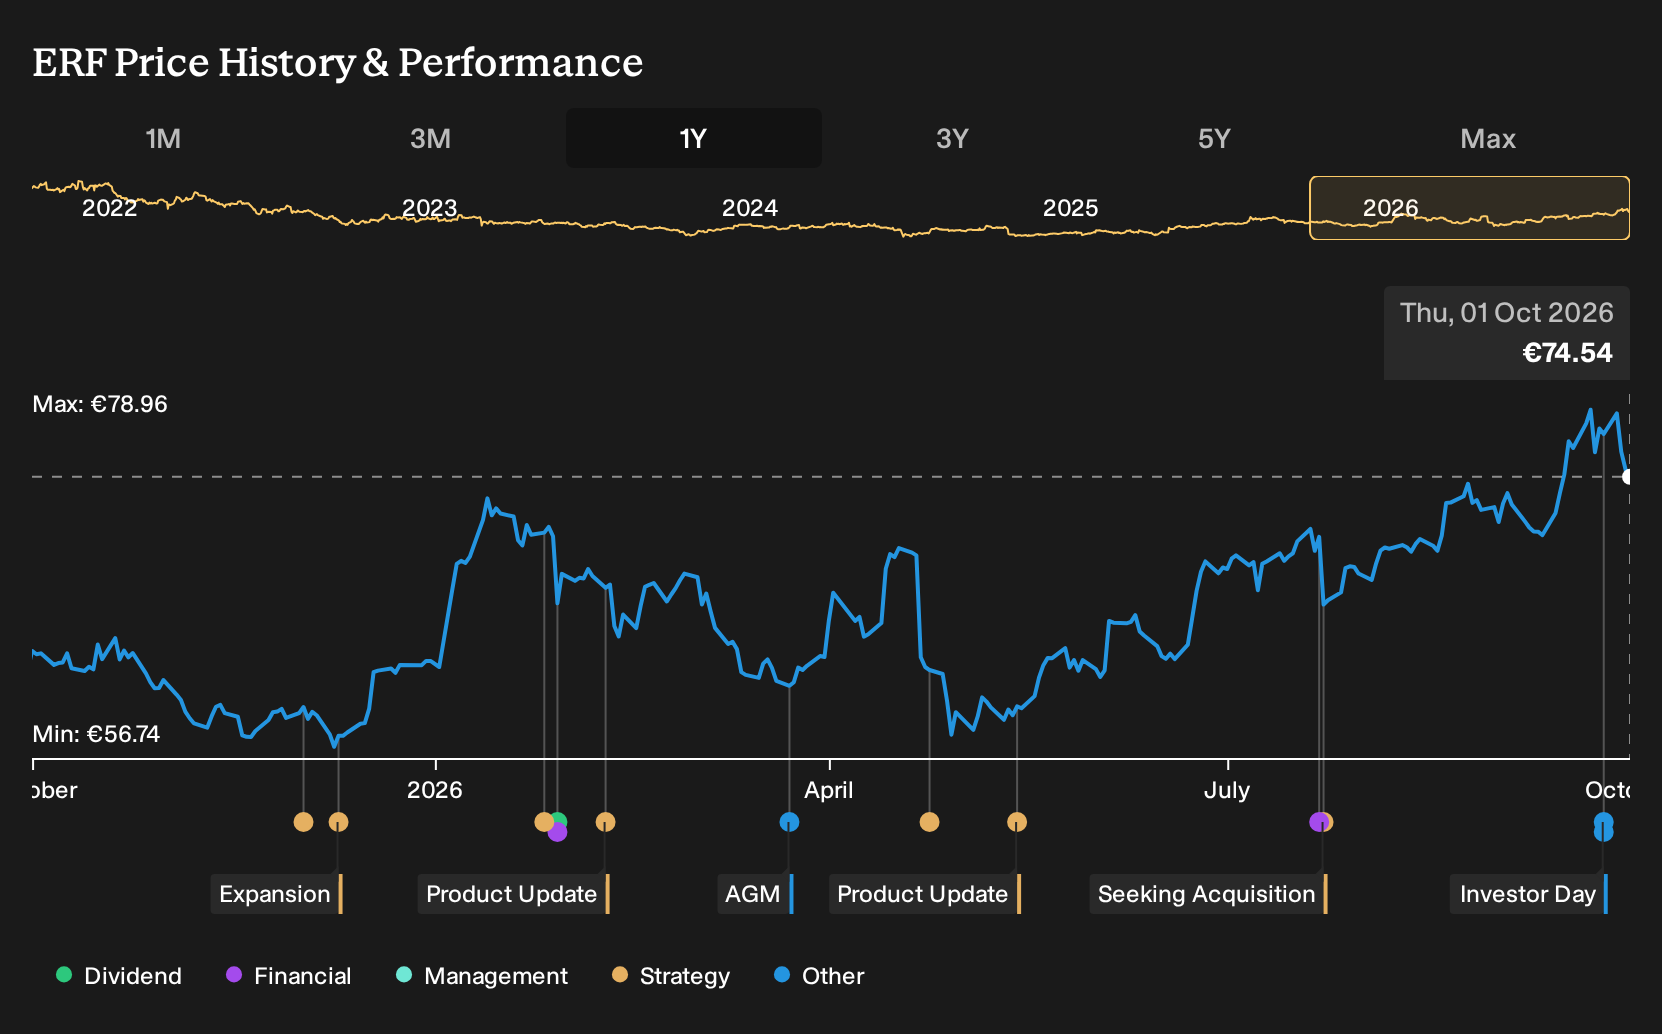
Exploring Other Perspectives
One bullish twist on Eurofins Scientific focuses on faster than expected benefits from its digital and infrastructure spend. The most optimistic analysts were already pencilling in €9.4b of revenue and €965.0m of earnings by 2029 before this central lab news. That is a much richer story. Use it as a prompt to compare multiple viewpoints.
Explore 4 other Eurofins Scientific fair value estimates, including one that suggests as much as 22% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on careful research.
- A great starting point for your Eurofins Scientific research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eurofins Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eurofins Scientific's overall financial health at a glance.
Looking for more Eurofins Scientific sized investment ideas?
If the Eurofins Scientific story has you thinking about what else might be hiding in plain sight, it can help to scan a wider field of potential opportunities with similar or stronger fundamentals.
- For investors who care most about valuation support and balance sheet strength, consider screening for a 189 high quality undervalued stocks that combines healthy finances with compressed expectations.
- If resilience and capital protection sit at the top of your checklist, build a watchlist starting with a 224 resilient stocks with low risk scores that scores well on stability and risk metrics.
- For a quality first approach that still leaves room for upside, widen your research universe using a list of solid balance sheet and fundamentals (207 results) that clears a high bar on financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com