
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Oil And Gas Stocks Worth Watching As Brent Crude Stays Above $100
Oil is flowing again through the Strait of Hormuz at roughly pre war volumes, yet refined fuel supplies remain tight and Brent crude holds above $100. That mix of relief and lingering stress is reshaping cash flows for integrated oil and gas majors and the companies that rely on them. This article unpacks the story and highlights 3 stocks exposed to this news that merit a closer look right now.
The three stocks below are a sample starting point, and the full screen surfaced 17 more large integrated oil and gas companies with similarly detailed stories that are not covered here. To go straight to the broader opportunity set, use the Global Integrated Oil & Gas Majors screener to identify and analyze the highest conviction integrated majors for your watchlist.
Par Pacific Holdings (PARR)
Overview: Par Pacific Holdings is a Houston based energy business that runs U.S. refineries, fuel retail networks and logistics assets supplying renewable and conventional fuels.
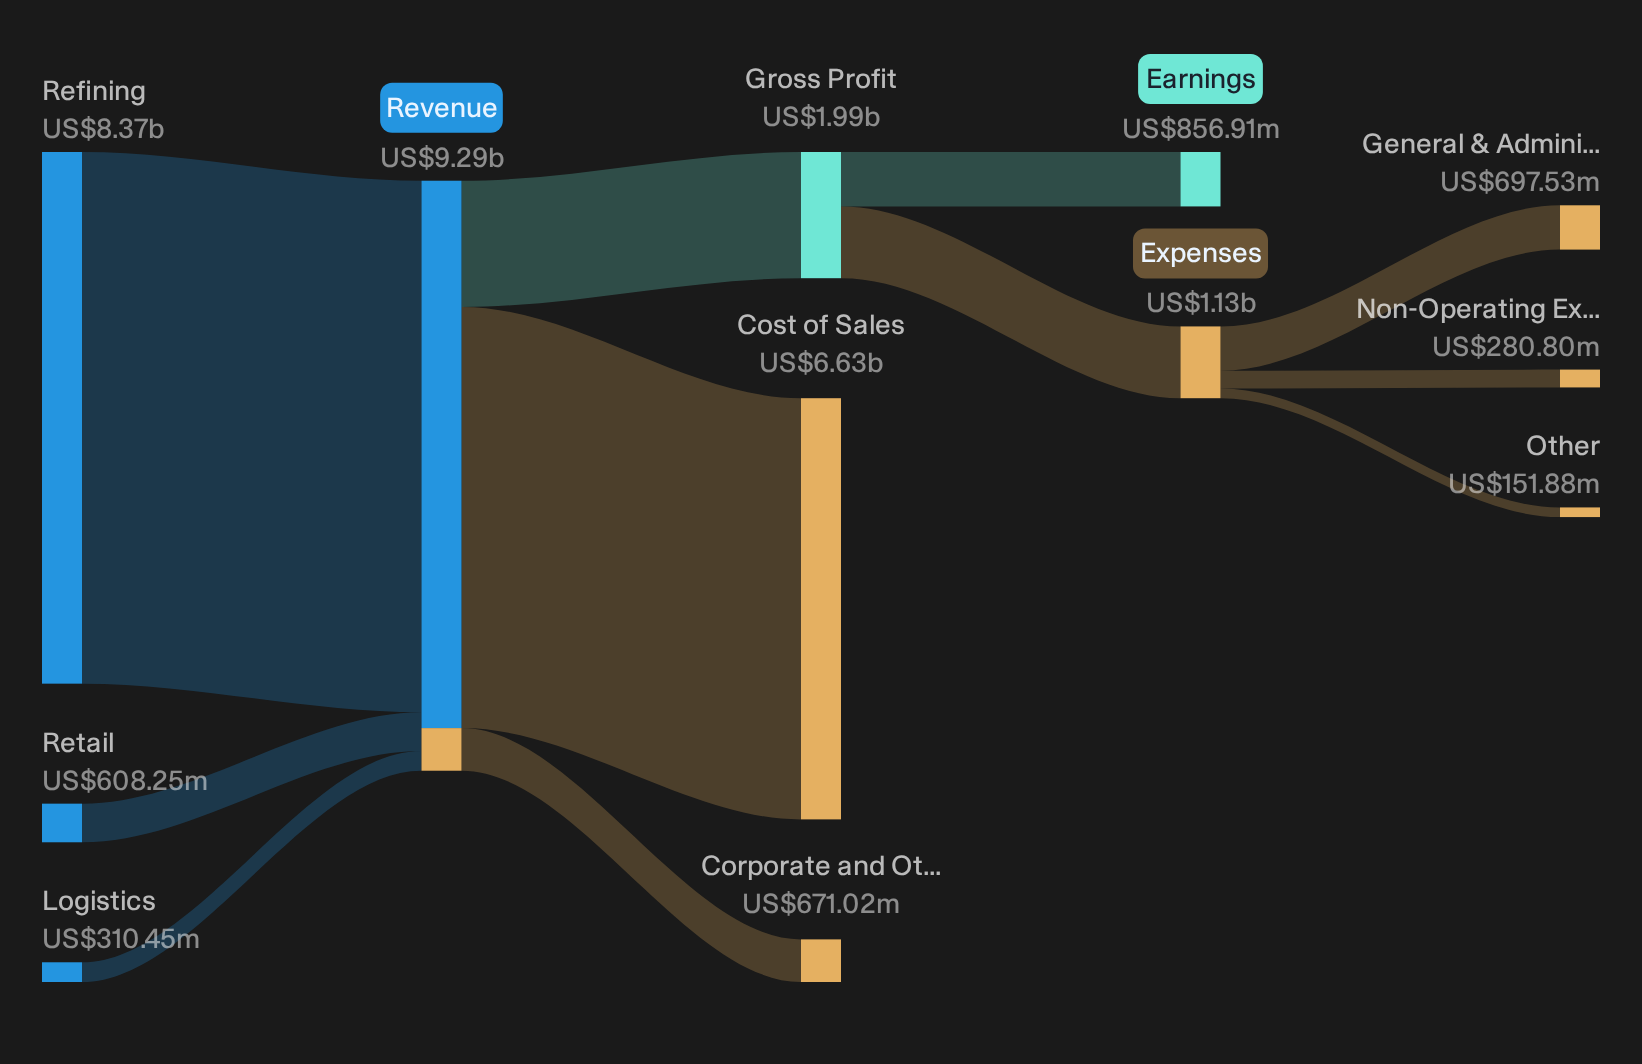
Operations: Par Pacific generates about US$8.4b from refining, US$608 million from retail and US$310 million from logistics, offset by corporate charges.
Market Cap: US$4.1b
Par Pacific Holdings gives this integrated majors screen some U.S. downstream flavor, with a mix of refineries, fuel outlets and logistics that tie directly into the current refined product squeeze.
"Sustained growth in Asia-Pacific energy demand, along with minimal increases in Chinese refined product exports, is maintaining strong export opportunities and elevated utilization rates at Par Pacific's Hawaii refinery, which supports continued revenue and margin stability."
What happens if a single pressure point in that refined product trade shifts and the pricing power behind those margins softens?
If that pricing power matters to your thesis, read the full narrative for Par Pacific Holdings to see how Par Pacific Holdings could react if refining margins suddenly decouple.
Xinjiang International IndustryLtd (SZSE:000159)
Overview: Xinjiang International IndustryLtd runs refining, storage, transportation and wholesale operations for oil and chemical products in China and overseas markets.
Operations: Xinjiang International IndustryLtd generates about CN¥985 million from oil and chemical wholesale, CN¥940 million from manufacturing and CN¥50 million from warehousing, almost entirely in China.
Market Cap: CN¥2.6 billion
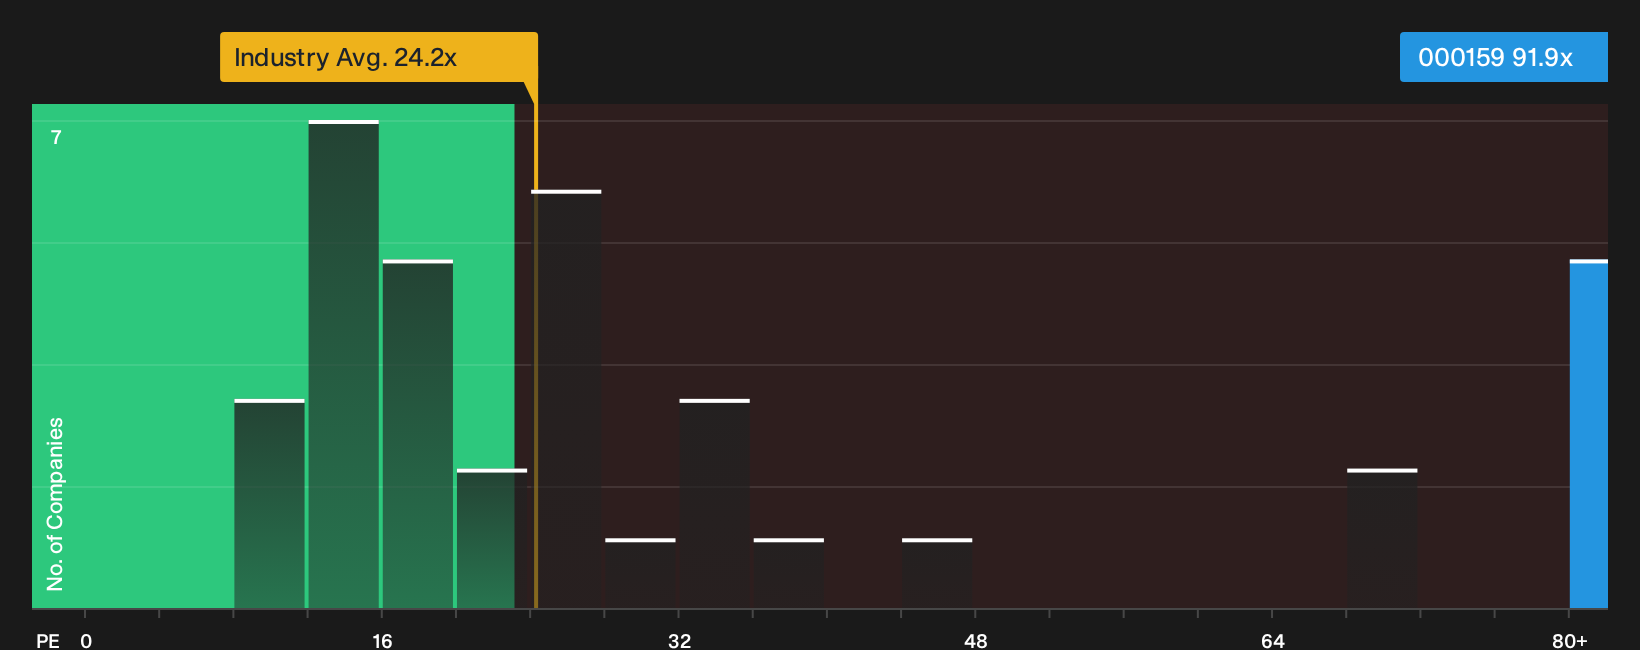
Xinjiang International IndustryLtd provides exposure to the integrated oil and gas theme through refining, storage and wholesale, offering downstream exposure connected to global crude flows and domestic Chinese demand. Fresh profitability this year and exposure to higher crude prices are balanced against a high P/E and low ROE. The outlook will be influenced by how one currently unseen pressure on downstream margins develops from here.
That hidden pressure point matters for your risk reward, so read the 1 key reward and 2 important warning signs (2 are major!) for details on how Xinjiang International IndustryLtd’s premium valuation could react.
Saudi Arabian Refineries (SASE:2030)
Overview: Saudi Arabian Refineries focuses on crude oil extraction and related energy investments in Saudi Arabia, linking directly into regional export flows.
Operations: The business records a decline of SAR 25 million in Oil & Gas Refining & Marketing revenue, entirely from within Saudi Arabia.
Market Cap: SAR764 million
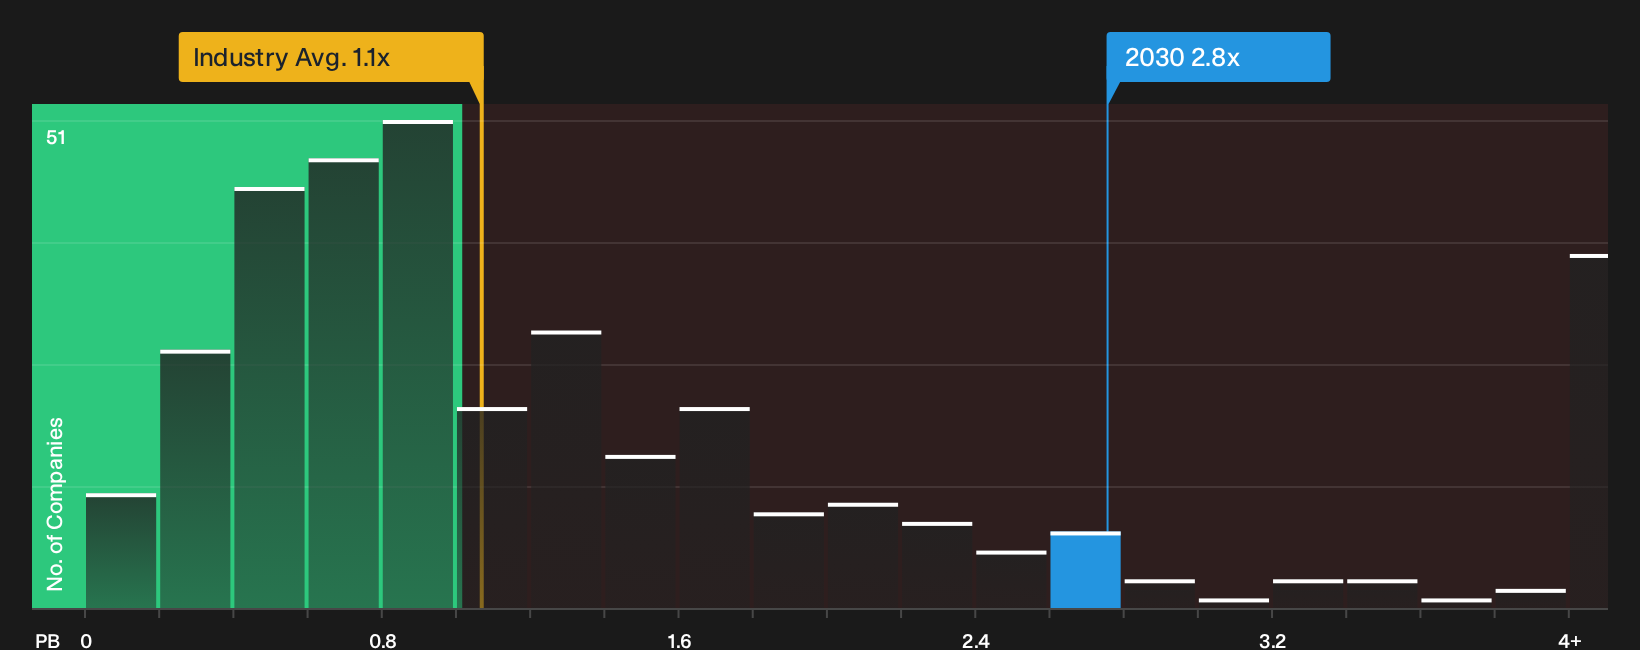
Saudi Arabian Refineries provides this integrated majors screen with direct exposure to Saudi crude production and Hormuz-linked export pricing, combined with a very small revenue base, losses and a relatively high P/B. Investors seeking pure upstream leverage to movements in Brent prices may monitor the company, depending on how one unresolved profitability issue develops.
That unresolved issue is exactly why the analysis report for Saudi Arabian Refineries could help you see whether Saudi Arabian Refineries’ small revenue base masks bigger swings ahead.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Prices react fast, stories spread and the best entries get caught early while it matters and before the crowd piles in, act now.
- Spot under the radar quality before it starts breaking out by scanning the 19 high quality undiscovered gems while they are still quietly building momentum.
- Stack your watchlist with durable balance sheets built to handle shocks by running the list of solid balance sheet and fundamentals (25 results) while prices still look reasonable.
- Target cash generative yield plays that keep paying even when markets swing by using the 7 dividend fortresses before income hunters push them higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com