
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Visteon (VC) Stock Stays Hard To Call On Earnings Alone
Visteon has seen its share price fall back over the past few years, which puts fresh attention on a basic question. Are investors paying a sensible price for the earnings this auto technology supplier currently produces?
- The stock has declined 30.6% over the past 3 years, which puts the current valuation debate squarely on whether those weaker returns already reflect its earnings power.
- For a business tied to automotive electronics and cockpit systems, a key consideration is how efficiently it can convert design wins into steady profits and cash flow, since that stream is what ultimately needs to support today's equity value.
- The analysts covering Visteon have run their own numbers. See what analysts think Visteon's shares could be worth.
The issue now is whether the price investors see on Visteon today lines up with what its earnings suggest the stock should reasonably be worth.
To put Visteon's recent share price slide in context and compare how other auto related companies trade on earnings, it can help to scan a broader group using the 27 high quality undervalued stocks
Is Visteon Fairly Priced on Earnings?
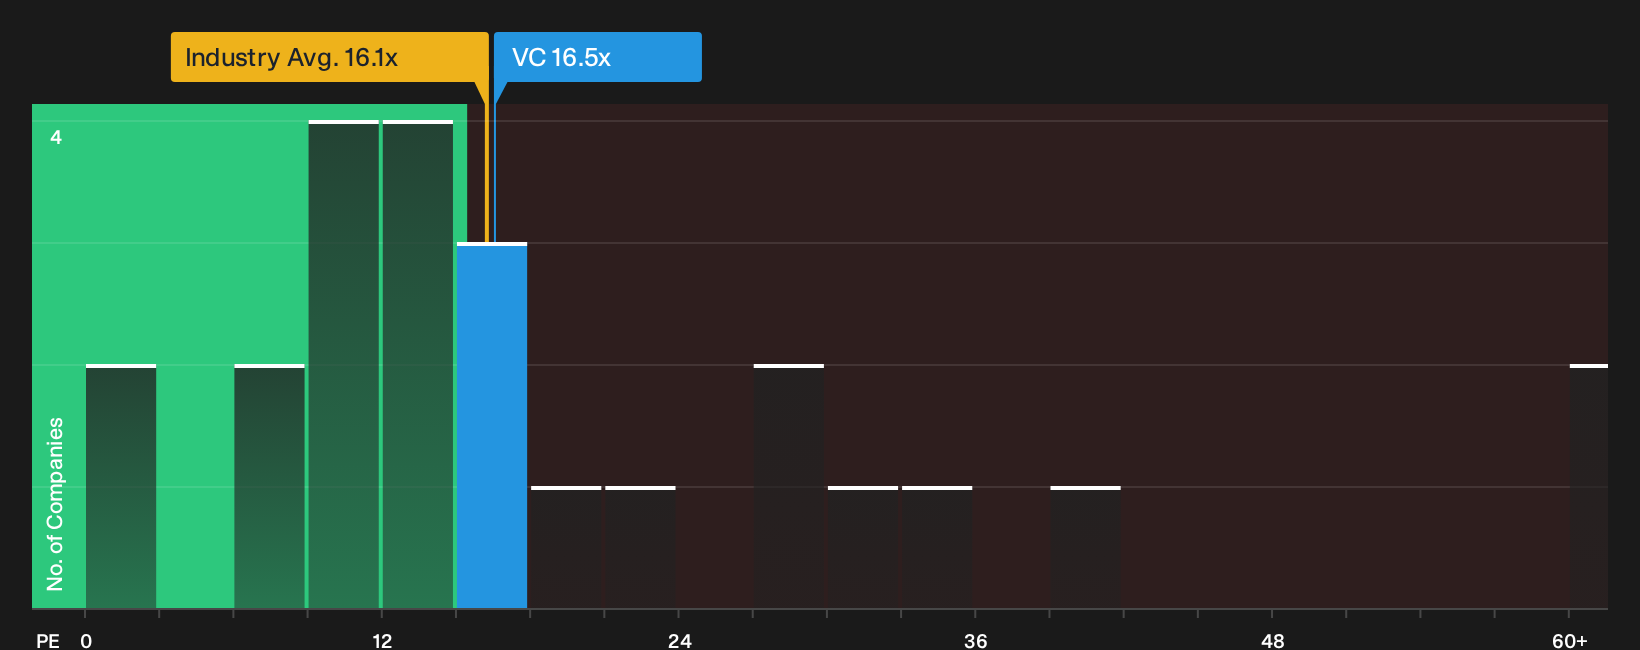
The P/E ratio fits Visteon because earnings remain the core yardstick for an established auto components supplier. Visteon currently trades at about 16.5x earnings, which is close to the 16.1x average for the wider Auto Components industry. That keeps the stock in the same general valuation zone as the sector rather than at a steep premium or clear discount.
Analysts' fair multiple model, which blends Visteon's growth profile, margins, size and risk, points to a level slightly under the current 16.5x. The gap between that tailored yardstick and where Visteon trades now is not large, so the P/E suggests the stock is about right compared with what its recent earnings justify. To judge whether that feels comfortable, you would want to weigh how durable those profits look across an auto cycle and how much certainty you want before paying this kind of earnings multiple. Explore the numbers behind Visteon's P/E valuation.
The Visteon Narrative: What Would Justify Today's Price?
Narratives for Visteon pick up from that P/E puzzle and explain which assumptions on future growth, profitability and earnings strength would need to hold for the stock to be worth significantly more or less than it is today, and they sit on Simply Wall St's Community page. Each one treats Visteon's fair value as a thesis you can track over time, rather than a single fixed estimate, so you can see how the story holds up as new information arrives.
One of the top community narratives on Visteon: 39% undervalued
"With global OEMs demanding outsourced sustainable and regulatory-compliant next-generation electronics, Visteon's proven execution and cost advantage will drive premium share gains…"
Discover why this Narrative puts Visteon at 39% undervalued.
For Visteon, who is steering the ship matters as much as the sticker price
The next question is who actually runs Visteon, how their pay is structured, and whether those incentives line up with the outcomes shareholders care about most. See who runs Visteon and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com