
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Texas Energy Campus Change NextEra Energy Stock Narrative
- NextEra Energy Resources was selected with Related Companies and Lewis Energy Group to develop Project Star in Encinal, Texas, a more than US$22b energy campus with 6.47 GW of natural gas generation supporting a nearby 5 GW digital infrastructure site and supplying excess power to the grid.
- The Project Star partnership gives NextEra Energy a large contracted-style natural gas platform alongside its renewables and storage portfolio, which could reshape how its generation mix serves fast growing data center demand and long duration power needs.
- Attention now turns to how NextEra Energy's Project Star role, and its 6.47 GW of planned gas capacity, could influence the broader investment narrative.
Scan beyond NextEra Energy and size up other grid and data infrastructure beneficiaries with the hand-picked 39 power grid technology and infrastructure stocks, now feeding into AI and data center demand.
NextEra Energy Investment Narrative Recap
To own NextEra Energy, you need to believe the company can keep turning very large capital plans at Florida Power & Light and Energy Resources into rate base growth and contracted cash flows while managing a heavier interest bill. The Wolfe conference appearance gives management another forum to explain how data center driven load, Project Star and the Dominion proposal fit together or create trade offs.
The biggest near term swing factor is still execution and regulatory risk around the Dominion Energy application and broader approvals for new generation. The recent FERC filing response looks important procedurally but does not change the core risk that tougher conditions or delays could affect returns if regulators push harder on customer bill impacts and allowed equity yields.
The FERC Answer tied to the Dominion Energy deal is the announcement that matters most for this news flow. Project Star and the planned up to 10 GW of new gas resources only fully pay off if the balance sheet can handle them alongside any Dominion related commitments, without interest expense squeezing earnings more than it already has.
Investors listening to John Ketchum at Wolfe will likely be focusing on how management prioritises between Dominion, Project Star and the 35.1 GW renewables backlog if financing or policy supports become less favourable. That hearing also gives a platform to address concerns over interest coverage, dividend funding and the extent to which new contracted gas and storage can offset those financial pressures.
What The Consensus Numbers Assume For NextEra Energy
NextEra Energy's narrative projects US$39.9b revenue and US$10.6b earnings by 2029. This rests on analysts modelling 11.6% yearly revenue growth and an earnings increase of about US$1.3b from US$9.3b today.
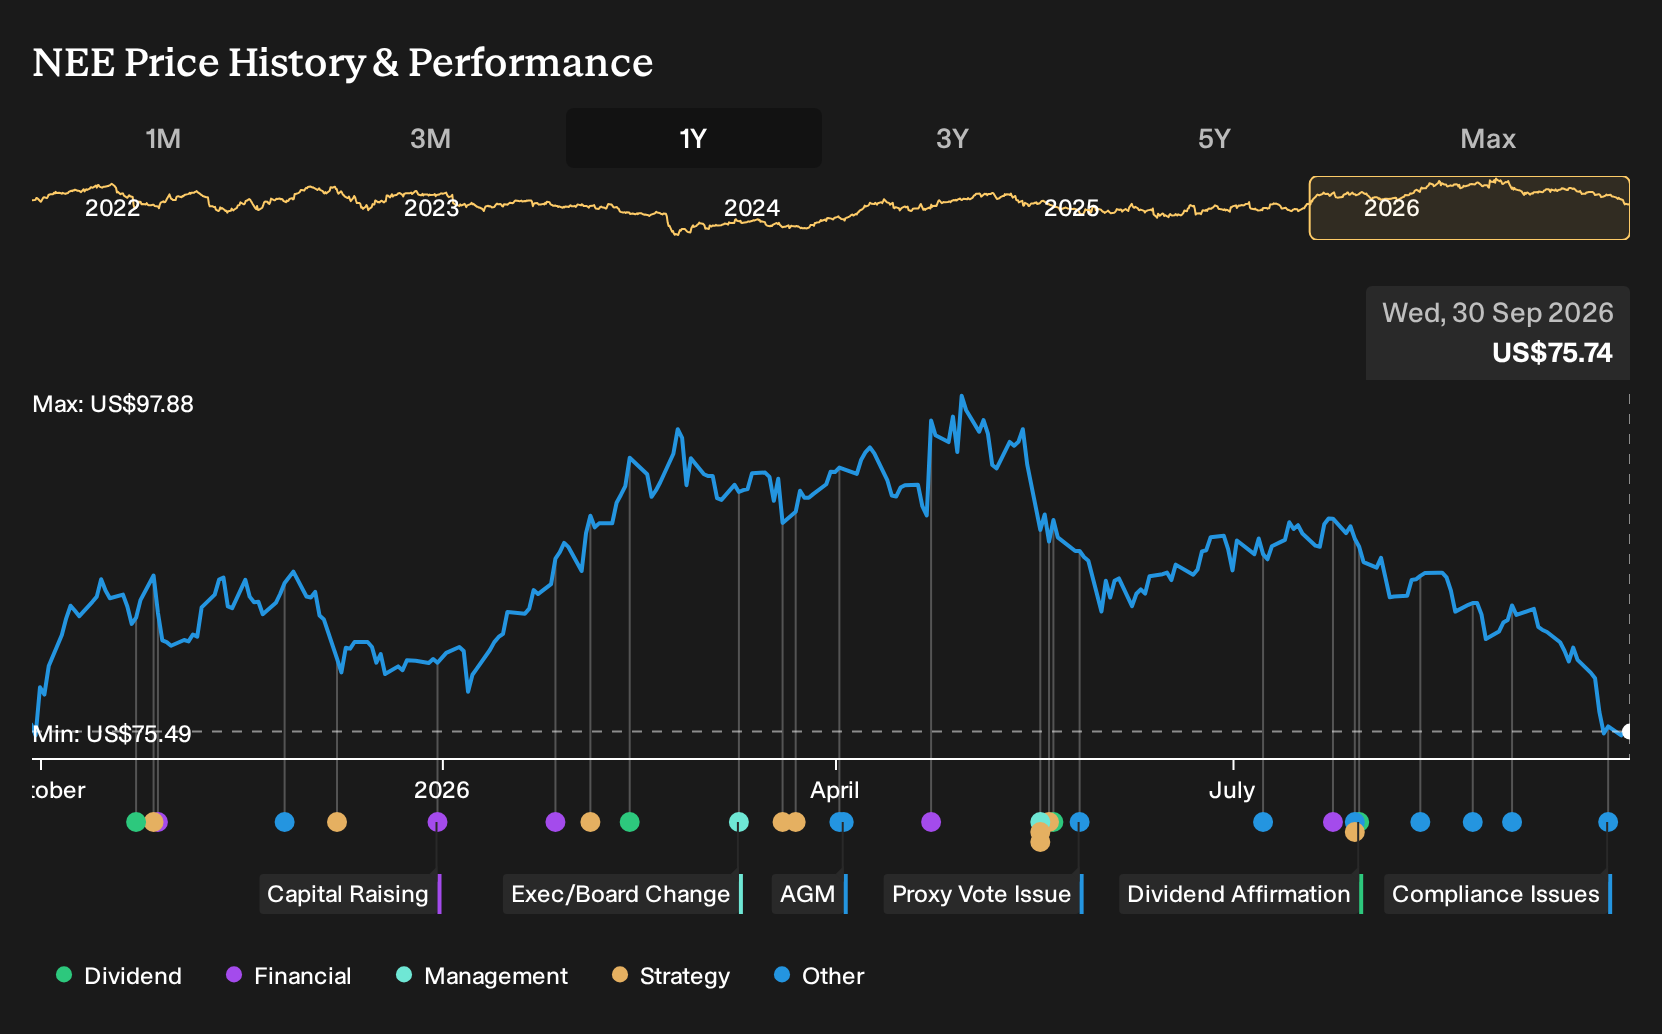
Uncover why NextEra Energy's fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate story on NextEra Energy focuses on regulatory pushback. The most cautious analysts were estimating revenue of about US$33.3b and earnings of roughly US$9.9b by 2029 before this Project Star news. That outlook is far more conservative, so treat today’s headlines as a reason to compare several competing narratives.
Explore 9 other NextEra Energy fair value estimates, including one that suggests it could be worth just $76.65.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your NextEra Energy research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NextEra Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NextEra Energy's overall financial health at a glance.
Looking for more investment ideas beyond NextEra Energy?
Once you have a view on NextEra Energy, it can help to cross check that thesis against other opportunities with different risk profiles, income streams and balance sheet strength using the Simply Wall St Screener.
- If capital preservation comes first for you, filter for companies with resilient financial profiles through the 31 resilient stocks with low risk scores.
- Income focused investors can zero in on reliable cash payouts by scanning the 7 dividend fortresses built around higher yielding payers.
- For those hunting for less crowded stories with solid fundamentals, sort through the 19 high quality undiscovered gems and see what others might be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com