
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Fuel Stocks Retail Investors Are Watching As Diesel Supply Risks Grow
Fuel markets are being pulled in several directions at once, with talk of a US diesel export ban, emergency reserve releases in Europe and record UK pump prices all feeding into the same story of tight supply and policy risk. Extreme moves like these often create mispricing. That can reward investors who understand which integrated oil and gas stocks are most exposed to this diesel shock. This article walks through 3 such companies from our Global Integrated Oil & Gas Producers screener and explains how this backdrop could influence each stock, so you can decide whether they deserve a closer look.
The three fuel-linked giants covered below are only a sample, as the full screen surfaced 22 more integrated oil and gas producers with equally compelling stories that are not unpacked in this article. To size up that broader field, head straight to the Global Integrated Oil & Gas Producers screener to identify, analyze, and focus on the highest-conviction ideas for your watchlist.
Verbio (XTRA:VBK)
Overview: Verbio produces and distributes biodiesel, bioethanol, biomethane and other bio-based fuels internationally, tying its fortunes closely to global fuel pricing.
Operations: Verbio generates most of its revenue from biodiesel at about €951 million and bioethanol including biomethane at roughly €899 million.
Market Cap: €1.8b
Verbio fits this fuel-focused screen as a vertically linked biofuel producer that can plug into diesel-sensitive sectors without relying on crude refining.
"The anticipated tightening of biofuel supply as higher-cost competitors reduce output, combined with gradual policy improvements, such as stricter fraud controls and quota increases across Europe, is likely to support a material recovery in greenhouse gas (GHG) quota prices, directly impacting Verbio’s revenue and EBITDA as each €1 rise in quota price increases annual EBITDA by €1 million."
What really matters for Verbio now is how one quiet policy-driven pressure ultimately feeds through to margins and long-term cash generation.
To see how that margin story could accelerate or stall, read the full narrative for Verbio to understand what the market might be missing on policy, pricing and scale.

World Kinect (WKC)
Overview: World Kinect is an energy management group that sources, supplies, and coordinates fuel and related services across aviation, land, and marine customers worldwide.
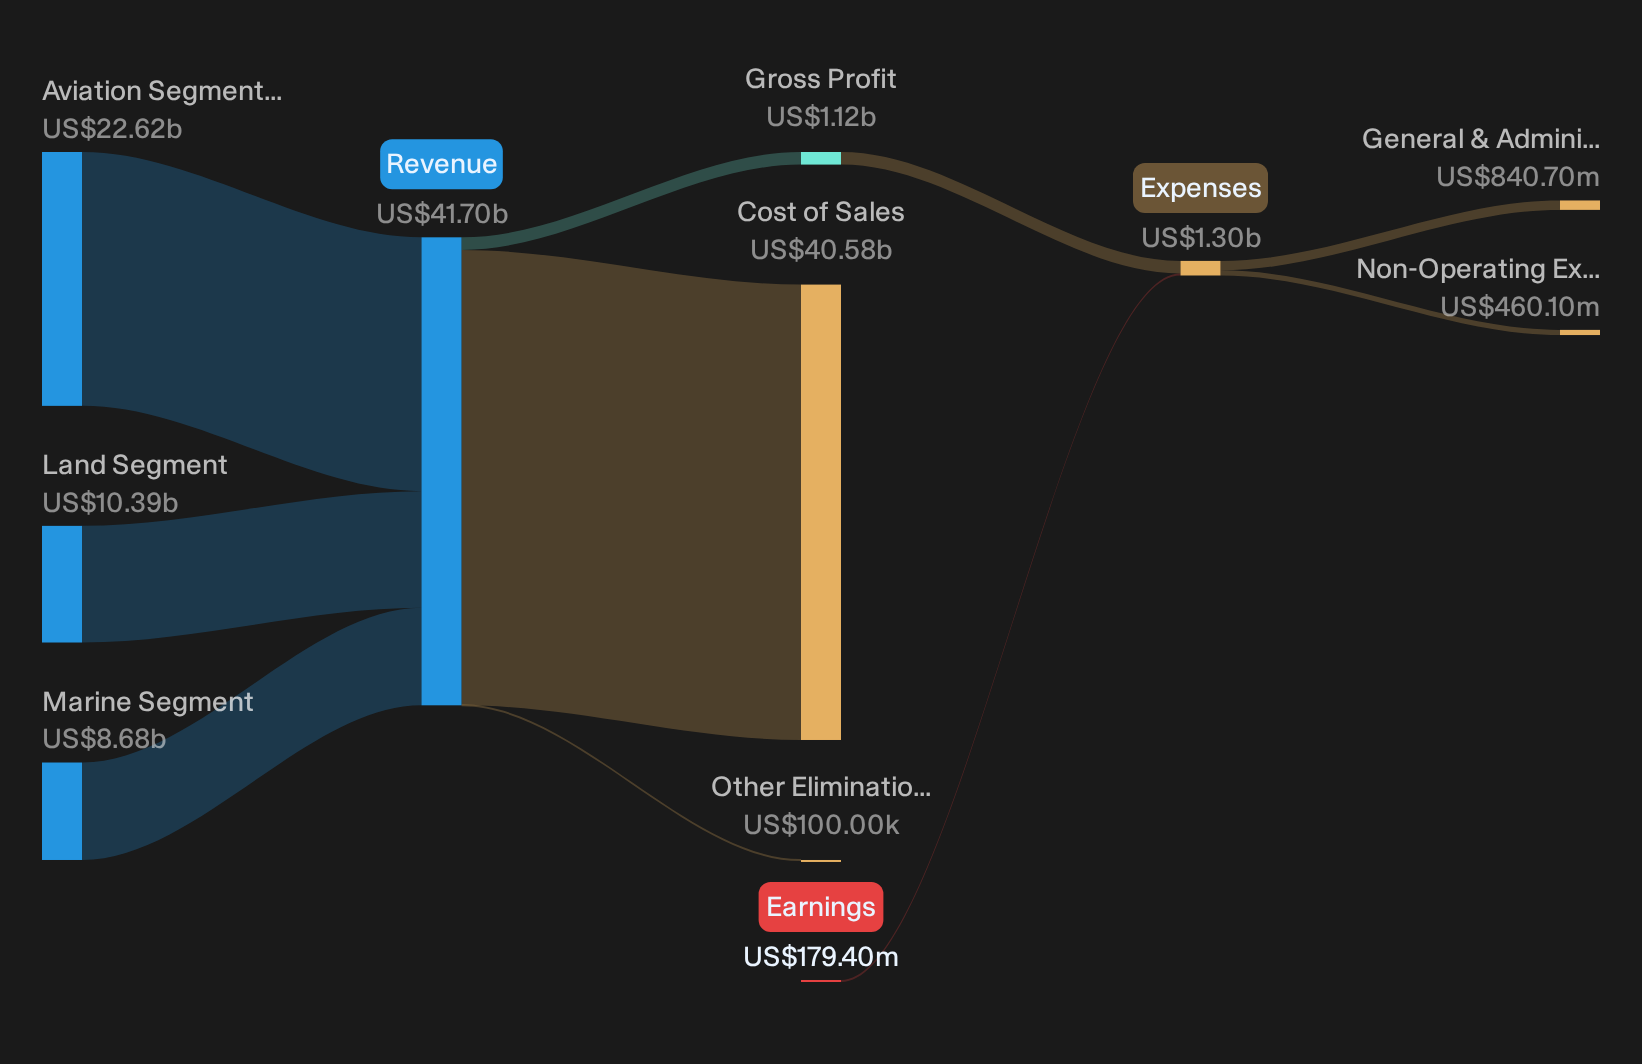
Operations: World Kinect generates most of its revenue from aviation at about US$22.6b, with land at roughly US$10.4b and marine near US$8.7b.
Market Cap: US$1.8b
World Kinect plugs into this integrated energy theme as a downstream fuel distributor and logistics partner that sits closest to end users. As a result, the business feels diesel volatility and supply security concerns in real time and can potentially turn those pressures into higher value services for customers that need reliability.
"The company is exceptionally well-positioned to address global demand for renewable fuels and carbon reduction solutions, having already built operational capabilities and customer relationships in renewables. This early focus could support the development of new revenue streams as regulation and customer preferences evolve, with implications for both topline and margins."
The key variable for World Kinect is how developing pressure on diesel-dependent customers ultimately feeds through to pricing power and profitability.
That pricing power question is exactly where it gets interesting, and the full narrative for World Kinect shows whether World Kinect’s renewables push is accelerating upside or quietly masking risk.
NWF Group (AIM:NWF)
Overview: NWF Group is a UK distributor of fuel oils, food logistics services and animal feeds, linking suppliers to domestic and commercial customers.
Operations: NWF Group generates around £645.8 million from Fuels, £193 million from Feeds and £90.7 million from Food, almost entirely in the UK.
Market Cap: £78.9 million
NWF Group plugs into the Global Integrated Oil & Gas Producers theme at the downstream end, where reliable refined fuel supply and pricing shape earnings sensitivity.
"Although the rollout of the regional Fuels operating model is improving miles per drop and price per liter, the complexity of consolidating 30 depots into 9 hubs could dilute the efficiency gains and limit the anticipated uplift in operating margins and earnings."
The appeal of NWF Group now largely depends on how one unresolved execution choice filters through to downstream margins and cash generation.
To see how that execution risk could flip into an advantage, read the full narrative for NWF Group and identify where NWF Group’s fuel model might be quietly accelerating earnings quality.

Curious About What You’re Missing?
Fresh opportunities often move first, then headlines follow. Spot breakouts, catch quiet momentum, and find stocks still under the radar for now.
- Search for sturdier compounding by scanning companies with strong balance sheets and fundamentals using the list of solid balance sheet and fundamentals (206 results) before others notice potential changes.
- Look for emerging AI leaders by tracking cash-generative operators via the 37 profitable AI stocks that aren't just burning cash while enthusiasm is developing and potential mispricing may exist.
- Review metal producers in the 17 top copper producer stocks to better understand how changing valuations and sentiment could affect potential supply dynamics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com