
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How FTSE All World Removal Will Impact Interpump Group Stock Investors
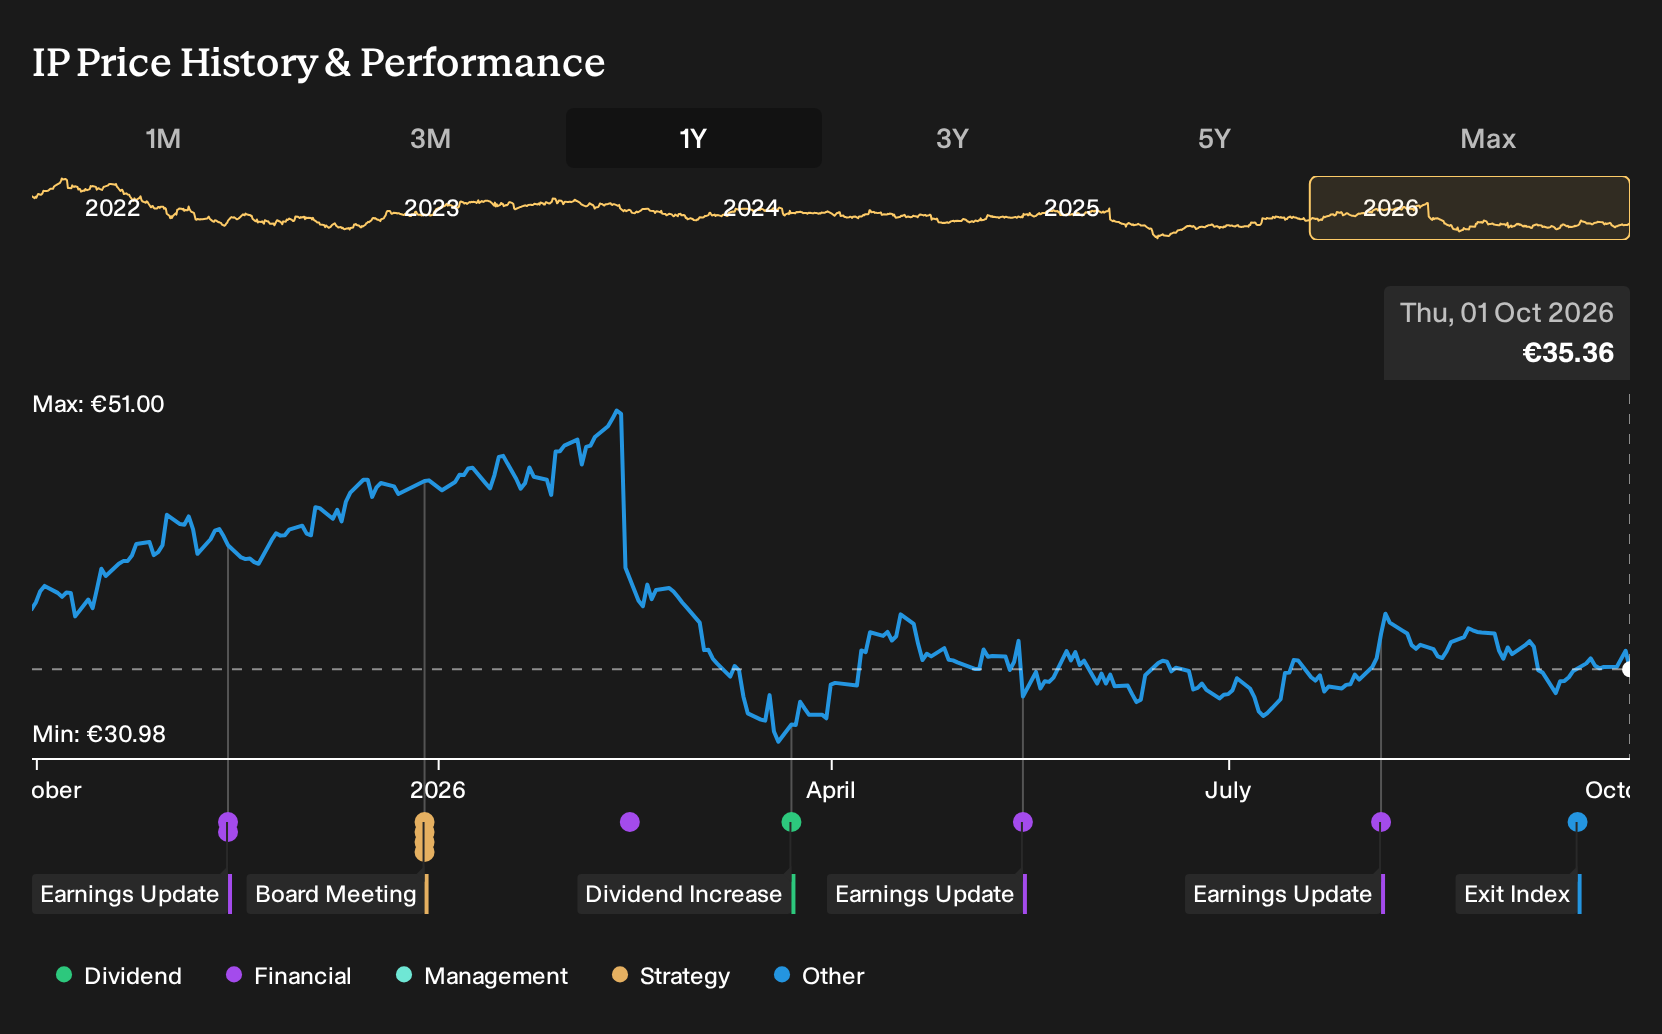
- Interpump Group S.p.A. was removed from the FTSE All-World Index (USD) on 19 September 2026, a change that can alter how index-linked investors are exposed to the business.
- This exclusion may reduce mechanically driven index ownership at a time when Interpump Group’s fundamentals are closely tied to demand for eco-efficient high-pressure pumping and water-jetting solutions across infrastructure and industrial markets.
- The focus now turns to what Interpump Group’s index removal could mean for the existing investment narrative built around diversification and eco-efficient water-jetting demand.
Compare how Interpump Group’s index exit stacks up against other industrials by scanning a curated set of list of solid balance sheet and fundamentals (206 results) that may be less exposed to benchmark reshuffles.
Interpump Group Investment Narrative Recap
To own Interpump Group, you need to believe in a steady build in demand for eco efficient high pressure pumping, hydraulics and water jetting across infrastructure, industrial cleaning and agriculture. The near term swing factor is still execution in Hydraulics, where a fragile normalization in orders can influence how quickly the wider group feels more stable.
The FTSE All World exit mainly affects how some passive funds hold the stock, not the industrial reality on the ground, so the operating story is broadly unchanged. The bigger risk is weak visibility in North America and Hydraulics, where prolonged softness or tariff shocks could unsettle revenues and margins again.
There have been no fresh operating announcements tied directly to this index change, so the most relevant reference point for Interpump Group remains the earlier focus on eco efficient Water Jetting and the acquisition pipeline. Management has highlighted a full M&A funnel including assets such as White Drive and Padoan, which keeps integration quality firmly in the spotlight.
For investors, that link matters because the same factors that drive potential future catalysts, such as margin improvement from higher value water jetting and any recovery in Hydraulics, also shape how the stock absorbs technical hits such as benchmark removal. If synergy delivery stalls or restructuring drags on profitability, headline index moves could amplify sentiment swings around an already sensitive earnings path.
Interpump Group's current analyst storyline points to revenues of €2.3b and earnings of €285.3m by 2029, based on 4.0% yearly revenue growth and an earnings increase of about €76.8m from €208.5m today.
Uncover how Interpump Group's fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Simply Wall St Community members offer three fair value views for Interpump Group, ranging from €30.21 to €45.56, which shows how far apart retail opinions can sit. Those assessments do not yet factor in the FTSE All-World removal, so you should weigh them against Hydraulics fragility, tariff risk, and M&A execution questions.
Explore 2 other Interpump Group fair value estimates, including one that suggests as much as 29% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Interpump Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Interpump Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interpump Group's overall financial health at a glance.
Looking for more ideas beyond Interpump Group?
If you are reassessing Interpump Group after its FTSE All-World exit, it can help to line it up against other companies with different balance sheet strength, risk profiles, and income potential.
- For investors who want financial resilience front and center, start with a list of solid balance sheet and fundamentals (206 results) that can help you compare Interpump Group to peers with similarly robust fundamentals.
- If you are hunting for potential mispriced opportunities, scan a 196 high quality undervalued stocks to see which other businesses the Screener currently flags as trading below their estimated worth.
- Anyone building an income-focused portfolio can review a 157 dividend fortresses to find stocks generating meaningful yield while still passing basic quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com